Gulf Energy Development Plc’s subsidiary, Gulf International Holding Pte Ltd (GIH), entered into a share purchase agreement with Vietnamese entrepreneurs Nguyen Tran Thao Nhi and Tran Thi Minh Trang to acquire a 100-per-cent stake in Dien Xanh Gia Lai Investment Energy Joint Stock Company (DGI), according to its filing with the Stock Exchange of Thailand today.
DGI is the developer and operator of two Onshore Wind Farm Projects – la Pech 1 and 2 – which have a contracted capacity of 50 megawatts each.
Both projectswill generate and sell electricity to Vietnam Electricity (EVN) for 20 years. Gulf is expected to spend approximately US$200 million (Bt6.2 billion) on building the project. Construction will begin in 2021 and the projects should start commercial operation by the fourth quarter of 2022.
By The Washington Post · Rachel Siegel · BUSINESS, HEALTH, US-GLOBAL-MARKETS JOBS-ANALYSIS
WASHINGTON – The U.S. unemployment rate is expected to stay above its pre-pandemic levels through the end of 2030, according to a 10-year economic report released Thursday by the Congressional Budget Office.
The agency is predicting that the unemployment rate in the fourth quarter of 2030 will be 4.4%. The current level, according to data published Thursday by the Labor Department, is 11.1%. Before the spread of the coronavirus pandemic shut down vast swaths of the American economy, unemployment had reached 50-year lows, coming in at 3.5% in February.
The new projection shows the long-term tail impact that economists believe the coronavirus pandemic will have on the U.S. economy, which is the largest economy in the world. A severe disruption to production and hiring in March and April has had a jarring impact on the United States.
The country’s economic outlook over the coming decade has “deteriorated significantly” since the CBO published its full baseline economic projections in January, the agency said. The agency on Thursday also said that economic growth for the second half of 2020 is now expected to be slower than projections published in May, which focused on the U.S. economy this year and next.
The latest projections showed that real GDP is expected to grow at a 12.4% annual rate in the second half of 2020 and recover to pre-pandemic levels by mid-2022. The unemployment rate is expected to peak at over 14% in the third quarter of this year, the report said.
In May, the CBO estimated that real GDP would contract by 11% in the second quarter of this year, equivalent to a 38% drop at an annual rate. The May report also projected that in the second quarter, almost 26 million fewer Americans would be employed than in the fourth quarter of 2019.
At a news conference following Thursday morning’s jobs report, President Donald Trump said the economy was “coming back extremely strong.” Earlier this week, senior White House economist Larry Kudlow said that the “overwhelming” evidence pointed to a V-shaped recovery.
But many economists and lawmakers caution that the jobs data reflects a survey taken in the middle of June – before a surge in cases pushed multiple states to reimposed restrictions and scale back reopening plans. That means scores of Americans have now been kicked out of the workforce for a second time. This week also marked the 15th straight week of unemployment claims that topped 1 million.
On Wednesday, the country reported 52,789 new coronavirus cases, marking the largest single-day total since the start of the pandemic. A growing number of health officials, lawmakers and economists say controlling the virus is crucial for the economic recovery. Minutes released Thursday from the Federal Reserve’s June meeting showed that officials at the central bank are concerned that the United States could enter a much worse recession later this year if infections continue to mount.
The price of gold rose by Bt100 per baht weight in morning trade on Friday (July 3), the Gold Traders Association reported.
As of 9.24am, buying price of a gold bar was Bt26,050 per baht weight and selling price Bt26,150, while gold ornaments were priced at Bt25,574.92 and Bt26,650, respectively.
At close on Thursday (July 2), buying price of a gold bar was Bt25,950 per baht weight and selling price Bt26,050, while gold ornaments were priced at Bt25,483.96 and Bt26,550, respectively.
The price of gold contracts in Comex (Commodity Exchange) to be delivered in August rose by US$10.1 per ounce or 0.57 per cent, closing at $1,790 per ounce at yesterday’s close.
Investors were buying gold as a safe haven asset due to uncertainty following the Covid-19 outbreak as the number of new cases worldwide continue to increase
The Stock Exchange of Thailand (SET) Index rose by 3.18 points, or 0.23 per cent to 1,377.31 in the morning session on Friday (July 3).
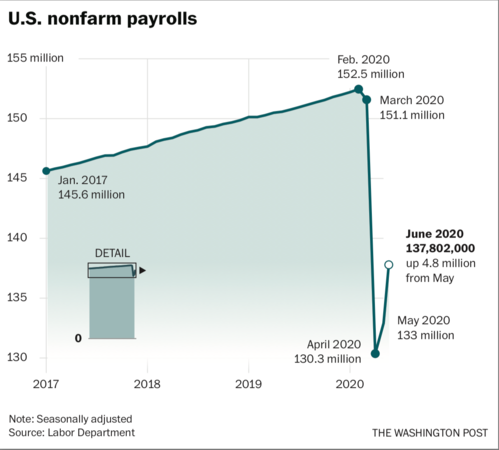
A stock analyst at Krungsri Securities expected the index to rise between 1,385 and 1,390 on hopes of a US economic recovery after the US June non-farm payrolls rose by 4.8 million jobs and June unemployment rate dropped to 11.1 per cent.
“Besides, the market gained positive sentiment from the rising crude oil price after Opec-plus cut June crude oil exports by 1.84 million barrels per day to 17.2 barrels per day,” the analyst said.
Meanwhile, the analyst advised investors to beware of mass sell-offs due to uncertainty following the second coronavirus wave after the number of new cases in US continued to rise, and the tight SET valuation as the index’s price to earnings ratio was 19.5 times.
“The New York Stock Exchange was closed due to the US independence day,” the analyst added.
He recommended that investors buy:
▪ Energy stocks that benefit from the rising crude oil price, such as PTT, PTTEP, Top, PTTGC, IRPC, SPRC and IVL.
▪ Stocks whose second-quarter performance will improve, such as CKP, Tasco and STA.
▪ Stocks that benefit from the Cabinet’s domestic tourism stimulus measures, such as MINT, CENTEL, ERW, AOT and AAV.
The SET Index rose by 25 points, or 1.83 per cent, on Thursday (July 2), closing at 1,374. Total transactions amounted to Bt84 billion on hopes of Pfizer and BioNTech’s Covid-19 vaccine testing and increasing US, euro-zone, and China’s manufacturing purchasing managers’ index in June.
Foreign investors made net sales in stocks worth Bt614 million and net buys in bonds worth Bt1.613 billion. There are 5,612 net long TFEX SET50 contracts.
By The Washington Post · Eli Rosenberg, Heather Long, Jeff Stein · NATIONAL, BUSINESS, US-GLOBAL-MARKETS
WASHINGTON – The U.S. economy added a record 4.8 million jobs in June, according to federal data released Thursday, but a surge in new infections and a spate of new closings threatens the nascent recovery.
Two key federal measurements showed the precarious place the economy finds itself in three and a half months into the pandemic as the country struggles to hire back the more than 20 million workers who lost their jobs in March and April.
Unemployment claims
While companies have continued to reopen, a large number of Americans are finding their jobs are no longer available. The unemployment rate in June was 11.1 percent, the Bureau of Labor Statistics said, down from a peak of 14.7 percent in April but still far above the 3.5 percent level notched in February.
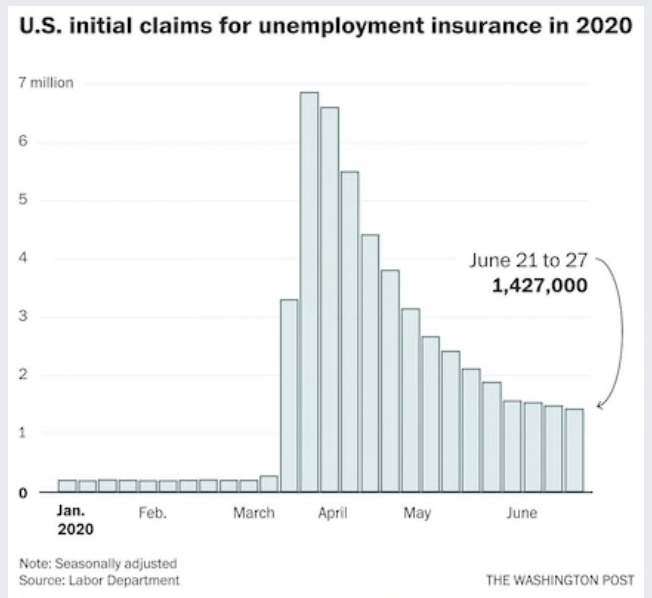
And another 1.4 million Americans applied for unemployment insurance for the first time last week and more than 19 million people are still receiving unemployment benefits, stubbornly high levels that show how many people are struggling to find or keep work.
The Congressional Budget Office on Thursday said the coronavirus pandemic gave such a shock to the labor market that it would not fully recover for more than 10 years.
Snanpsho of jobs in the U.S.
President Trump touted the jobs that were added at a news conference called shortly after they were released, saying they were a sign that “America’s economy is now roaring back to life like nobody has ever seen before.”
“All of this incredible news is the result of historic actions my administration has taken,” Trump said.
But his top aides acknowledged there was still a long way to go.
“There is still a lot of hardship, and a lot of heartbreak, in these numbers,” National Economic Council Director Larry Kudlow said. “I think we have a lot more work to do.”
The stock market initially rose on the news, with the Dow Jones industrial average rising 400 points, or 1.5 percent, before retreating. It closed up 92 points on the day.
Economists called the 4.8 million jobs added encouraging, saying they were a sign that the massive financial incentives that Congress passed appeared to have succeeded at stanching even greater job loss.
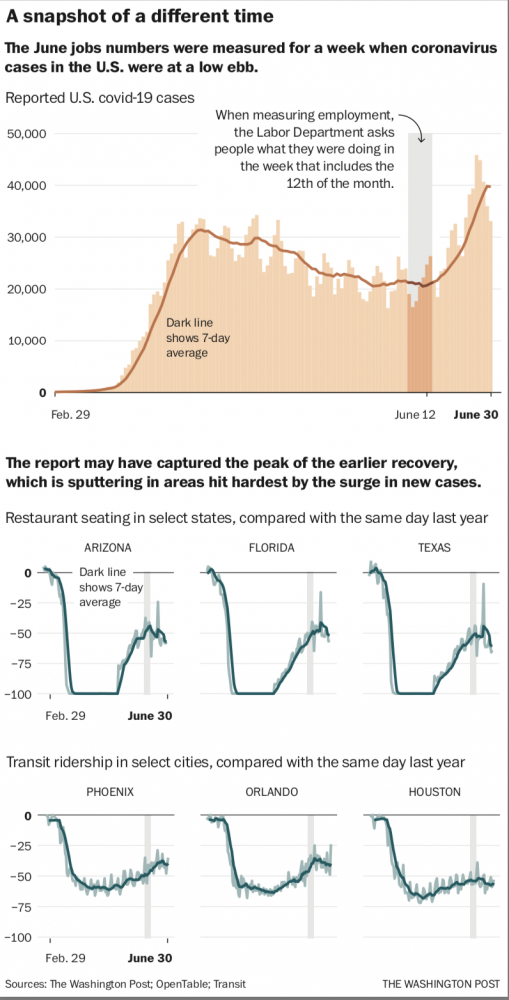
But the good news came with a couple of significant asterisks: It was gathered the week of June 12, when the country was reporting less than 25,000 new cases a day, not the current average of more than 40,000 that has sent new closures and shutdowns cascading across states and counties.
“The pandemic pushed us into a very deep economic hole,” said Mark Zandi, chief economist at Moody’s Analytics. “We can certainly fall back.”
The more than 14.7 million people who are still out of work have left the country with an unemployment rate higher than any point during the Great Recession.
The unemployment insurance data, based on statewide claims that are separate from the survey that informs the jobs report, paints an even less sanguine picture: Last week was the 15th straight where unemployment claims exceeded 1 million, a sign that the economic recovery has not taken hold for many Americans.
The strong month of job gains was driven by robust hiring in the leisure and hospitality sector, with 2.1 million additional jobs added, accounting for about 40 percent of the total gained for the month. Food services and drinking establishments saw their payrolls swell by 1.5 million people, but they still remain 3.1 million lower than before the pandemic.
These are the industries that are getting hit hard in the past two weeks by new closings, as a numbers of states shuttered bars and restricted restaurant service as they try to get the case surge under control.
Retail gained back 740,000 jobs, though employment remains at less than half its pre-pandemic level; education and health services regained 568,000 jobs and health care 358,000 as people returned to the offices of dentists, physicians and other medical practitioners.
The data bring into sharper focus the turmoil facing the U.S. economy after many businesses sent workers home in March during the beginning of the spike in deaths caused by the virus.
Many companies began rehiring in May and June, but there are signs that some workers are getting laid off for the second time in just a few months.
Others technically remain employed but are working drastically reduced schedules – more than 9 million workers reported working part time because of economic reasons, more than double the level in February before the pandemic. Still a participation rate of 61.5 percent in June, slightly up from April and May but nearly a percentage point below February, indicates that others may be leaving the labor force all together – an echo of the deep economic turbulence in the Great Recession.
Economists said there are other reasons to be concerned as incentives for businesses to retain employees and some benefits that have allowed people out of work to stay afloat financially are winding down without more federal action.
Federal and state officials struggled to time their reopening efforts in April and May, in some cases ignoring warnings from public health officials. Now, cases in some of the states that reopened the fastest, or with the loosest restrictions, are seeing the biggest spikes, such as Florida, Arizona, and South Carolina.
In recent days, Texas shut down all bars just weeks after they had reopened. California announced the closure of bars and indoor dining in 19 counties, more than 70 percent of the state. And at least nine other states have slowed or reversed their reopenings. Restaurant bookings have begun to sink in hard-hit states such as Florida, Texas and Arizona. Job postings on the Indeed website, though up from a low of 39 percent, are still down 24 percent from last year.
Many workers are starting to report being laid off or furloughed for a second time in just a few months.
But those effects will not be captured in these reports for the most part.
In the May jobs report, there was a particular focus on a misclassification error the Bureau of Labor Statistics said it made that marred how it calculated the unemployment rate. On Thursday, it said that issue had been mostly been fixed.
The BLS said the true unemployment rate is probably closer to 12.1 percent, 1 percentage point higher than the official rate it gave. Last month, it said the unemployment rate was 13.3 percent, but the data collection error had artificially lowered it from 16.3 percent. In April, the 14.7 percent official rate was likely closer to 19.7 percent.
The disconnect stems from the way surveyors interview people about their job status, as many Americans are unclear about whether they have actually been laid off or just sent home temporarily.
There are other strains on the economy. Only a third of the 22 million Americans who lost their jobs in March and April have returned to work so far. The number of people who reported permanently losing a job rose by 588,000 in June, bringing the total since February to 2.9 million
“It’s becoming clearer that some of what people hoped were temporary layoffs are now turning into permanent layoffs,” said Donald Marron, an economist at the Urban Institute.
The new unemployment claims, a different measurement which has stagnated around 1.4-1.5 million a week during the last month, remain at more than double the pre-pandemic record, pointing to the magnitude of the crisis. With the supplemental insurance given to gig and self-employed workers, that number was well over 2 million last week.
“I would take solace with these numbers but I wouldn’t pop any champagne,” Zandi said. “It’s ten times what you would see in a well-functioning economy.”
At the start of the pandemic, most workers believed they would quickly be rehired, but as the deadly virus continues to be a danger, more and more businesses are telling workers they will never get their old job back.
The job loss has had a disproportionate affect on people of color as well.
The jobless rate for black people is 15.4 percent and 13.8 percent for Asians. For Latinos, the jobless rate is 14.5 percent.
Federal legislators continue to wrangle over proposals that would continue or extend some of the emergency unemployment benefits that will run out by the end of July. Democrats and the White House are at odds over how to authorize the funds even though there are large numbers of people still out of work.
White House officials told outside advisers on Thursday that the jobs report makes it less likely they will approve legislation that would cost as much as $2 trillion or $3 trillion, according to Stephen Moore, a conservative close to the White House. Moore said the jobs report is also likely to shore up White House opposition to extending the significant increase in unemployment benefits approved by Congress in March.
“There will be a phase four, but this makes the case in their eyes for a smaller one and makes even stronger the case for not extending the unemployment benefits,” Moore said. “You don’t have the sense of crisis you did a few weeks ago.”
Trump and Treasury Secretary Steven Mnuchin on Thursday talked about providing more money for businesses and schools, but Mnuchin said they had not decided on what to do for households.
“Our work is not done until every single American who lost a job because of Covid is back to work,” Mnuchin said.
There are some positive indications about the country’s reopening. Data gathered by the HR software company Kronos on 30,000 private industry businesses and 3.2 million hourly workers found that businesses had by the end of last week recovered more than half – 59 percent – the work shifts they lost between March and April. Even in places where coronavirus cases are still surging, more workers clocked in during the last week of June than at the beginning of the month.
“From February through June, we will have seen an enormous amount of job loss,” Jason Furman, a former top economic adviser to President Barack Obama, said on a conference call organized by Rep. James Clyburn, D-S.C., the chairman of the House’s coronavirus subcommittee. “Whatever happens month to month, the economy is in a much worse place than it was four months ago.”
By Syndication Washington Post, Bloomberg · Rita Nazareth, Vildana Hajric · BUSINESS, US-GLOBAL-MARKETS
U.S. stocks pared gains on speculation that an increase in coronavirus cases could jeopardize an economic rebound from the sharpest contraction on record.
The S&P 500 came off session highs amid a plunge in trading volume ahead of a holiday on news that U.S. virus cases had the biggest increase since May 9. Earlier, Florida reported that infections and hospitalizations jumped the most ever, and Houston had a surge in intensive-care patients. The figures offset data showing that payrolls increased by 4.8 million in June after an upwardly revised 2.7 million gain in the prior month.
The U.S. labor market made greater progress than expected last month digging out of a deep hole, yet optimism over the rebound was tempered by stubbornly high layoffs and a resurgent coronavirus outbreak across the country. President Donald Trump still said the report shows the economy is “roaring back.” Massive monetary and fiscal policy stimulus helped lower borrowing costs and keep the financial system liquid in a time of stress while propelling the stock market higher.
“There’s still a general positive sentiment about how quickly we’re seeing the recovery,” said Chris Gaffney, president of world markets at TIAA Bank. “But we do think you’re going to see the recovery level off, especially if we continue to see higher case numbers on the virus.”
Investors also assessed remarks from White House Economic Adviser Larry Kudlow, who told Fox Business Network that “we are very unhappy with China” and that “there are going to be export restrictions.”
U.S. stocks are poised to rise this quarter if history is any guide, according to Keith Lerner, chief market strategist at SunTrust Private Wealth Management. Lerner cited the S&P 500’s track record after its biggest quarterly gains since 1950 in a report Tuesday. The gains ranged from 15% to 22%, in line with last quarter’s 20% increase, according to data compiled by Bloomberg. In each case, the S&P 500 rose in the following quarter. The average advance was 8.4%.
– – –
These are some of the main moves in markets:
Stocks
– The S&P 500 gained 0.5% as of 4 p.m. New York time.
– The Dow Jones Industrial Average rose 0.4%.
– The Nasdaq Composite Index advanced 0.5%.
– The Stoxx Europe 600 Index added 2%.
– The MSCI Asia Pacific Index increased 1.7%.
Currencies
– The Bloomberg Dollar Spot Index declined 0.1%.
– The euro fell 0.1% to $1.124.
– The Japanese yen weakened 0.1% to 107.53 per dollar.
Bonds
– The yield on 10-year Treasuries declined one basis point, to 0.67%.
– Germany’s 10-year yield sank three basis points, to -0.43%.
– Britain’s 10-year yield fell three basis points, to 0.186%.
Commodities
– The Bloomberg Commodity Index advanced 0.7%.
– West Texas Intermediate crude advanced 1.2%, to $40.29 a barrel.
The Stock Exchange of Thailand (SET) Index closed at 1,374.13 today (July 2), up 24.69 points or 1.83 per cent.
Total transactions amounted to Bt84.485 billion with an index high of 1,376.31 and a low of 1,353.50.
In the morning session, a stock analyst at Krungsri Securities expected the index to fluctuate between 1,340 and 1,360 due to mixed sentiments.
“The market was buoyed by advances in Pfizer and BioNTech’s Covid-19 vaccine research, the US private payroll in June adding 2.369 million jobs, and the crude oil price rising in response to US storage dropping by 7.2 million barrels,” the analyst said.
However, the index was still pressured by uncertainty following the second wave of Covid-19 cases in the US where daily cases are still rising, added the analyst.
“Also, the latest US Federal Reserve’s meeting pinpointed a risk that fiscal measures may not be enough to assist households, businesses, and local governments, which would drag down the index.”
The 10 stocks with the highest trade values today were STGT, STA, PTT, SCC, MINT, PTTEP, KBANK, CPF, BAM, and AOT.
As of 4.30pm, the crude oil price had risen by US$0.22 or 0.55 per cent to $40.04 per barrel, while gold was up by $3.20 or 0.18 per cent to $1,783.10 per ounce.
Other Asian indices were on the rise:
Japan’s Nikkei Index closed at 22,145.96, up 24.23 points, or 0.11 per cent.
China’s Shang Hai SE Composite Index closed at 3,090.57, up 64.59 points, or 2.13 per cent, while the Shenzhen SE Component Index closed at 12,269.49, up 156.52 points, or 1.29 per cent.
Hong Kong’s Hang Seng Index closed at 25,124.19, up 697.00 points, or 2.85 per cent.
South Korea’s KOSPI Index closed at 2,135.37, up 28.67 points, or 1.36 per cent.
Taiwan’s TAIEX Index closed at 11,805.14, up 101.72 points, or 0.87 per cent.
Jul 02. 2020Prime Minster Prayut Chan-o-cha has scheduled a meeting with the council of economic ministers on July 10 to discuss the country’s economic situation.
By THE NATION
Prime Minister Prayut Chan-o-cha has called a meeting with the council of economic ministers on July 10 to discuss the state of Thailand’s economy, the council’s secretary-general Kobsak Pootrakul said on Thursday (July 2).
The meeting will also seek measures to assist small and medium-sized enterprises from the impact of the Covid-19 outbreak, he added.
Meanwhile, Deputy Prime Minister Somkid Jatusripitak on Thursday assigned the Revenue Department and the Fiscal Policy Office to come up with measures to encourage community-level tourism and woo big spenders. The measures should be ready by mid this month, he added.
Somkid has also asked the central bank to widen the opportunity for businesses to take bank loans.
Meanwhile, Finance Minister Uttama Savanayana said his ministry was thinking about asking the Thai Credit Guarantee Corporation to develop a credit guarantee project to help small businesses. This measure is expected to be ready in two weeks.
The Joint Standing Committee on Commerce, Industry and Banking revised itsforecast for Thailand’s economic growth on Wednesday, bringing it down from between -3 and -5 per cent to between -5 and -8 per cent.
The Bank of Thailand has also recently said that the country’s economy this year will contract 8.1 per cent, worst ever, because the Covid-19 crisis has had a greater impact on both the Kingdom’s and global economy.
Thanavath Phonvichai, president of the University of the Thai Chamber of Commerce (UTCC), expects Thai gross domestic product (GDP) to show a 10-15 per cent contraction in the second quarter of this year, the period of lockdown when the economy felt the full impact of Covid-19.
He forecasts that the spending level of Thais will return to normal spending in a year’s time.
According to the university’s Economic and Business Forecasting survey, the consumer confidence index rose to 49.2 from the previous month’s score of 48.2. The rise coincided with phases 3 and 4 of lockdown easing.
The survey was conducted on 2,241 participants.
Positive factors affecting the results were the government’s relaxation of lockdown restrictions and launch of measures to ease burdens on consumers and businesses, Thanavath added.
Negative factors included public concern over the outbreak and weakened economy as well as the state of emergency extension.
People were also worried over the renewed trade war between the US and China, which threatens Thai exports.
United Nations Conference on Trade and Development (UNCTAD) estimates that for every US$1 million a country loses in tourism revenue its national income can drop by up to $3 million and have a dramatic effect on local employment.
Globally, the tourism sector could lose at least $1.2 trillion or 1.5 per cent of the world’s GDP now that travel has come to a virtual standstill for nearly four months due to the Covid-19 pandemic, an UNCTAD report published on Wednesday (July 1) said.
In the report, UNCTAD warned that the loss could rise to $2.2 trillion or 2.8 per cent of the global GDP if the halt on tourism lasts for eight months, and as much as $3.3 trillion or 4.2 per cent of global GDP if travel is halted for 12 months.
Tourism is the backbone of many countries and a lifeline for millions around the world, having more than tripled in value from $490 billion to $1.6 trillion in the last two decades, according to the UN World Tourism Organisation (UNWTO). However, the Covid-19 pandemic has brought travel to a halt, causing severe economic consequences globally.
Prevailing lockdown measures in some countries, travel restrictions, reduction in consumers’ disposable income and low confidence levels could significantly slow down the sector’s recovery, UNCTAD said.
“These numbers are a clear reminder of something we often seem to forget: the economic importance of the sector and its role as a lifeline for millions of people all around the world,” said Pamela Coke-Hamilton, UNCTAD’s director of international trade.
“For many countries, like small island developing states, a collapse in tourism means a collapse in their development prospects. This is not something we can afford.”
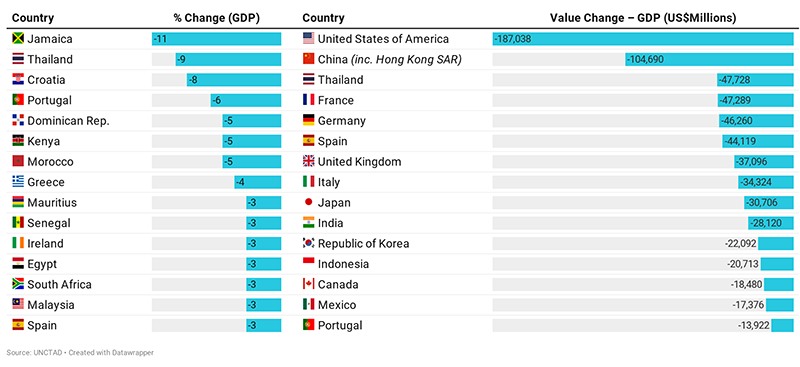
Developing countries could suffer the steepest GDP losses and Jamaica and Thailand stan out in this, losing 11 per cent and 9 per cent of GDP in the most optimistic scenario. Other tourism hotspots like Kenya, Egypt and Malaysia could lose over 3 per cent of their GDP.
Even rich countries are also feeling the pinch. Many popular European and American destinations, including France, Greece, Italy, Portugal, Spain and the United States may lose billions of dollars due to the dramatic drop in international tourism, UNCTAD forecasts.
Changes in GDP: 15 most affected countries, moderate scenario
Impact on other sectors, jobs and wages
Tourism accounts for a significant share of the global GDP and more than half of many countries’ national income. The coronavirus-induced losses in tourism are having a knock-on effect on other sectors that supply goods and services to tourists, such as food, beverages and entertainment.
Hence, UNCTAD estimates that for every $1 million lost in international tourism revenue, a country’s national income may decline by between $2 million and $3 million.
The massive drop in tourist arrivals has also left a growing number of people unemployed or with less income.
UNCTAD estimates show that in the worst-affected countries, such as Thailand, Jamaica and Croatia, employment for unskilled workers could drop at double-digit rates even in the most moderate scenario. Meanwhile, in terms of wages for skilled workers, the steepest drops were seen in Thailand (12 per cent), Jamaica (11 per cent) and Croatia (9 per cent) in the most optimistic scenario.
The effects could be worse for women who are expected to be disproportionately affected by layoffs in tourism due to Covid-19, the report said.
Women are more likely to run tourism businesses and make up about 54 per cent of workers in the accommodation and food services sectors. Since many women in the sector work informally in low-skilled jobs, they are unlikely to have unemployment benefits or other safety nets.
“This is why women are particularly hard hit in this crisis. And this is why policies that help protect the sector also protect the economic empowerment that many of these women have long fought for,” Coke-Hamilton said.
Recovery support needed
UNCTAD, meanwhile, is calling for stronger social protection in affected nations to prevent worse economic hardship for people and communities that depend on tourism.
It is urging governments to protect workers, and design subsidies to help workers move to new industries if their workplace is unlikely to recover.
Government should also help tourism companies facing the risk of bankruptcy, like hotels and airlines. One approach may be low-interest loans or grants, the report states.
UNCTAD is also calling on the international community to support access to funding for the hardest-hit countries.
The government is planning to boost Thailand’s international trade by signing bilateral free-trade pacts with three countries over the next two years.
Trade Negotiations Department director general Auramon Supthaweethum said the department was targeting the following free trade agreements (FTAs) as it prepared its 2022 budget.
1. The Thailand-Pakistan FTA, delayed by political developments in Pakistan after nine rounds of talks.
2. The Thailand-Turkey FTA, with the 7th round of talks due in Turkey this December.
3. The Thai-Sri Lanka FTA, delayed by elections in Sri Lanka after two rounds of talks.
Meanwhile, ongoing talks on the 15-member Regional Economic Partnership (RCEP) covering Asia-Pacific trade are set to conclude this month, with proposals put to the Cabinet in October ahead of the signing in Vietnam next year.
The Trade Negotiations Department will also prepare frameworks for talks on FTAs with the Eurasian Economic Union, the European Free Trade Association (EFTA), Bangladesh, the UK, Hong Kong, and separate Asean and Thailand pacts with the European Union. Budget will also be reserved to study whether Thailand should join the Comprehensive and Progressive Trans-pacific Partnership (CPTPP).

 Prime Minster Prayut Chan-o-cha has scheduled a meeting with the council of economic ministers on July 10 to discuss the country’s economic situation.
 Photo credit: freepik