High PE ratio, vaccine study set Thai bourse back a bit #ศาสตร์เกษตรดินปุ๋ย

#ศาสตร์เกษตรดินปุ๋ย : ขอบคุณแหล่งข้อมูล : หนังสือพิมพ์ The Nation.

https://www.nationthailand.com/business/30388173?utm_source=category&utm_medium=internal_referral

High PE ratio, vaccine study set Thai bourse back a bit

May 20. 2020
By The Nation

The Stock Exchange of Thailand (SET) Index opened at 1,308.75, down 1.20 points, or 0.09 per cent, on Wednesday (May 20) morning.

A Krungsri Securities stock analyst expected the index to remain at between 1,300 and 1,320.

He said that the market had gained positive sentiment from the second phase of lockdown easing and the rising crude oil price.

“Investors expect the demand for oil to recover after several countries eased their lockdown measures,” the stock analyst said.

However, the index would be under pressure due to news reports that a study of the new Moderna vaccine did not yield enough critical data to assess its success.

“In addition, investors would sell stocks as the index’s forward price-to-earnings ratio rose over 17 times, the highest among emerging countries,” the stock analyst said.

The analyst recommended investors buy these stocks:

● Energy stocks, such as PTT, PTTEP, TOP, PTTGC and SPRC, due to a rise in the price of crude oil.

● Retail stocks, such as CRC, CPN, HMPro, Global, Com7, and DoHome, due to the second phase of lockdown easing.

● Stocks whose second quarter performance would improve, such as CKP, Tasco and EPG.

SET rises nearly 2% over news of possible Covid-19 vaccine #ศาสตร์เกษตรดินปุ๋ย

#ศาสตร์เกษตรดินปุ๋ย : ขอบคุณแหล่งข้อมูล : หนังสือพิมพ์ The Nation.

https://www.nationthailand.com/business/30388134?utm_source=category&utm_medium=internal_referral

SET rises nearly 2% over news of possible Covid-19 vaccine

May 19. 2020
By The Nation

The Stock Exchange of Thailand (SET) Index closed at 1,309.95 today (May 19), rising by 23.42 points or 1.82 per cent.

Total transactions amounted to Bt78.863 billion with an index high of 1,318.01 and a low of 1,304.49.

A stock analyst from Krungsri Securities said he expects the index to rise between 1,300 and 1,310 points now that regional indices have rebounded over news about progress being made in the development of a Covid-19 vaccine.

“Moderna, a Massachusetts-based biotechnology company, announced that a human safety test revealed that the vaccine triggered virus-fighting antibodies,” the analyst said.

He added that the index also gained positive sentiment from the US Federal Reserve’s move to inject money into the market to mitigate the impact of Covid-19 and the rising price of crude oil.

“The price of crude oil rose over US$32 [Bt1,023.70] per barrel as demand for oil is expected to recover once several countries ease their lockdown measures and Saudi Arabia cuts oil production by 1 million barrels per day by June this year,” he said.

“However, we advise investors to beware of mass sell-offs as the index’s price-to-earnings ratio was around 17 times, the highest among emerging countries.”

The top 10 stocks with the highest trade values today were MINT, PTT, CPALL, BAM, KBANK, PTTEP, BBL, GPSC, PTTGC, and BDMS.

As of 4.30pm, crude oil price rose by $0.43 or 1.35 per cent to $32.25 per barrel, while gold rose by $3.80 or 0.22 per cent to $1,738.20 per ounce.

Though US and European indices were on the slide, Asian indices were on the rise:

Japan’s Nikkei Index closed at 20,433.45, up 299.72 points, or 1.49 per cent.

China’s Shanghai SE Composite Index closed at 2,898.58, up 23.16 points, or 0.81 per cent, while Shenzhen SE Component Index closed at 11,052.85, up 131.70 points, or 1.21 per cent.

Hong Kong’s Hang Seng Index closed at 24,388.13, up 453.36 points, or 1.89 per cent.

South Korea’s KOSPI Index closed at 1,980.61, up 43.50 points, or 2.25 per cent.

Taiwan’s TAIEX Index closed at 10,860.44, up 119.89 points, or 1.12 per cent.

Gold price drops amid hopes for Covid-19 vaccine #ศาสตร์เกษตรดินปุ๋ย

#ศาสตร์เกษตรดินปุ๋ย : ขอบคุณแหล่งข้อมูล : หนังสือพิมพ์ The Nation.

https://www.nationthailand.com/business/30388108?utm_source=category&utm_medium=internal_referral

Gold price drops amid hopes for Covid-19 vaccine

May 19. 2020
By The Nation

The price of gold dropped by Bt300 per baht weight in trade this morning (May 19), the Gold Traders Association reported.

As of 9.21am, the buying price of a gold bar was Bt26,100 per baht weight and selling price Bt26,300, while gold ornaments were priced at Bt25,635.56 and Bt26,800, respectively.

At Monday’s close, the buying price of a gold bar was Bt26,400 per baht weight and selling price Bt26,600, while gold ornaments were priced at Bt25,923.60 and Bt27,100, respectively.

The Gold Spot Index price this morning moved to around US$1,740 (Bt55,530) per ounce after the price dropped by $21.90 to $1,734.4 per ounce at close on Monday.

Investors were selling gold after the US Dow Jones Index rose more than 900 points in response to news reports that a Covid-19 vaccine had seen progress.

Meanwhile, the price of gold on the Hong Kong market dropped by HK$260 to $16,050 (Bt66,084) per tael.

Hopes for Covid-19 vaccine, US Fed move spur SET to rise over 1,300 points #ศาสตร์เกษตรดินปุ๋ย

#ศาสตร์เกษตรดินปุ๋ย : ขอบคุณแหล่งข้อมูล : หนังสือพิมพ์ The Nation.

https://www.nationthailand.com/business/30388104?utm_source=category&utm_medium=internal_referral

Hopes for Covid-19 vaccine, US Fed move spur SET to rise over 1,300 points

May 19. 2020
By The Nation

The Stock Exchange of Thailand (SET) Index opened at 1,308.96, up 22.43 points, or 1.74 per cent, this morning (May 19).

A Krungsri Securities stock analyst expected the index to rise to between 1,300 and 1,310 points after regional indices increased due to news reports about the progress of a Covid-19 vaccine.

“Moderna, the Massachusetts biotechnology company, announced after a human safety test result that the vaccine triggered blood levels of virus-fighting antibodies,” the analyst said.

He said the index also gained positive sentiment from the US Federal Reserve’s move to inject money into the market to mitigate the impact of Covid-19 and the rising crude oil price.

“The price of crude oil rose over US$32 [Bt1,023.70] per barrel as the demand for oil is expected to recover after several countries eased their lockdown measures and Saudi Arabia planned to cut oil production by 1 million barrels per day by June this year,” he said.

“However, we advised investors to beware of mass sell-offs in stocks as the index’s price-to-earnings ratio was around 17 times, the highest among emerging countries.”

The analyst recommended investors buy these stocks:

● Energy stocks, such as PTT, PTTEP, TOP, PTTGC and SPRC, due to a rise in the price of crude oil.

● Retail stocks, such as CRC, CPN, HMPro, Global, Com7, and DoHome, due to the second phase of lockdown easing.

● Stocks whose second quarter performance would increase, such as CKP, Tasco and EPG.

Masters of Norway’s $1 trillion fund now reaping rewards of a good choice made a half century ago #ศาสตร์เกษตรดินปุ๋ย

#ศาสตร์เกษตรดินปุ๋ย : ขอบคุณแหล่งข้อมูล : หนังสือพิมพ์ The Nation.

https://www.nationthailand.com/business/30388085?utm_source=category&utm_medium=internal_referral

Masters of Norway’s $1 trillion fund now reaping rewards of a good choice made a half century ago

May 19. 2020
A Norwegian national flag flies from the back of a boat in view of the the Aasta Hansteen gas platform near Stord, Norway, on March 8, 2018. MUST CREDIT: Bloomberg photo by Carina Johansen

A Norwegian national flag flies from the back of a boat in view of the the Aasta Hansteen gas platform near Stord, Norway, on March 8, 2018. MUST CREDIT: Bloomberg photo by Carina Johansen
By Syndication Washington Post, Bloomberg · Mikael Holter · BUSINESS 

In one of the world’s richest countries, the finance minister may soon need to break the spending record he just set.

For Jan Tore Sanner, 55, who’s been running Norway’s finances since January, that’s not really a problem thanks to a couple of choices his country made awhile back.

After Norway first discovered oil in 1969, a decision was made that would set it apart from other petro-states. Instead of splurging its newfound wealth on glitzy opulence to be savored by a small elite, Norway put the money in an oil fund for the people. Its wealth fund is now more than three times the size of Saudi Arabia’s, even though Norway’s oil production is dwarfed by the OPEC leader’s.

For Norway, the moment of truth has now arrived. Its $1 trillion wealth fund, the world’s biggest, has reached a historic turning point that lays bare the scale of the current crisis, and the remarkable prescience of Norway’s past leaders.

For the first time ever, Norway will draw more money from the fund than the vehicle generates in cash flow, due to the twin crises of covid-19 and a slump in oil prices. That requires an unprecedented asset sale to cover state spending. But the mechanism also means Norway won’t need to borrow an extra penny from bond markets.

Norway’s government estimates it will need to take $37 billion from the fund this year. The final figure may be even bigger. In an interview with Bloomberg, Sanner said, “We must be prepared to implement measures that will lead to higher oil money spending.”

“I don’t start the discussion with how much oil money we should spend,” he said. “I start the discussion with what measures are necessary and pertinent.”

Here’s what Bloomberg Economics’ Johanna Jeansson said in an analysis on Monday:

“Norway has a unique advantage — a $1 trillion wealth fund built from its vast oil reserves.” (…) “This assistance will limit lasting damage to the economy and quicken the recovery once the virus recedes.” (…) “Still, the risks to our outlook are to the downside.”

The Government Pension Fund Global, also dubbed the oil fund, was created in the 1990s to invest income from petroleum and gas in securities outside Norway. The idea was not only to build up savings, but also to protect the domestic economy from overheating.

To make sure future generations benefit from Norway’s fossil-fuel wealth long after the oil runs out, governments aren’t supposed to spend more than 3% of the fund’s value each year (which matches its expected real return).

During crises like the current one, politicians are allowed to bend the rules. So this year, Sanner is using a record amount of oil wealth, representing 4.2% of Norway’s fund. That’s about the same, in percent, as during the financial crisis in 2009 (but far more in absolute terms).

The worry is that persistent overspending might prevent the fund from becoming the perpetual welfare machine Norway intended it to be. But those overseeing the investment vehicle say even the current level of withdrawals isn’t an issue.

“It obviously is a positive feature of our society that we have this room to maneuver, unlike a number of other countries,” said Oystein Olsen, the governor of Norges Bank, which manages the fund. With such a “huge” piggy bank to draw on, there’s “no drama in fiscal policy,” he said in an interview.

Norway’s economy still faces a deep contraction in 2020 of around 4%. But Sanner says GDP may grow as much as 7% next year. The money he’s released from the wealth fund is helping pay for cash support for businesses, loan guarantees and more generous jobless benefits. That’s on top of free health care and education.

Norway’s fossil fuels laid the foundations for its extreme wealth. But as risks around oil grow, Norway wants to be less exposed. For now, its oil reliance might actually result in a longer economic downturn, and Sanner won’t say when spending will again be within the 3% rule.

“We don’t know how the oil price will develop or what the situation will be in the global economy,” he said.


‘Triple whammy’ of good news powers Dow more than 900 points #ศาสตร์เกษตรดินปุ๋ย

#ศาสตร์เกษตรดินปุ๋ย : ขอบคุณแหล่งข้อมูล : หนังสือพิมพ์ The Nation.

https://www.nationthailand.com/business/30388084?utm_source=category&utm_medium=internal_referral

‘Triple whammy’ of good news powers Dow more than 900 points

May 19. 2020
By The Washington Post · Taylor Telford · BUSINESS, US-GLOBAL-MARKETS 

A “triple whammy” of good news – led by promising results from a coronavirus vaccine trial – buoyed investors Monday, powering Wall Street to strong across-the-board gains.

The Dow Jones industrial average surged nearly 700 points at the opening bell, then kept going, after Moderna announced that an early-stage human trial for its coronavirus vaccine successfully produced covid-19 antibodies in participants. The biotech company said a large clinical trial to determine the treatment’s effectiveness would follow in July. Moderna’s shares soared more than 19%.

Investors also found comfort in comments made by Federal Reserve Chair Jerome Powell during a “60 Minutes” interview broadcast Sunday. He said the central bank is “not out of ammunition by a long shot” in its resources to support the economic recovery, even while he cautioned that it could stretch late into 2021. The comment come as most states have begun to ease restrictions on businesses and social activity after weeks of stay-home orders affecting about 315 million Americans.

At Monday’s close, the blue chip index’s lead swelled 911 points, or 3.9%, to 24,597.37. The broader Standard & Poor’s 500 index soared 3.2%, to 2,953.91, while the tech-heavy Nasdaq composite advanced 2.4%, to 9,234.83.

David Rosenberg, chief economist of Rosenberg Research, said investors were being rewarded with a “triple whammy of good news” after two weeks of market volatility marked by dramatic intraday swings as bad news piled up, interspersed by notes of optimism on the medical-research front, rising consumer sentiment and rumblings from business.

“For one, there is palpable relief that the majority of the states are reopening their economies, including 75% of California,” Rosenberg said in an email to The Washington Post. “Second, there is growing hope that a vaccine is coming our way sooner, rather than later. Lastly, Fed Chairman Jay Powell told investors over the weekend that the central bank’s checkbook remains wide open, strongly hinting that more monetary policy stimulus is on its way.”

The Trump administration’s senior economic adviser seconded that optimism in an interview Monday.

“I think that definitely you’re looking at a very strong third quarter, a very strong fourth quarter and probably a great next year,” Kevin Hassett said on CNBC’s “Squawk Box”

“I think the question is not really, ‘When does the recovery start?’ because, absent a second wave of the disease, it’s kind of already begun,” he said.

Most states have started relaxing stay-home public health orders. But infectious-disease experts caution that reopening too quickly could invite another wave of coronavirus cases. Infections in Alabama, North Dakota and Texas, three of the earliest states to reopen, have spiked in recent days, though that could be a byproduct of increased testing capacity.

Last week, fresh economic data revealed the pandemic’s mounting economic toll: The U.S. Labor Department on Thursday reported weekly jobless claims of 3 million, bringing the two-month total to more than 36 million unemployed people. April retail sales plummeted 16.4%, a drop that was worse than analysts had predicted as lockdowns kept consumers at home.

The darkening retail picture prompted some economists to issue even graver predictions for second-quarter gross domestic product, given that consumer spending accounts for 70% of U.S. economic growth. The economy shrank 4.8% in the first quarter – the biggest decline since the Great Recession – and some analysts believe the April to June period could see a contraction as high as 40%.

“The economic collapse has taken a dangerous turn where now it is consumer prices that are being pulled down into the abyss as consumers sitting at home have postponed their purchases,” Chris Rupkey, chief financial economist and MUFG Union Bank wrote in commentary. “The danger is that consumers will see that prices are falling and actually stop buying goods and services to wait for even cheaper prices and a better deal which will only serve to prolong the recession and reinforce the economy’s downward spiral into the unknown.”

That put investors in a selling frame of mind, with the Dow ending the week 2.6% lower. The S&P 500 fell 2.2%, and the Nasdaq shed 1.2% over the five-day run.

But Monday’s news led investors to leave safe havens for riskier ground. The yield on the 10-year U.S. Treasury note ticked upward, to 0.665% in early trading. Bond yields rise as prices drop.

Crude prices continue to recover, adding to the positive sentiment, as the easing of restrictions around the world also reined in fears of an oil glut. West Texas intermediate crude, the U.S. oil benchmark, jumped 7.8%, to $31.83 a barrel. Brent crude, the global oil benchmark, was trading up 7.7%, at $35 per barrel.

“The supply cuts of the last month combined with gradual reopening of various countries around the world has put a significant dent in the supply/demand imbalance and alleviated capacity concerns that led to last months panic,” Craig Erlam, an analyst with OANDA, wrote in commentary Monday.

Desalination plant to ease drought in industrial zones, EEC #ศาสตร์เกษตรดินปุ๋ย

#ศาสตร์เกษตรดินปุ๋ย : ขอบคุณแหล่งข้อมูล : หนังสือพิมพ์ The Nation.

https://www.nationthailand.com/business/30388069?utm_source=category&utm_medium=internal_referral

Desalination plant to ease drought in industrial zones, EEC

May 19. 2020
By THE NATION

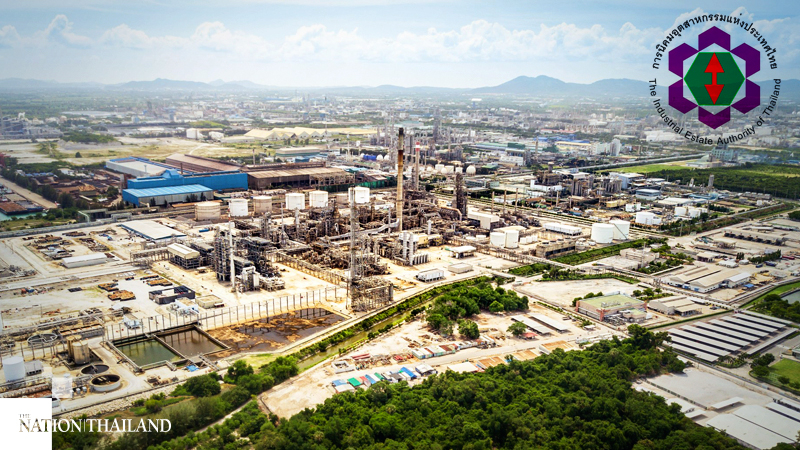
The Industrial Estate Authority of Thailand (IEAT) plans to set up a seawater desalination plant to produce fresh water for factories in all industrial zones, said IEAT governor Somchint Pilouk.

She added that the IEAT will set up a subsidiary to launch a joint venture with a private company for this project.

The aim is to ensure adequate supplies of water to factories regardless of weather conditions.

She said that some major businesses in the Map Ta Phut industrial zone already have their own desalination plants, but the IEAT plant will serve all factories in all industrial zones.

The plant will be able to process 300,000 cubic metres of water per day, expanded from the previous plan for 30,000 cubic metres daily.

The IEAT will talk with factories in the zones before setting its price for water.

Somchint added that though the price might be high, the water would only be used for short periods of drought. In normal periods, factories could continue to use regular sources, meaning their average long-term water costs would not surge.

Industrial zones in the Eastern Economic Corridor (EEC) are expected to use 264 million cubic metres of water in 2025, up from the estimated 239 cubic metres this year.

She said that Deputy Prime Minister Prawit Wongsuwan has asked related state agencies to tackle the drought in the EEC and asked the IEAT to seek new supplies for EEC factories without using water from the farm sector.

Harvard’s Reinhart and Rogoff say this time really is different #ศาสตร์เกษตรดินปุ๋ย

#ศาสตร์เกษตรดินปุ๋ย : ขอบคุณแหล่งข้อมูล : หนังสือพิมพ์ The Nation.

https://www.nationthailand.com/business/30388078?utm_source=category&utm_medium=internal_referral

Harvard’s Reinhart and Rogoff say this time really is different

May 18. 2020
A 2010 file photo of Carmen Reinhart, today a professor at the Harvard Kennedy School, at the Federal Reserve Bank of Kansas City annual symposium near Jackson Hole, Wyo. MUST CREDIT: Bloomberg photo by Andrew Harrer.

A 2010 file photo of Carmen Reinhart, today a professor at the Harvard Kennedy School, at the Federal Reserve Bank of Kansas City annual symposium near Jackson Hole, Wyo. MUST CREDIT: Bloomberg photo by Andrew Harrer.
By Syndication The Washington Post, Bloomberg · Simon Kennedy

When Carmen Reinhart and Kenneth Rogoff published their heavyweight history of financial crises in late 2009, the title was ironic.

“This Time Is Different: Eight Centuries of Financial Folly” reminded readers that the catastrophic 2008-09 credit crisis was far from unique. The authors became the go-to experts on the history of government defaults, recessions, bank runs, currency sell-offs, and inflationary spikes. Everything seemed to be part of a predictable pattern.

Kenneth Rogoff, professor of economics at Harvard University, at the World Economic Forum in Davos, Switzerland, on Jan. 23, 2018. MUST CREDIT: Bloomberg photo by Jason Alden.

Kenneth Rogoff, professor of economics at Harvard University, at the World Economic Forum in Davos, Switzerland, on Jan. 23, 2018. MUST CREDIT: Bloomberg photo by Jason Alden.

And yet a little more than a decade later, we’re experiencing what appears to be a one-of-a-kind crisis. The covid-19 pandemic has catapulted the world into its deepest recession since the Great Depression, provoking an unprecedented fiscal and monetary response. To figure out what might be next, Bloomberg Markets spoke to Reinhart, a former deputy director at the International Monetary Fund who’s now a professor at the Harvard Kennedy School, and Rogoff, a former IMF chief economist who’s now a professor at Harvard. It turns out this time really is different.

BLOOMBERG MARKETS: How are you faring during the lockdown?

CARMEN REINHART: My husband and I are among the lucky ones because we can work from home. We came to Florida, where we’ve had a house for a decade. Our son lives in this area. Vincent’s brother lives in this area. So we wanted to be close to family. It’s a very busy period even though you’re always at home.

KENNETH ROGOFF: I’m with my wife and 21-year-old daughter in our house in Cambridge, quarantining, so to speak. It’s been a very intense period partly because I was teaching a lot. And there was the shift to Zoom, which created more work because you’re trying to prepare differently and do your lectures differently. It’s obviously a surreal experience overall.

BM: I will start with the clichéd question. Is this time different?

CR: Yes. Obviously there are a lot of references to the influenza pandemic of 1918, which, of course, was the deadliest with estimated worldwide deaths around 50 million-maybe, by some estimates, as many as 100 million. So pandemics are not new. But the policy response to pandemics that we’re seeing is definitely new. If you look at the year 1918, when deaths in the U.S. during the Spanish influenza pandemic peaked, that’s 675,000. Real GDP that year grew 9%. So the dominant economic model at the time was war production. You really can’t use that experience as any template for this. That’s one difference.

It’s certainly different from prior pandemics in terms of the economy, the policy response, the shutdown. The other thing that I like to highlight that is very different is how sudden this has been. If you look at U.S. unemployment claims in six weeks, we’ve had [job losses that] took 60 weeks in terms of the run-up. If you look at capital flows to emerging markets, the same story. The reversal in capital flows in the four weeks ending in March matched the decline during the [2008-09] global financial crisis, which took a year. So the abruptness and the widespread shutdowns we had not seen before.

KR: Certainly the global nature of it is different and this highlights the speed. We have the first global recession crisis really since the Great Depression. In 2008 it was the rich countries and not the emerging markets. They [the emerging markets] had a “good” crisis in 2008, but they’re not going to this time, regardless of how the virus hits them.

The policy response is also different. Think about China. Can you imagine if this had hit 50 years ago? Can you imagine the Chinese state having the capacity to shut down Hubei province? To feed nearly 60 million people, give them food and water and concentrate medical attention? So there is a policy option that we have and I think most countries have. It’s the choice that had to be taken to try to protect ourselves. Obviously, this has been done to differing degrees of effectiveness in different countries, with Asia reacting much quicker and with much better near-term outcomes than Europe and the U.S.

BM: How do you regard the economic policy response?

KR: It’s a little bit as if you were in a war and saying, “I’m not going to grade how you’re doing on the battlefield. I’m just going to grade how you’re hiring extra workers at home.” Obviously how you’re doing on the battlefield is driving everything.

The economic policy response has been massive and absolutely necessary. You can quibble between the European style of trying to preserve firms and workers in their current jobs and the U.S. version, which is to try to address it as a natural catastrophe and try to subsidize people but allow higher unemployment. They’re actually not that different. If this thing persists, a lot of those European firms will end up having to let their workers go when the crisis passes. Some of the U.S. firms will end up rehiring their workers. But certainly the aggressive crisis response reflects lessons learned in 2008.

BM: Does that explain the stock market surge, which seems at odds with the state of the economy?

CR: How much of the resilience, if not ebullience, in the market is policy driven? I think a lot of it. Let’s take monetary policy before the pandemic. U.S. unemployment was at its lowest level since the 1960s. By most metrics the U.S. was at or near full employment. It’s very possible that the path was toward rising interest rates. Clearly that has been completely replaced by a view that rates are zero now and that they’re going to stay low for a very long, long, indeterminate period of time, with a lot of liquidity support from the Federal Reserve. So that’s a big game changer, discounting futures.

Let me just point out another issue in terms of the policy response. The Fed has established a lot of facilities that are now providing support not only to corporates, but to the fallen angels, the riskier corporates that certainly were not envisioned at the outset of the pandemic. What this does mean is that the market is really counting on a lot of rescues. The blanket coverage by the Fed is broad, and that is driving the market. And expectations are that we’re going to have this nice V-shaped recovery and life is going to return to normal as we knew it before the pandemic. And my own view is that neither of those are likely to be true. The recovery is unlikely to be V-shaped, and we’re unlikely to return to the pre-pandemic world. Although I do think that that’s part of the reason why we see this incongruence between the economic numbers and what the market is doing.

KR: Of course, the “Fed lower forever” is part of it. I also feel the markets have a very sanguine view of the virus and what’s going to happen and how quickly we can return to normal or maybe how quickly we will choose to return to whatever normal is. It seems very uncertain to me. I don’t know how we’re coming back to 2010 levels [in the economy] in any near term. The true fall in GDP, economic historians will debate for years. It’s probably much larger than the measured fall. It’s not just the people not working. What’s the efficiency of the people who are working? The monetary response has been done hand in hand with the Treasury. The market is banking on this V-shaped recovery. But a lot of the firms aren’t coming back. I think we’re going to see a lot of work for bankruptcy lawyers going across a lot of industries.

BM: So what does the economic recovery look like?

CR: There is talk on whether it’s going to be a W-shape if there’s a second wave and so on. That’s a very real possibility given past pandemics and if there’s no vaccine. One thing that’s clear is the numbers are going to look spectacularly great in some months simply because you’re coming out from a base that was pretty devastated. That doesn’t imply that per capita incomes are going to go back in V-shape to what they were before.

The shock has disrupted supply chains globally and trade big-time. The World Trade Organization tells you trade can decline anywhere between 13% and 32%. I don’t think you just break and re-create supply chains at the drop of a hat. There are a lot of geographic changes that are being necessitated because, if the economic downturn has been synchronous, the disease itself hasn’t been synchronous.

Another reason I think the V-shape story is dubious is that we’re all living in economies that have a hugely important service component. How do we know which retailers are going to come back? Which restaurants are going to come back? Cinemas? When this crisis began to morph from a medical problem into a financial crisis, then it was clear we were going to have more hysteresis, longer-lived effects.

KR: In our book, Carmen and I use the definition of recovery as going back to the same income as the beginning. That, by the way, is really not the Wall Street definition of recovery, where recovery is going back to where the trend was. So we use a much more modest version of recovery. And still, with postwar financial crises before 2008-09, the average was four years, and for the Great Depression, 10 years. And there are many ways this feels more like the Great Depression.

And you want to talk about a negative productivity shock, too. The biggest positive productivity shock we’ve had over the last 40 years has been globalization together with technology. And I think if you take away the globalization, you probably take away some of the technology. So that affects not just trade, but movements and people. And then there are the socio-political ramifications. I liken the incident we’re in to “The Wizard of Oz,” where Dorothy got sucked up in the tornado with her house, and it’s spinning around, and you don’t know where it will come down. That’s where our social, political, economic system is at the moment. There’s a lot of uncertainty, and it’s probably not in the pro-growth direction.

Also you probably need a debt moratorium that’s fairly widespread for emerging markets and developing economies. As an analogy, the IMF or Chapter 11 bankruptcy is very good at dealing with a couple of countries or a couple of firms at a time. But just as the hospitals can’t handle all the covid-19 patients showing up in the same week, neither can our bankruptcy system and neither can the international financial institutions.

So there are going to be phenomenal frictions coming out of this wave of bankruptcies, defaults. It’s probably going to be, at best, a U-shaped recovery. And I don’t know how long it’s going to take us to get back to the 2019 per capita GDP. I would say, looking at it now, five years would seem like a good outcome out of this.

BM: I’d like to focus on the debt issue. The Group of 20 has already agreed to freeze bilateral government loan repayments for low-income nations until the end of 2020. How else do we deal with what developing and emerging economies owe?

CR: The problem in emerging markets goes beyond the poorest countries. For many emerging markets, we’ve also had a massive, massive oil shock. Nigeria, Ecuador, Colombia, Mexico-they’ve all been downgraded. So the hit to emerging markets is just very broad. Nigeria is in terrible shape. South Africa is in terrible shape. Turkey is in terrible shape. Ecuador already is in default status, as well as Argentina. These are big emerging markets. It’s going to be enormously costly.

For the G-20 initiative, I indeed hope it is the G-20 and not just the G-19. China needs to be on board with debt relief. That’s a big issue. The largest official creditor by far is China. If China is not fully on board on granting debt relief, then the initiative is going to offer little or no relief. If the savings are just going to be used to repay debts to China, well, that would be a tragedy.

We’ve not mentioned Italy, and that brings us to the euro zone. This is very, very destructive within the euro zone. If it drags on, the forces that are pulling the euro zone apart are going to grow stronger and stronger.

BM: What is the appetite at the IMF for coming to the rescue?

KR: The IMF at this point is all-in on trying to find a debt moratorium, recognizing there’s going to be restructuring in a lot of places. But I don’t think the U.S. is by any means all-in, and a lot of the contracts of the private sector are governed under U.S. law. And if the U.S. government is not in, if China’s not in, it’s not really enough. But it’s far easier to go the route of the G-20. If the G-20 says it’s in the global interest that debt moratoria be widely respected by all creditors for the next year, then that carries a lot of force, even in U.S. courts. But if they don’t say that, and every country’s left on its own to work something out, I think we get back to my covid-19 hospital analogy where the system just gets overwhelmed.

BM: What about the debts in the major economies, given they have been run up so aggressively?

KR: It’s not a free lunch, but there was no choice. This is like war. There is no debate that they should be doing all they can to try to maintain political and social cohesion, to maintain economies. But what lies at the other end? I go back to my “Wizard of Oz” analogy. The financial markets think there’s no chance interest rates will go up. There is no chance inflation will go up. If they’re right, and if another shoe doesn’t drop, it’ll be fine. But we could have costs from this. We’re talking about economies shrinking by 25% to 30%. And those [declines] are just staggering compared to the debt burden costs, whatever they are. So certainly we would strongly endorse doing what governments are doing. But selling it as a free lunch, that’s stupefyingly naive.

CR: I actually wanted to go back to the Italy issue. If you look back to 2008-09, nearly everybody had a banking crisis. But a couple of years later, the focus had moved from the banking problem to the debt problem. And it was the peripheral Europe debt problem with Portugal, Ireland, Iceland-most notoriously Greece-having the largest, by a huge margin, IMF programs in history. I would point out that Greece, Ireland, and Portugal combined are a little over a third of Italian GDP. And if there’s a shakeout that involves concerns about Italy’s growth, then we could have a transition again from the focus on the covid-19 crisis this time to a debt crisis. But Italy, as I said, is on a different scale than the peripheral countries that got into the biggest trouble in the last crisis. It potentially also envelops Spain. So I think that if you were to ask me about an advanced economy debt issue, I think that is where it is most at the forefront.

KR: We argued at the time that the right recipe was to involve writedowns of the southern European debts. And I think that would have been cheap money in terms of restoring growth in the euro zone and would have [been] paid back. And we may be at that same juncture in another couple of years where you’re looking at just staggering austerity in Spain and Italy on top of a period of staggering hardship. Advanced countries have done this all the time-finding some sort of debt restructuring or writedown to give them fiscal space again, to support growth again. If the euro zone doesn’t find a way to deal with this, maybe eurobonds might be in the picture to try to indirectly provide support. Again, we’re going to see huge forces pulling apart the euro zone.

BM: What about China, which also has leverage challenges?

CR: Chinese growth has always been very outward-looking, very propelled by export-led growth. You’ve also had much of its double-digit growth come from incredible fixed investment. So I think the settling point for Chinese growth is going to be well below 6%. I’m not saying they’re not going to have a rebound after the more than 20% crash at the beginning of this year. But I’m saying that then your settling point is going to be lower than 6%. And part of the story is debt. It’s hard to say in China what is public and what is private, but corporates in China levered up significantly, expecting that they were going to continue to grow at double digits forever. That hasn’t materialized. There’s overcapacity in a lot of industries.

China came into this with inflation running over 5% because of the huge spike in pork prices. So I think initially that the PBOC [People’s Bank of China] has been somewhat constrained initially in doing their usual big credit stimulus by uncertainty over their inflation. I think that’s changing because of the collapse in oil price. So I do think we are going to see more stimulus from China.

KR: There will be a pretty sustained growth slowdown in China. We were on track for that anyway. But who can they export to? The rest of the world is going to be in recession. I think if they can average 1% growth the next two, three years, then that will look good. That’s not a bad prediction for China. And let’s remember, their population dynamic is completely changing. So 3% growth in that, with that Europeanizing of their population dynamics, would not be bad at all. But there’s a big-picture question about their huge centralization, which is clearly an advantage in dealing with the national crisis but maybe doesn’t provide the flexibility over the long term to get the dynamism that at least you’ve got in the U.S. economy.

BM: How does central banking change worldwide? Do we see that blurring of lines with fiscal policy?

KR: It’s fiscal policy that they’re doing in this emergency situation. You can’t imagine trying to get these same subsidies passed through the Senate and the House in real time. So central banks all over the world are using the fiscal side of their balance sheet. A lot of people don’t properly understand that governments own the central banks. And when the central bank uses its balance sheet, it’s acting as an agent on behalf of the government, whether it’s doing maturity transformation, which is what pure quantitative easing is, when it buys long-term debt, [or] it’s doing subsidies to the private sector by buying mortgages, by intervening in corporate debt, by intervening in municipals.

Ultimately I hope we don’t see a big change in central banks, but we’re probably going to need an expansion in finance ministries to take on and regularize and legitimize some of these responsibilities. Lastly I think we’re not in a position to use deeply negative interest rates because the preparation hasn’t been done. And you have to deal with cash hoarding. That’s a shame because I think that would have been a valuable instrument, and would have been helpful for some municipals and corporates, and would have reduced the number of patients going into bankruptcy court. Monetary policy is essentially castrated by the zero bound.

CR: Central banks were the arm of financing during two world wars, without question. I think you would have been laughed at if you really brought up the issue of central bank independence in the context of either world war. You really can’t separate the fiscal story and the debt story from the monetary story in extreme periods. Central banks began to do fiscal policy not just this time around, but they began to do fiscal policy in the 2008-09 crisis. We really can’t look independently at central banks without also looking at the balance sheet, not just of the government, but the balance sheet of the private sector, which has a lot of contingent liabilities.

On the issue of negative interest rates, I do not share Ken’s views on that particular matter. When you have, as we do today, very fragmented markets, markets that became totally illiquid, I think the way I would deal with that would not be through making rates more negative, but by an approach closer to the one taken by the Fed, which is through a variety of facilities that provide directed credit. Sustained negative interest rates in Europe have led to a lot of bank disintermediation. And often bank disintermediation means that you end up with the less regulated, less desirable financial institutions.

BM: There is some question over the future path of inflation. Do you see an inflationary surge at some point?

KR: We don’t know where we will come out. So the probability is, for the foreseeable future, we’ll have deflation. But at the end of this, I think we’re going to have experienced an extremely negative productivity shock with deglobalization. In terms of growth and productivity, they will be lasting negative shocks, and demand may come back. And then you have the many forces that have led to very low inflation maybe going into reverse, either because of deglobalization or because workers will strengthen their rights. The market sees essentially zero chance of ever having inflation again. And I think that’s very wrong.

BM: And what scars are left on economies once the pandemic passes?

CR: Some of the scars are on supply chains. I don’t think we’ll return to their precrisis normal. We’re going to see a lot of risk aversion. We’ll be more inward-looking, self-sufficient in medical supplies, self-sufficient in food. If you look at some of the legacies of the big crises, those have all seen fixed investment ratchet down and often stay down.

Kennedy is executive editor for Bloomberg Economics in London.

Flying blind through crisis, many Gulf economies still an enigma #ศาสตร์เกษตรดินปุ๋ย

#ศาสตร์เกษตรดินปุ๋ย : ขอบคุณแหล่งข้อมูล : หนังสือพิมพ์ The Nation.

https://www.nationthailand.com/business/30388076?utm_source=category&utm_medium=internal_referral

Flying blind through crisis, many Gulf economies still an enigma

May 18. 2020
An empty highway leads past the Burj Khalifa skyscraper (center) and other office buildings on the city skyline during the coronavirus lockdown in Dubai, United Arab Emirates, on April 24, 2020. MUST CREDIT: Bloomberg photo by Christopher Pike.

An empty highway leads past the Burj Khalifa skyscraper (center) and other office buildings on the city skyline during the coronavirus lockdown in Dubai, United Arab Emirates, on April 24, 2020. MUST CREDIT: Bloomberg photo by Christopher Pike.
By Syndication Washington Post, Bloomberg · Abeer Abu Omar · BUSINESS, WORLD, MIDDLE-EAST 

Statistics are a poor guide to the crisis raging across Gulf Arab economies.

The region’s second-biggest economy, the United Arab Emirates, has yet to disclose how it performed in the second quarter — of last year. The statistics authority separately released an assessment of the U.A.E.’s full-year gross domestic product growth for 2019, without providing a quarterly breakdown.

Qatar published national accounts for the fourth quarter only in late April. Although faster than its neighbors, Saudi Arabia is scheduled to report the first quarter’s GDP on the last day of June, some two months behind most of its counterparts in the Group of 20.

The delays are increasingly a source of frustration for investors, economists and rating companies — especially at a time when the damage from slumping oil prices and the coronavirus pandemic is reshaping the outlook so fast that analysts can barely keep up. Statistics in some of the countries can be equally scarce on everything from budgets to wealth fund holdings.

Qatar’s government communications office didn’t provide a comment and the Federal Competitiveness and Statistics Authority of the U.A.E. didn’t respond to questions. Saudi Arabia’s General Authority for Statistics “has launched an internal project to have early GDP estimates by the end of the year,” said its president, Konrad Pesendorfer.

With visibility so low, decisions can be hard to make, according to Ali Al-Salim, co-founder of Arkan Partners, a consulting company for alternative investments including hedge funds and private equity.

In the case of Abu Dhabi, the richest of the U.A.E.’s seven sheikhdoms, Moody’s Investors Service last week said its “main credit challenges lie in a lack of institutional data transparency.”

The World Bank has even argued that a lack of reliable data might have been costly enough to contribute to slow economic growth before this year’s shocks. The Middle East and North Africa is the only region of the world that has seen an absolute decline in their index of data transparency between 2005 and 2018, according to a report in April.

As the crisis gained momentum last month, the U.A.E. tried to compensate for any shortage of information by asking manufacturers to take part in a survey to gauge the impact of the virus outbreak. The Finance Ministry also launched an online platform that it says is “dedicated to transparency in the U.A.E.,” allowing the public to access studies, reports and statistics.

But given the lag in GDP figures and without enough high-frequency indicators to track the recent disruptions, consultancy Oxford Economics has looked for workaround solutions by using “non-traditional” sources of information, from Google location data to hotel occupancy statistics.

“Data limitations make it difficult to track the economic impact of the coronavirus pandemic” in the Gulf, said Scott Livermore, chief economist in the Middle East at Oxford Economics. “The challenges are particularly acute given the significant lags in releasing national accounts data.”

Gold climbs to 7-year high after fed’s stocks, growth warnings #ศาสตร์เกษตรดินปุ๋ย

#ศาสตร์เกษตรดินปุ๋ย : ขอบคุณแหล่งข้อมูล : หนังสือพิมพ์ The Nation.

https://www.nationthailand.com/business/30388074?utm_source=category&utm_medium=internal_referral

Gold climbs to 7-year high after fed’s stocks, growth warnings

May 18. 2020
Jerome Powell, chairman of the Federal Reserve, in Washington on March 3, 2020. MUST CREDIT: Bloomberg photo by Andrew Harrer.

Jerome Powell, chairman of the Federal Reserve, in Washington on March 3, 2020. MUST CREDIT: Bloomberg photo by Andrew Harrer.
By Syndication Washington Post, Bloomberg · Ranjeetha Pakiam · BUSINESS, US-GLOBAL-MARKETS

Gold rose to the highest in more than seven years after the Federal Reserve said stocks and asset prices could suffer a significant hit from coronavirus, and warned the process of economic recovery may stretch through until the end of next year. Palladium surged more than $100 in 20 minutes.

Commercial real estate could be among the hardest-hit industries should the health crisis deepen, the U.S. central bank said in its twice-yearly financial stability report Friday. Separately, Chairman Jerome Powell said in an interview with CBS that a full recovery of the U.S. economy could drag through 2021 and depends on the delivery of a vaccine.

Bullion has surged 16% this year as the spread of the virus curbed economic growth, roiled markets, and prompted vast amounts of stimulus to be unleashed by governments and central banks. Further bolstering the case for the metal has been recent speculation U.S. interest rates could go negative, while holdings in gold-backed exchange-traded funds are at a record.

Spot gold climbed as much as 1.2% to $1,764.73 an ounce, the highest since October 2012, and traded at $1,763.58 at 6:44 a.m. in London.

“Financial markets can best be described as factoring in the best-case scenario, with economic stimulus leading to a rapid recovery,” said Gavin Wendt, senior resource analyst at MineLife. “The reality is likely to be quite different and there is the prospect that no vaccine will be developed. The recovery is probably set to be more problematic than the optimists think, with gold set to benefit from the enormous boost to money supply that is going to ensue.”

Monday’s gain in gold comes after data released Friday underscored how hard virus-related shutdowns have hit the world’s largest economy. U.S. retail sales and factory output registered the steepest declines on record in April.

Powell is due to appear along with Treasury Secretary Steven Mnuchin before the Senate Banking Committee on Tuesday. Fed officials including Powell have consistently batted the idea of negative interest rates away, and he did so again on Sunday, saying that it’s probably not an appropriate or useful policy for the U.S., according to a transcript of the full interview.

In other precious metals, silver climbed as much as 4% and platinum advanced 3.5%.

Palladium jumped as much as 8.3%, the most since March 25, before trading 4.3% higher at $1,962.41. The surge comes even after Norilsk Nickel said last week demand may drop 16% this year, the most in almost two decades. The metal, alongside platinum, has found some recent support from operational curbs in South Africa.

“Palladium is seeing strength on supply concerns due to the virus-related reduction in mining activities,” said Gnanasekar Thiagarajan, director at Commtrendz Risk Management Services. “During May-June output is expected to be lower.”