The Stock Exchange of Thailand (SET) Index fell by 0.49 points, or 0.04 per cent, to 1,274.34 in the morning session on Friday.
An analyst at Krungsri Securities expected the index to fluctuate between 1,265 and 1,285 despite the rise in oil price and ongoing progress in the US economic stimulus measures.
“Investors should beware of mass sell-offs of shares to mitigate risks from the political rally next week, as it would pressure the index,” he said.
As an investment strategy, he recommended that investors buy:
▪︎ PTTEP, TOP and PTTGC that will benefit from rising oil price.
▪︎ CRC, HMPRO, JMART, COM7, KTC, CENTEL and MINT that will benefit from the government’s “Shop Dee Mee Kuen” (Shop and Payback) scheme.
▪︎ TU, PLANB, STGT, COM7, ASIAN and CBG whose third-quarter performance is expected to grow.
The SET Index closed at 1,274 on Thursday, up 11.12 points or 0.88 per cent, while transactions amounted to Bt56 billion in response to the news of US President Donald Trump’s U-turn on stimulus measures and Thailand’s Centre for Economic Situation Administration approving the “Shop Dee Mee Kuen” (Shop and Payback) scheme to stimulate consumer spending.
The price of gold rose by Bt200 per baht weight in morning trade on Friday, the Gold Traders Association reported.
As of 9.21am, the buying price of a gold bar was Bt28,000 per baht weight and selling price Bt28,100, while gold ornaments were priced at Bt27,500.24 and Bt28,600, respectively.
At close on Thursday, the buying price of a gold bar was Bt27,800 per baht weight and selling price Bt27,900, while gold ornaments were Bt27,303.16 and Bt28,400, respectively.
Spot gold price moved to US$1,905 (Bt59,278) per ounce on Friday morning after the price rose by $43 to $1,895.1 per ounce at Thursday’s close in response to ongoing progress of US economic stimulus measures after US President Donald Trump expressed confidence that the White House and the Democrats could reach an agreement to roll out these measures.
Hong Kong gold price rose by HK$70, opening at $17,550 (Bt70,469) per tael this morning, the Chinese Gold and Silver Exchange Society reported.
Lack of middlemen helps property marketplace offer attractive discounts
Oct 09. 2020
By THE NATION
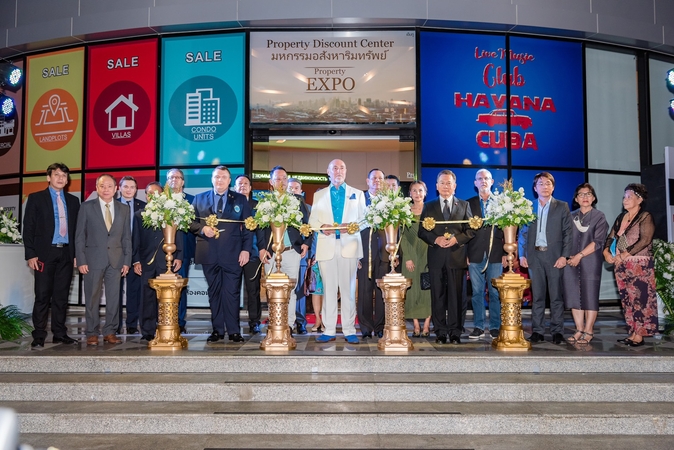
Thailand’s first offline and online property marketplace, Property Discount Center (propertydiscountcenter.com), was launched on October 1 in Phuket.
This site links buyers and sellers directly without middlemen.
“We are a property marketplace, not an agency or broker. You can place an ad for your condo, villa, business or even boat with us and we can share the info with buyers from across the world. Our advertising network covers Hong Kong, Singapore, Macau, China, Russia and Europe,” said Stuart Coakley, director of the business said.
“We have over 10 years of experience successfully facilitating sales of property online. Foreign buyers do not have to come to Thailand, all the work can be done without them being present. This is important at a time when investors want to invest, but can’t visit due to Covid-19 restrictions.”
Normally developers and property owners spend 20 to 35 per cent of their selling price on advertisement, marketing, commissions, rental of boots, salaries and discounts sought by buyers, he said.
“But we use another format. Instead of spending on all this, we offer buyers an attractive discount so both parties win,” he said.
He added that during these challenging times, it’s important to find new ways to attract international investors and increase the sale of real estate in Thailand.
Huawei unveils ‘cloud+AI+IoT synergy’ trend, to revolutionise Thai smart business
Oct 08. 2020Abel Deng, chief executive officer of Huawei Technologies (Thailand) Co Ltd
By The Nation
Huawei has launched a synergy-based ecosystem between the cloud, artificial intelligence (AI) and Internet of Things (IoT) innovations to help reduce costs, improve efficiency and boost service quality of Thai businesses.
Such ecosystems will pave the way for the new fully ‘smart’ era for every industry nationwide, the company said, adding, Huawei believes that all businesses and industries will adapt to using cloud services within five years. Cloud service providers will, therefore, need to focus their priority on the issues of data security, communication speed, and the cloud ecosystem.
Abel Deng, chief executive officer of Huawei Technologies (Thailand) Co Ltd, illustrates how the cloud, AI and IoT technologies can be integrated and utilised by the Thai business sector, saying: “The joint efforts between the public and private sector to drive technological development is the key reason why Thailand has become one of the leaders in technological innovation adoption in Asean.”
“Such collaboration is seen in policies like the Thailand 4.0 strategy from the Thai government, while the private sector has consistently pushed the boundaries through the construction of innovative communication networks, as well as new service offerings for Thai users,” Abel.said.
“Thailand is also a key market for Huawei, where we offer all four business categories of our products and services: Carrier, enterprise, consumers and cloud and AI. With such a comprehensive product portfolio, Huawei will be able to deliver a complete end-to-end ecosystem, covering both hardware and software, while helping Thai industry further develop at an accelerated pace towards ‘Smart Industry’.”
He adds that cloud technology is the backbone infrastructure that enables other advanced technologies, such as AI, IoT, VR/AR, and 5G, helping foster future-oriented innovative networks.
“The cloud functions like a runway, powering efficient data processing to support these technologies. Therefore, Huawei has given precedence to our cloud development, which includes the establishment of the first cloud data centre in Thailand, operating specifically for the Thai market. This commitment can also be seen in our ‘Cloud First’ strategy for ecosystem development in Thailand, so we can deliver the best of experiences to all Thai users,” Abel adds.
Piyatida Itiravivongs, president of Cloud Business Department, Huawei Technologies (Thailand) Co Ltd, states: “The synergic integration of the cloud, AI, and IoT technologies can help support the development of the ‘Smart City’ at a national level, through solutions such as smart city management, traffic management or AI drone inspection.
“As for the private sector, the synergy of these technologies within organisations will help revamp operational processes in multiple areas. Data from various sources will be collected through network systems and Internet of Things applications, then sent to the cloud for processing with the help of AI. As such, Thai enterprises that can successfully adapt these technologies will be able to reduce costs, accelerate back-end operational efficiency and deliver a better customer experience.”
Piyatida says the cloud, AI, and IoT will automate operational procedures within organisations, from basic tasks such as office lighting control and movement of people on premises, to improved operations or customer insights, enabling businesses to offer higher quality products and services and delivering a better customer experience, thereby increasing the number of returning customers and generating higher profits for their company.
Piyatida also adds that, according to the Huawei GIV (Global Industry Vision) 2025 Report, it is predicted that 100 per cent of global business organisations will utilise cloud technology and 85 per cent of all enterprise applications will be cloud-based by 2025.
In addition, 86 per cent of all enterprises will adopt AI technology, and enterprise data utilisation will increase to 80 per cent. In Thailand, cloud services will focus on the public cloud due to its convenience and higher return on investment, aligned with the current economic recovery. Furthermore, the public cloud can increase corporate flexibility, helping open more investment opportunities for business expansion. Organisations who require increased information security standards have the option to utilise the hybrid and public cloud with data centres located in Thailand.
Surasak Wanichwatphibun, chief technology officer of the Cloud Business Department, Huawei Technologies (Thailand) Co Ltd, says: “Huawei Cloud is the first and currently the only global cloud service provider to have two data centres in Thailand, dedicated to providing cloud services. The local centres will be able to offer the lowest latency, data security protection under the Thai laws, and 24/7 response from customer support and the R&D expertise team located at Huawei’s headquarters.” Huawei is providing cloud services to customers in various industries in Thailand from retail to banking and manufacturing, as well as international organisations such as logistics company J&T Express, entertainment company Mango TV, and media agency Xinhua News Agency.
“Cloud service providers must place priority on their clients’ data security, and having cloud data centres located in Thailand will help maintain the highest data security since the particular cloud service is under Thai law. Moreover, the R&D and customer support service teams will be able to quickly react to solve any demands or problems. “Another advantage of the data centre being located in Thailand is the higher speed of data transactions, with latency under 10 milliseconds, 5-10 times better than other international cloud service providers, aligned and fully compatible with the development of Thailand’s new network infrastructure speed levels,” Surasak adds.
Huawei Cloud has been certified by more than 50 organisations, including ISOA27701, and aligns with Thailand PDPA.
Furthermore, Huawei Cloud is capable of providing both public and hybrid cloud, and with over 21 years of experience working with partners and clients in Thailand, leveraging its rounded expertise, Huawei has deep insights regarding the demands and challenges experienced by companies in the Thai market, the company says.
In addition, Huawei, as the ICT developer of the entire ecosystem (including hardware and software), can provide better overall performance than other cloud service providers, derived from its operations synergy, with 30 per cent more computing power and 30 per cent more cost-effectiveness, to best answer all clients’ needs, the company says.
Indorama Ventures joins World Economic Forum’s Global Plastic Action Partnership
Oct 08. 2020
By THE NATION
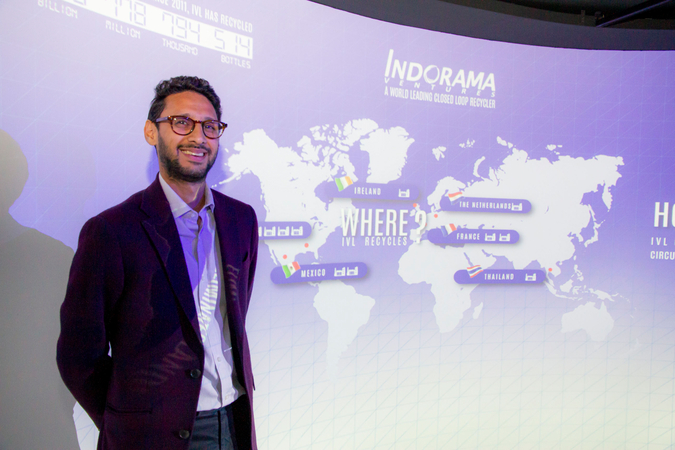
Indorama Ventures Public Company Limited (IVL) has joined the World Economic Forum’s Global Plastic Action Partnership (GPAP), the company announced on Wednesday.
The global partnership aims to reduce plastic leakage into the environment and is driving the transition to a circular economy for plastics.
“This partnership is aligned with Indorama Ventures’ 2019 commitment to increase the volume of recycled PET by at least 750,000 tonnes, pledging US$1.5 billion [Bt46.8 billion] towards achieving this target by 2025,” the firm said in press statement.
“By joining GPAP, we will advance our shared goal of ending PET plastic waste,” IVL chief sustainability officer Yashovardhan Lohia said. “Harnessing the convening power of the World Economic Forum, GPAP is bringing together governments, businesses and civil society to forge circular solutions – at both the global and national levels. Our recycling facilities across the world can close the loop and deliver a circular economy for PET plastic.
“In March this year we recycled our 50 billionth PET bottle since we started in 2011. We want to go further because we know PET is fully recyclable: by 2025 we aim to recycle 50 billion bottles a year. To achieve this, we have committed up to US$1.5 billion to expand the recycling infrastructure the world needs. The GPAP community is championing this shift to a circular economy and helping the world to understand the benefits of a closed-loop approach,” Lohia said.
“Joining GPAP is a clear statement of Indorama Ventures’ commitment to sustainability and advancing the circular economy,” said Kristin Hughes, GPAP director and member of the World Economic Forum Executive Committee. “Their global presence, fully integrated model and decades of recycling know-how means they are uniquely placed to close the loop for PET plastic.
“We look forward to working with Indorama Ventures and learning from their experience with collection systems around the world. Together we can drive high-potential solutions to improve collection, ensuring plastic never ends up as waste,” Hughes added.
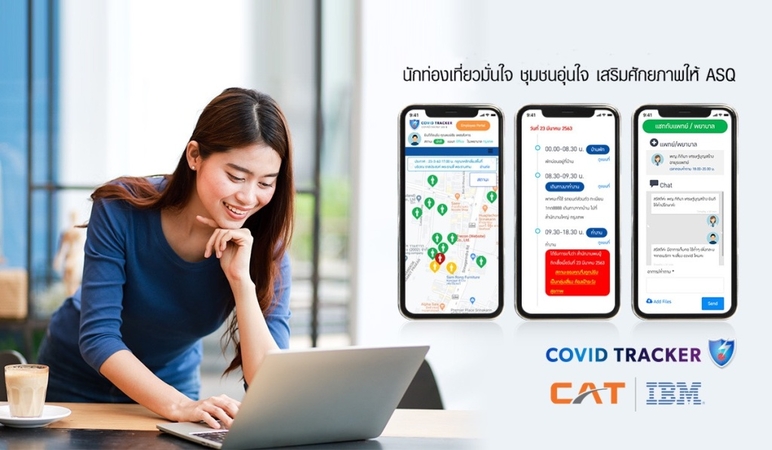
State telecom agency CAT Telecom has teamed up with IBM to develop the CAT Covid Tracker service for alternative state quarantine (ASQ) hotels to keep track of their guests’ health condition.
This system aims to help reduce risks and build confidence once Thailand reopens its doors to foreign tourists.
Dr Wongkot Vijacksungsithi, CAT’s senior executive vice president for digital business, said the application allows ASQ hotels to keep track of guests’ health digitally instead of getting staff to check on the guest in person.
Under the system, guests will be given a username and password and will be required to record their daily health information, such as temperature and symptoms.
The system will then automatically create files that can be submitted to the Department of Disease Control. The app also allows guests to talk directly to doctors or nurses from partnering hospitals.
The app also tracks the health of hotel staff, providing notifications if any cases are found so other personnel can protect themselves and treatment can be provided in a timely manner.
The CAT Covid Tracker, which took just one month to develop, leverages the capabilities of CAT’s cloud services, together with experiences in open-source management and support services from IBM.
Anywheel ties up with Dtac to launch bike-sharing service in Chiang Mai
Oct 08. 2020
By The Nation
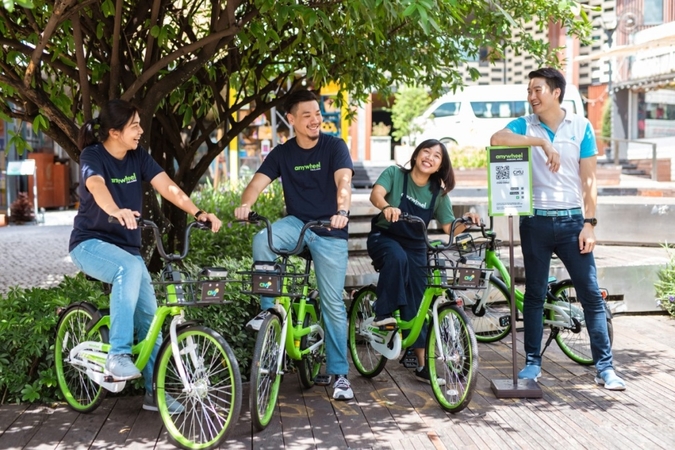
Anywheel, Singapore’s largest short-distance public transport provider, has chosen dtac Business’s internet of things (IoT) solutions to power its eco-friendly bike-sharing service in Chiang Mai.
Dtac Business is a unit of Total Access Communication (dtac), which was created to provide connectivity services and business solutions to corporate clients.
The Anywheel service supports the public transportation dimension of Chiang Mai’s aspiration of becoming a smart city in line with the Thailand 4.0 goals.
Cycling also supports efficient social distancing in the Covid-19 era.
Anywheel, which was founded by CEO Htay Aung, has been offering bike-sharing services for more than three years in Singapore, Malaysia, and most recently in Thailand.
Dtac Business has supported Anywheel from prototype development and testing, to the shipment of the first 1,000 IoT SIMs for installation onsite. Dtac Business IoT SIMs enable accurate vehicle fleet management with real-time positioning of all bicycles.
Rui Jie Seet, general manager of Anywheel Singapore said: “Anywheel kicked off its Thailand operation in Chiang Mai’s city centre and now has about 150 docking stations already installed and more than 6,000 users per day. The company also installed another 150 docking stations at Chiang Mai University and plans to expand its services to other university campuses and industrial complexes. I really hope that in the post-Covid era, locals and tourists will want to enjoy cycling and the scenery of Chiang Mai during the cool months. We know every year from January to March the air quality worsens, but I hope we can help improve the situation here.”
The Anywheel service is simple: download and open the Anywheel app, locate the nearest bicycle parking from its built-in map, scan QR code on the bike to unlock it. The base fare is Bt10, while a monthly pass starts at Bt200.
Anywheel also plans to develop their app to further suit urban needs with electric scooter services which would better serve longer journeys. Currently, electric scooters are only available in Singapore and Malaysia.
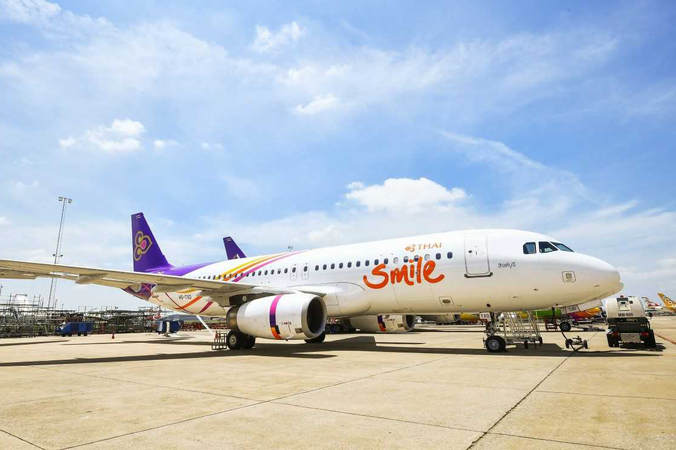
Thai Smile Airways, a subsidiary of Thai Airways International, plan to fly on four new routes in the last quarter of this year, chief executive officer Charita Leelayudth said.
The routes are: Suvarnabhumi-Nan, Suvarnabhumi-Nakon Panom, Nakhon Si Thammarat-Chiang Mai and Nakhon Si Thammarat-Udon Thani.
Charita said that the airline had witnessed an increase in passenger numbers after the resumption of operation on domestic routes since June 1.
She said that the airline saw new potential customer segments, including retirees.
By The Washington Post · David J. Lynch · NATIONAL, BUSINESS, POLITICS
ECON-ANALYSIS
Katie Button has put her bar stools into storage, laid off about half of her 130 employees and learned how to run a half-empty restaurant. But she remains at the mercy of Washington, D.C.
With the recession having blown a $3 million hole in her business, Button, 37, was counting on the federal government to provide one more round of financial aid to get Curate, her Asheville, N.C., restaurant, through the winter.
The coronavirus pandemic already has permanently shuttered 24 eateries in her scenic town of about 93,000 people. Button is trying desperately to avoid becoming the 25th.
“They can’t just walk away and go home to campaign,” she said. “It’s getting worse and worse…We need help.”
Button’s plight illustrates the economic consequences of Washington’s failure, after months of intermittent negotiation, to deliver a fresh economic stimulus package. Negotiations between President Donald Trump’s team at the White House and congressional Democrats have been on and off for months, though they appeared to be on again as of Thursday evening.
The president and his congressional adversaries picked a bad time for gridlock. Job growth is slowing, businesses are closing, and cooler weather is driving people inside where the virus flourishes. In September, for the first time since the pandemic began, the Homebase gauge of small business activity declined, signaling weakness ahead.
Failure now to agree on new help for struggling workers, companies and public agencies risks greater misery for millions of Americans, lower future living standards and a longer, slower road back to prosperity, economists said.
“It is completely avoidable, if they would just provide some stimulus. It is so obvious what needs to be happening,” said Nan Whaley, mayor of Dayton, Ohio, who confronts a $10 million budget gap that will likely force cuts to police and fire services.
When the coronavirus shutdowns began in March, the White House and Congress quickly agreed to spend nearly $3 trillion to help the economy through the worst of the pandemic. But much of that aid lapsed months ago, leaving households and businesses exposed.
The expiration this summer of enhanced unemployment payments triggered a decline in August’s disposable income reading. On again, off again negotiations between the administration and lawmakers failed to reach agreement on new measures to contain the virus and repair the economic damage.
In recent days, companies that endured the pandemic’s first half-year without permanentjob losses — such as Walt Disney, Houghton Mifflin and Allstate — announced layoffs. United Airlines, American Airlines and other air carriers hurt by the collapse of travel have also begun tens of thousands of cuts.
Earlier this week, the owner of Regal Cinemas announced it would close all of its 663 movie theaters in the U.S. and United Kingdom, imperiling 45,000 jobs. And state and local governments, which already have trimmed 1.2 million workers over the past year, face budget shortfalls that will require additional pink slips.
Furloughs once billed as temporary have hardened into permanent job loss for an increasing number of workers. And almost 11 million Americans who had jobs in February remain unemployed, even as the labor market is slowing.
A total of 661,000 people were hired in September, down sharply from June’s 4.8 million.
At last month’s hiring pace, it will take until early 2022 to regain February’s number of jobs.
In Bowling Green, Ky., Amy Perry, 51, a former loan company customer service representative, filed for unemployment on June 1. But more than four months later, state backlogs mean she’s still waiting for her first check.
“I have not gotten a penny of unemployment. I get a robo-call every two or three days, saying I’m in the queue,” she said. “I’m at a loss. I don’t know what to do.”
She and her husband, Jonathan, 49, have secured six months of forbearance on their mortgage payments. And they expect to cover their other bills with his salary as a driver for UPS.
“We’re like everyone else,” she said. “We have a mortgage. We have bills to pay. It’s been hard.”
Perry has autoimmune disorder, and her employment prospects amid a contagion are slim. She and her husband plan to sell their home in the spring and downsize to a smaller place. Even if Washington eventually provides additional help, she worries about the long run.
“How long can they continue the stimulus packages?” she said. “Our country is so much in the hole. I worry about what we’re leaving our children.”
The unique nature of this recession also worries some economists. The U.S. failure to contain the coronavirus has interrupted the education of millions of American schoolchildren and caused a sizable labor force exodus of women who lack adequate childcare.
“This could be permanently damaging,” said Lisa Cook, an economics professor at Michigan State University, who worked in the Obama White House. “The whole economy is going to be worse off because these kids are worse off. We are losing our future labor force. We’re settling for lower living standards in the future.”
To be sure, after suffering the sharpest plunge in recorded history during the second quarter, when output contracted at an annual rate of 31 percent, the economy has bounced back stronger than many economists anticipated in the dark days of March.
Tom Porcelli, chief U.S. economist for RBC Capital Markets, cites a steady decline in the total of continuing claims for unemployment benefits as a sign of genuine progress. From a peak of 22.8 million in early May, the number of those receiving jobless benefits has been cut in half, according to the Bureau of Labor Statistics.
Yet at year end, the U.S. economy is still expected to be smaller than it was a year ago. And nearly 98,000 businesses have permanently closed their doors, according to Yelp, the online review site.
“The economy needs a bridge and the bridge is fiscal stimulus,” he said. “There is absolutely a need.”
Without immediate pump-priming, the economy may come dangerously close to “stall speed” in the last three months of the year, according to Oxford Economics. Economist Michael Feroli of JPMorgan Chase is more upbeat, projecting annualized growth of 2.5 percent in the fourth quarter.
The president’s abandonment of talks with Pelosi sent the Dow Jones industrial average sharply lower on Tuesday into a nearly 600-point plunge on Tuesday. Investors Wednesday took solace from late-night Trump tweets backing separate measures for a new round of $1,200 individual checks or an airline industry bailout, which already have been rejected by Democrats who favor a comprehensive approach.
The importance of fiscal support was evident this summer, when Walmart credited government stimulus checks for delivering a more than 9 percent gain in same-store sales compared to the same period in 2019.
But in July, the final month of the company’s second quarter, that increase dipped to 4 percent, as customers retrenched in anticipation of the expiration of enhanced unemployment benefits, executives told investors.
The earlier benefits were critical to supporting consumer spending at a time of high unemployment. By halting support, at least for now, the administration and Congress are defying increasingly loud pleas for help from the Federal Reserve.
Earlier this week, Federal Reserve Chairman Jerome Powell told an audience of economists that the Fed had “deployed the full range of tools at our disposal,” but needed those who control government spending to act.
“There is still a long way to go,” he said. “…Too little support would lead to a weak recovery, creating unnecessary hardship for households and businesses.”
To some economists, a premature end to government support risks repeating mistakes made after the 2008 housing bubble collapse. Layoffs then by cash-strapped state and local agencies delayed the return to pre-recession unemployment rates by four years, according to the Economic Policy Institute.
The current recession is gouging similar holes in public accounts, forcing officials to ax teachers, recreation aides and first responders. Such belt-tightening only hurts the local economy, depressing tax revenue and requiring further layoffs, officials said.
In Dayton, Whaley said she already has laid off “dozens” of workers at the city’s airport and closed two of the three municipal golf courses. Further cuts are likely in police and fire services.
“These are real tough decisions we’re going to have to make. There’s no fat left here,” she said.
In Asheville, with the state limiting indoor dining, Curate’s revenue is stalled at just 40 percent of last year’s figure. But Button’s loss is not her problem alone. Her customary payments to area workers and farmers have dropped by $2.5 million.
Button, who owns two successful eateries, got a government-backed small business loan that she says helped her navigate the pandemic’s first months. But she’s watched in frustration as lawmakers and administration officials spent months debating additional economic aid even as public health officials warn Americans to be cautious about venturing into restaurants.
The Independent Restaurant Coalition, an industry group, hoped for a $120 billion bailout in any final stimulus measure.
“You can’t say we’re not different from other industries,” she said. “Ninety to ninety-fie percent of every dollar that we take in is going right back out the door into our communities. The risk of doing nothing is far greater than the risk of giving restaurants what they need.
—-
David J. Lynch is a staff writer on the financial desk who joined The Washington Post in November 2017 after working for the Financial Times, Bloomberg News and USA Today.
By Syndication Washington Post, Bloomberg · Claire Ballentine, Vildana Hajric · BUSINESS, US-GLOBAL-MARKETS U.S. stocks rose to almost five-week highs as traders speculated that lawmakers will eventually provide more stimulus and corporate deal activity increased. Treasury bond yields dropped and the dollar weakened.
The S&P 500 finished up 0.8% after conflicting comments from President Donald Trump and House Speaker Nancy Pelosi, D-Calif., whipsawed equity markets earlier in the day. Energy, utilities and financials were the biggest gainers in the benchmark index, with crude oil rallying as Hurricane Delta approached the already battered Louisiana coast.
“It’s likely that there will continue to be near-term volatility due to the back-and-forth over a deal,” UBS Global Wealth Management strategists led by Mark Haefele wrote in a note. “A stimulus deal will be struck eventually, central banks will continue to stay supportive, and medical developments still have scope to surprise, in our view.”
Eaton Vance leaped after the investment firm agreed to be taken over by Morgan Stanley. IBM surged after saying it will spin off its infrastructure unit. Regeneron Pharmaceuticals rose after Trump said its antibody cocktail was the “key” to his quick recovery. The president said he would authorize its emergency use.
Bulls are now back in control of a market that’s increasingly betting that a Joe Biden presidential victory and gains by Democrats in Congress will be good for equities. The scenario seems to be somewhat quelling volatility even as risks from a split in government to a resurgence of coronavirus cases threaten the economic rebound.
“At this point the market is likely projecting a Biden victory,” said Bill Fitzpatrick, managing director at Logan Capital Management. “It’s a scenario worth considering that we don’t get results for a month or so after the election, that’s a real possibility.”
Meanwhile, Pelosi said there won’t be a standalone bill on airlines without a guarantee the other stimulus items are going to be addressed. Trump had earlier touted progress in talks even though there was no sign the two sides are any closer on a deal.
Elsewhere in markets, airlines led European shares higher, helped by as optimism over a covid-19 treatment. U.K. jet engine-maker Rolls-Royce Holdings posted its best five-day performance on record, after shoring up its finances.
Oil futures rose 3.1% after Gulf of Mexico producers shut in 1.7 million barrels a day of crude production ahead of the storm that’s expected to slam into the Louisiana coast on Friday. Gold increased for a second day.
– – –
These are some of the main moves in markets:
Stocks
– The S&P 500 index increased 0.8%, to 3,446.85 as of 4:01 p.m. New York time, the highest in almost five weeks.
– The Dow Jones industrial average rose 0.4%, to 28,425.71, the highest in five weeks.
– The Nasdaq composite index climbed 0.4%, to 11,420.98, the highest in almost five weeks.
– The Nasdaq 100 index rose 0.4%, to 11,550.94.
– The Stoxx Europe 600 index jumped 0.8%, to 368.31, the highest in almost three weeks.
Currencies
– The Bloomberg Dollar Spot Index decreased 0.2%, to 1,170.35.
– The euro was little changed at $1.176.
– The Japanese yen was little changed at 106 per dollar, the weakest in almost four weeks.
Bonds
– The yield on 10-year Treasuries fell two basis points, to 0.76%.
– The yield on 30-year Treasuries decreased two basis points, to 1.56%.
– Germany’s 10-year yield fell three basis points, to -0.52%, the largest drop in more than two weeks.
– Britain’s 10-year yield declined one basis point, to 0.289%, the biggest fall in more than a week.
Commodities
– West Texas Intermediate crude climbed 3.2%, to $41.26 a barrel, the highest in almost three weeks.
– Gold strengthened 0.3%, to $1,894.64 an ounce.
– Copper gained 0.2%, to $3.04 a pound, the highest in more than two weeks.
 Abel Deng, chief executive officer of Huawei Technologies (Thailand) Co Ltd
 David J. Lynch