Investment in Thailand’s industrial estates will return to normal in the post-Covid-19 era, as companies from China and Taiwan are likely to relocate production bases to Thailand in response to the US-China trade war, said Industrial Estate Authority of Thailand (IEAT) governor Somchint Pilouk.
The easing of the lockdown will also bring new investment in the estates, she added.
The IEAT has launched promotional campaigns to draw more investment to the zones.
Two new estates opened recently – the Pinthong Industrial Estate 6 in Rayong and World Food Valley Thailand in Ang Thong – while two more are set to launch in Chonburi, namely the Rojana Industrial Park 2 and Asia Clean Industrial Park.
The opening of the Chonburi parks will bring the total land occupied by industrial parks to 177,261 rai, of which 39,332 rai is operated by the IEAT and the rest is jointly operated.
Of the total, 114,852 rai is allocated for lease and sales, of which 92,019 rai has already been leased or sold.
Accumulated investment in these zones is Bt4 trillion, with 6,112 factories and 515,962 jobs.
Jul 10. 2020Tada Phutthitada president of the Thai Bond Market Association
By The Nation
Investors are starting to return to the bond market amid signs Thailand is winning the battle to contain Covid-19, say Thai Bond Market Association executives.
Outstanding debt in the Thai bond market in the first half of 2020 stood at Bt13.69 trillion, a 1.25 per cent rise fuelled largely by the issuance of government bonds. However, issuance of corporate bonds in the first half plunged by 43 per cent year on year due to the Covid-19 impact, Tada Phutthitada president of the Thai Bond Market Association, said on Thursday (July 9). Bond transactions in the secondary market increased 5 per cent year on year.
However, signs of a bond market recovery have emerged as the number of Covid cases remains relatively low in Thailand, he added.
Recent debenture issuances were welcomed by investors and sold out, even those corporate bonds with a credit rating below investment grade, including high-yield bonds, he said.
Corporate bonds with a credit rating of BBB- to BBB+ sold out in June, after issuances in April and May sold only 41.4 per cent and 93 per cent of their targets respectively.
Issuances of high-yield bonds also secured 100 per cent investor subscriptions in June, up from 34.6 per cent in April and 87.6 per cent in May, he said.
About 10 companies have restructured and rescheduled debenture debt payments worth a total Bt7.2 billion in the first half of this year. These corporate bonds are rated at BB+ or not-rated. Their redemption periods have been extended to between six months and two years. Tada was optimistic that insurers will not default on their debt obligations this year.
“In most cases issuers plan to meet bond redemption [deadlines], rather than placing hope on bond rollovers. Issuers and bankers have reassured me that the problem is manageable and defaults are unlikely this year,” said Tada.
He projects that companies will raise Bt800 billion from the bond market this year, down from the previous projection of Bt850 billion.
In the first half of 2020, issuers raised Bt323 billion via corporate bonds, down 43 per cent year on year, or 22 per cent on average for five-year bonds.
Energy firms are expected to raise Bt160 billion to finance their mergers, acquisitions and expansion abroad in the second half of this year, he said.
Foreign investors sold government and central bank bonds worth about Bt108.5 billion in the first half. They held government and central bonds worth Bt811.1 billion, representing 9 per cent of total government outstanding bonds, down from 10.45 per cent at the end of last year.
However, they bought Bt23.3 billion in government bonds in June and Bt11.7 billion in early July after seeing progress in containing the spread of Covid-19. Foreign investors, however, will be cautious due to concerns over tourism and export contraction as the economy recovers, he said.
Bond yields were also volatile in the first half of the year. Yields for two-year and 10-year bonds dropped 69 basis points and 18 basis points respectively from early this year to 0.45 per cent and 1.28 per cent at the end of second quarter. It was a new record low for two-year bonds.
Tada expects the Bank of Thailand’s Money Policy Committee to maintain the historically low policy rate at 0.5 per cent until the end of this year in order to accommodate economy recovery, adding that the central bank might implement extra measures to support the economy.
The Stock Exchange of Thailand (SET) Index rose 3.35 points or 0.25 per cent to close at 1,365.81 today (July 9), with total transactions hitting Bt72.680 billion with an index high of 1,370.80 and a low of 1,358.03.
During the morning session, a stock analyst at Krungsri Securities said he expected the index to fluctuate between 1,355 and 1,370 due to a lack of new factors to stimulate the economy.
“The market gained positive sentiment over hopes of a V-shaped recovery as US, European and Chinese economic data showed a significant rise last month and there was speculation in stocks whose second-quarter performance was expected to show a big improvement,” the analyst said.
“However, the market was under pressure from uncertainty following the Covid-19 outbreak, as the number of new cases in the US continues to increase by approximately 61,000 patients per day.”
The top 10 stocks with the highest trade value today were STGT, AOT, PTT, STA, PTL, MINT, EA, ADVANC, TOP and BAM.
As of 4.30pm, the price of crude oil dropped by US$0.18 or 0.44 per cent to $40.72 per barrel, while gold rose by $2.80 or 0.15 per cent to $1,823.40 per ounce.
Asian indices were on the rise:
Japan’s Nikkei Index closed at 22,529.29, up 90.64 points, or 0.40 per cent.
China’s Shanghai SE Composite Index closed at 3,450.59, up 47.15 points, or 1.39 per cent, while Shenzhen SE Component Index closed at 13,754.74, up 348.37 points, or 2.60 per cent.
Hong Kong’s Hang Seng Index closed at 26,210.16, up 80.98 points, or 0.31 per cent.
South Korea’s KOSPI Index closed at 2,167.90, up 9.02 points, or 0.42 per cent.
Taiwan’s TAIEX Index closed at 12,192.69, up 22.50 points, or 0.18 per cent.
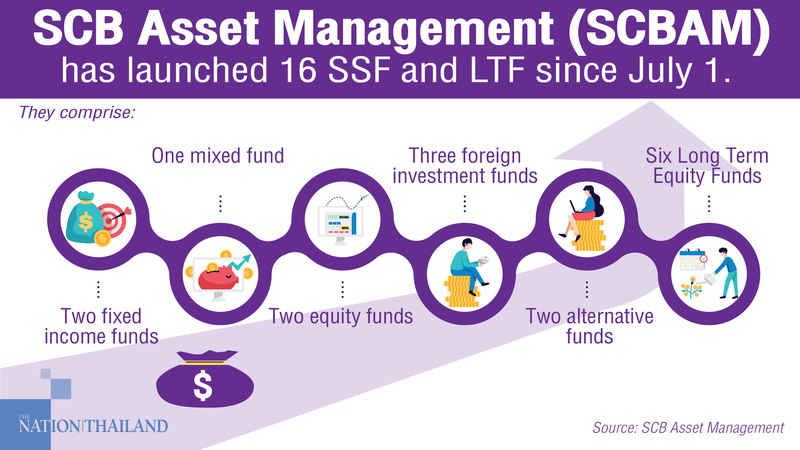
SCB Asset Management (SCBAM) has launched 16 Super Savings Funds (SSF) and long-term equity funds (LTF), covering investment in all assets since July 1 this year.
Narongsak Plodmechai, chief executive officer at SCBAM, said that this move aimed to provide a variety of investment options for several investors.
He said the 16 SSF and LTF funds are:
Two fixed income funds
▪︎ SCB Short Term Fixed Income Plus Fund (Super Savings Fund): This fund invests in deposits, government bonds and debt instruments, both domestic and offshore in the short term.
▪︎ SCB Fixed Income Plus Fund (Super Savings Fund): Invests in deposits, government bonds and debt instruments both domestic and offshore within one to three years.
One mixed fund
▪︎ SCB Smart Plan 2 Open End Fund (Super Savings Fund): Invests in stocks and debt instruments. The target volatility is approximately 5 per cent per year.
Two equity funds
▪︎SCB Selects Equity Fund (Super Savings Fund): Invests in 30 Thai stocks that have strong fundamentals to generate outstanding returns.
▪︎SCB Dividend Stock Open End Fund (Super Savings Fund): Invests in Thai stocks that pay dividends regularly.
Three foreign investment funds
▪︎ SCB Global Strategic Investment Fund (Super Savings Fund): Invests in debt instruments of foreign private sectors, managing by PIMCO, the world-class fund manager.
▪︎ SCB US Equity Fund (Super Savings Fund): Focuses on generating returns similar to the S&P500 Index, the most valuable index in the US.
▪︎ SCB Low Volatility Equity Fund (Super Savings Fund): This fund invests in stocks worldwide that have good fundamentals and low volatility.
Two alternative funds:
▪︎ SCB Gold THB Hedged Open-End Fund (Super Savings Fund): Focuses on generating returns similar to the gold bar price in the global market.
▪︎ SCB Property and Infrastructure Flexible Fund (Super Savings Fund): Invests in property and/or infra units, including real estate investment trust, registered both domestic and foreign.
Six Long Term Equity Funds (LTF): These existing funds will enable investors to avail investment opportunities.
Aeon Thana Sinsap (AEONTS) reported a 46-per-cent plunge in net profit for the first quarter ended May 31 despite revenue increasing by 3 per cent.
Aeon Thana Sinsap (AEONTS) reported a 46-per-cent plunge in net profit for the first quarter ended May 31 despite revenue increasing by 3 per cent.
The company had a net profit of Bt530 million on revenue of Bt5.65 billion.
Aeon was the first non-bank organisation to announce its financial results after being impacted by the Covid-19 crisis.
The decrease in profit was attributed to higher provision for bad debt and doubtful account, which had increased by 72 per cent to Bt2.39 billion.
Korakot Sawetkruttamat, Kasikorn Securities’ assistant director, said that the performance of Krungthai Card (KTC) would be like AEONT’s, since the two companies were similar to each other.
In the second half of this year, Korakot predicted that the stocks of those credit companies would not recover to their previous level, which will affect profits, especially KTC and Srisawad Corporation that previously charged high interest.
“The performance of credit company stocks will tend to be weak in the next one to three years” he added. “The high coverage ratio of AEONTS reflected that the corporation has prepared itself to deal with the non-performing loan [NPL], which will be heightened in the future. AEONTS’ NPL would rise from the present 3.7 per cent to at most 10 per cent in the worst case”.
However, the stock price of AEONTS on Wednesday (July 8) could return to positive zone, due to its NPL information that would increase investor confidence.
MCOT does not need a rehabilitation plan despite recording a Bt877-million loss in the first quarter, the Ministry of Finance said.
The State Enterprise Policy Office (Sepo) has said that MCOT Pcl is suffering from lack of liquidity, but it is still at a manageable level, a source at the ministry said. MCOT is therefore not on the list of state enterprises that require Sepo’s rehabilitation programme.
“MCOT’s liquidity problem stemmed from the auction of digital TV channels and losing programmes that Chanel 3 used to produce for it, now scrapped due to MCOT’s restructuring of its TV business,” said the source. “Furthermore, several business partners are late in paying advertising fees to MCOT due to the economic impact of Covid-19.
“MCOT’s executives are discussing the problem and should be able to come up with a plan soon, as MCOT’s problem is more manageable than that of Thai Airways International, which has substantial debt on top of lack of liquidity,” added the source.
MCOT reported an Bt870-million loss in the first quarter of 2020, a steep rise from a Bt32-million loss in the same period last year. Revenue in the first quarter was Bt467 million, down 21 per cent year on year. MCOT’s most profitable businesses are radio (29 per cent of revenue), TV (24 per cent), concession contract (22 per cent) and services for digital TV network (19 per cent).
By The Washington Post · Lori Aratani · BUSINESS, TRANSPORTATION, US-GLOBAL-MARKETS, CAREER-WORKPLACE
United Airlines announced Wednesday that despite receiving billions in federal aid, it may furlough nearly 36,000 employees Oct. 1, a scenario one union official called a “gut punch.”
The number represents nearly 40 percent of the Chicago-based airline’s workforce.
Government grants received through the $2 trillion Cares Act require airlines to keep front-line workers on the job through Sept. 30. In addition to receiving $4.9 billion in grants, United signed a letter of intent this week to accept roughly $4.5 billion in loans through the law. But executives said that with demand for air travel unlikely to return in 2020, they have no choice but to warn employees of layoffs.
“The reality is that United simply cannot continue at our current payroll level past October 1 in an environment where travel demand is so depressed,” the airline said in a memo sent to employees. “And involuntary furloughs come as a last resort, after months of companywide cost-cutting and capital-raising.”
Under the Worker Adjustment and Retraining Notification Act, most firms with 100 or more employees must give them 60 days’ notice of mass layoffs or plant closings. What is happening at United will probably be repeated as carriers struggle to survive the worst economic crisis in the industry’s history. Airline executives have already signaled they expect to emerge from the crisis with smaller workforces.
In a message to employees in March, Oscar Munoz, then United’s chief executive, and Scott Kirby, then the airline’s president, said that while taking care of employees would be their top priority, “if the recovery is as slow as we fear, it means our airline and our workforce will have to be smaller than it is today.”
Still, Wednesday’s announcement was a blow to employees.
“The United Airlines projected furlough numbers are a gut punch, but they are also the most honest assessment we’ve seen on the state of the industry,” said Sara Nelson, president of the Association of Flight Attendants-CWA, which represents nearly 50,000 flight attendants at 19 airlines, including United.
United employs roughly 95,000 people worldwide. The number of furloughs could be fewer depending on how many employees accept early retirement, voluntary separation or other programs, executives said. Already, more than 20,000 United employees have taken voluntary unpaid leaves of absence. The airline has also cut other costs, but officials said it is burning through $40 million a day.
Demand for travel has increased slowly but remains far below 2019 levels. In its June forecast, the International Air Transport Association estimated that carriers worldwide would lose $84.3 billion in 2020. Revenue is expected to fall 50 percent, from $838 billion in 2019 to $419 billion this year.
United said even though it has begun to add flights, capacity is expected to be down 75 percent in July compared with the same month last year. Some growth is anticipated in August, but the numbers are still projected to be down 65 percent compared with last August.
The recent spike in coronavirus cases in numerous states, including California, Florida, Texas and Arizona, is further diminishing hopes of a recovery, with many saying demand probably won’t return to normal levels until treatments or a vaccine become widely available. On Wednesday, the number of confirmed infections in the United States surged past 3 million, according to data tracked by The Washington Post, and there have been more than 129,00 deaths.
The AFA and other unions have called on Congress to extend payroll support offered through the Cares Act, warning that layoffs in aviation will ripple through the entire economy. U.S. airlines and cargo carriers directly employ an estimated 750,000 worldwide.
“Should October 1 arrive without extending the [Payroll Support Program] grant job program mass layoffs are inevitable, as airline executives have acknowledged. Hundreds of thousands of workers will lose their jobs and health insurance – not only in aviation, but across our entire economy,” union officials said in a letter last month to Democratic and Republican leaders on Capitol Hill. “Airline industry employment cannot simply be put back together overnight, and mass layoffs will do great damage to the sector, with potentially irrevocable consequences.”
Added Nelson on Wednesday: “Congress must extend the PSP in order to avoid hundreds of thousands of layoffs from an industry that normally drives economic activity for every other sector and supports more than 11 million jobs. Failing to maintain this successful jobs program will have a ripple effect across the economy. Conversely, a clean extension of the program helps prime us for economic recovery.”
Joe DePete, president of the Air Line Pilots Association, International – which represents more than 63,000 pilots at 34 airlines in the United States and Canada said: “The economic impact COVID-19 has had on the airline industry has been profound for the workers who keep our skies safe and our world connected. Unfortunately, in the past few weeks, thousands of pilots and crew members have received furlough notices and, absent congressional action, it is likely that there will be more to come.”
On a phone call with reporters Wednesday, United executives said they were aware of the unions’ push for an extension to the payroll support program, and while they would continue to engage with leaders in Washington, they were not counting on Congress to act.
“We don’t feel like we can count on additional government support,” a United executive on the call said.
At least one lawmaker signaled support for an extension.
“United’s announced furloughs are a canary in the coalmine for the industry,” Sen. Richard Blumenthal, D-Conn., said in a statement. “It’s clear that an extension of the Payroll Support Program is necessary to help airline workers keep their jobs and health insurance in the months ahead. I will continue to push for additional aid that puts workers and consumers first – and keeps airlines accountable.”
Of the 36,000 United employees who could be affected, roughly 15,000 are flight attendants, and 11,000 are customer service or gate agents. About 1,800 catering workers, 1,000 contact center employees, 5,500 technical operations employees and 225 network operations workers also could be affected. Among pilots, 2,250 could be harmed.
“Furloughing employees is corporate triage with a terrible impact on thousands of United families,” said Todd Insler, chairman of the United Master Executive Council of the ALPA. “This is a direct result of the global pandemic which has affected millions around the world and nearly grounded our industry. ALPA is doing everything we can do to support our fellow pilots, and we expect to have final agreement on several voluntary programs which will mitigate these furloughs.”
Earth Tech Environment (ETC), a subsidiary of Better World Green (BWG), will be listed on the Market for Alternative Investment (mai) and launch its initial public offering (IPO) in August.
The funds will be used to construct additional garbage power plants, expecting the government to open additional electric power bidding over 400 megawatts this year.
This move followed the BWG shareholders’ resolution.
Aekkarin Luengviriya, ETC president and chief executive officer, said that the company’s registered capital was Bt1.120 billion, while there are 2.240 billion shares with par value of Bt0.50 per share.
“The company will sell 600 million shares of which 60 million shares, or 10 per cent, have greenshoe option to gain confidence among investors during market volatility,” he said.
He added that to reward the current BWG shareholders and increase the value of BWG shares, the company will allow current BWG shareholders to subscribe to ETC’s 95.8 million newly issued ordinary shares.
“Shareholders who hold 40 BWG shares can subscribe for one new ETC ordinary share,” he added.
Currently, ETC’s main business is the garbage power plant, while the company will recognise revenue from three power plants with production capacity totalling 16.5MW by this year. The company’s electricity charge rate was between Bt5.83 and Bt6.83 per unit.
ETC’s parent company will be responsible for the distribution of refuse-derived fuel, a material for producing electricity, while subsidiaries will be responsible for the construction of power plants.
Meanwhile, ETC’s earnings before interest, tax, depreciation and amortisation (EBITDA) was Bt25 million per megawatt, higher than other types of power plants.
ETC also gained support from the Board of Investment (BOI) for eight years and the company can ask for BOI’s assistance for another five years.
ETC reported revenue of Bt362.39 million in 2019, up from Bt325.24 million in 2018, while the company’s EBITDA was Bt202.90 million, down from Bt224.40 in 2018 due to expenditure incurred in the construction of two additional power plants.
Meanwhile, ETC’s net profit in 2019 was Bt57.55 million, down from Bt66.96 million in 2018.
The company’s revenue and net profit in the first quarter of this year was Bt134.90 million and Bt24.18 million respectively.
Petrochemical firm IRPC said its performance in the second half should improve since its profit margin will rise in line with the increasing price of petroleum and petrochemical products.
Noppadol Pinsupa, director of IRPC, said the company’s refinery should be able to produce 205,000 barrels per day, and its primary profits should be between US$9 and $10 (Bt281 and Bt312) per barrel, rising from $8.7 per barrel last year.
However, he said, this depends on the direction the crude oil takes, adding that the price of crude oil for the rest of this year should hover between $40 and $50 per barrel, versus $60 per barrel last year.
Noppadol added that IRPC should do better than it did in the first quarter, when it was at a deficit of Bt8.91 billion, after the market GIM had increased to $8 or $9 dollar per barrel.
Also, due to several improved factors, its earnings before interest, taxes, depreciation and amortisation (EBITDA) should not contract in the second quarter, like it did by Bt6.44 billion in the first quarter.
In addition, IRPC has launched a five-year (2020 to 2025) strategy called “Strengthen IRPC” in a bid to cope with the Covid-19 fallout. Under this strategy, its EBITDA should reach Bt20 billion in 2025 and Bt30 billion in 2030. The firm’s EBITDA was Bt5.94 billion in 2019, the director added.
IRPC’s new strategy focuses on increasing specialised products as well as the expansion of sales channels. The strategy was relevant to the stock-and-cost management and the total budget spent in each aspect of “Strengthen IRPC” added up to Bt2.18 billion.
Noppadol added that IRPC holds a 50 per cent state in Mytex Polymers, the manufacturers of PP compound plastic. He said this investment will help the corporation expand into the automobile industry at a faster rate.
By Nu To Van, Sukanok Suthinan Special to the Nation
At a time when people are spending more time at home and companies are increasingly digitising their business and shifting “online”, it may not come as a surprise that governments are looking for ways to cast their tax net on these online activities.
Much like some other Southeast Asian countries, like Malaysia and Singapore, Thailand is in the process of introducing its own version of a digital services tax.
Only June 9, the Cabinet approved a draft bill to impose VAT on digital services that require foreign digital service providers, while platforms have to register for pay VAT in Thailand. In line with guidelines from the Organisation for Economic Cooperation and Development (OECD), the draft bill focuses on providing “clarity” on VAT taken for transactions between businesses and consumers.
What does it cover and what are the key requirements?
In Thailand, the digital services tax will be in the form of VAT imposed on electronic services transactions. Based on a broad definition of electronic services in the draft bill, most online activities are expected to be covered. For instance, services related to the supplying of digital content, like online gaming, music and movie streaming, e-books, online advertising services, providing online learning courses or webinars as well as online subscriptions to news website are all likely to be covered under the new digital services tax.
Companies that are caught by this new digital tax need to register for VAT (either as a service provider or electronic platform). They can do this electronically and the Revenue Department is expected to introduce a new simplified monthly VAT return to accommodate this process. Companies required to pay this digital tax are however not required to issue tax invoices to their customers and they cannot claim any input VAT from expenses incurred in Thailand.
Who will bear the impact?
Only foreign digital service providers or electronic platforms with an annual turnover exceeding Bt1.8 million are required to register for and pay VAT in Thailand. For electronic platforms like online shopping platforms and online travel agencies, the revenue threshold would apply to two sources – revenue generated by their own platform and revenue generated from foreign digital service providers who use their platform to provide services to customers (non-VAT registrants).
Upon becoming a VAT registrant, 7 per cent VAT of the revenue generated from digital services needs to be reported and remitted to the Revenue Department on a monthly basis.
Given the relatively low turnover threshold, it is likely that most digital service providers or digital platform owners will have to start paying VAT in Thailand once the new digital services tax is introduced. The big question, of course, is who will ultimately be “paying” the VAT. Given that the service providers and platforms will not be able to recover the VAT, it may well be that Thai consumers will ultimately have to pay a higher price to receive the same digital services in the future.
So, what’s next?
The draft bill will now be forwarded to the House for further consideration. Hopefully things will be fleshed out during this process, particularly on some of the practical implementation issues. For example, the current definition of the digital services is very broad, and as mentioned earlier could cover a wide range of online activities. Whether or not this was by design or unintentional, it would be helpful for companies to clearly understand the exact digital services coverage and to assess whether they are being impacted by this new tax.
It would also be interesting to see how the Thai Revenue Department is going to enforce the new digital services tax in the future. For example, how will the Revenue Department track and audit the reported revenue by overseas service providers/platforms?
Will they require local banks to start disclosing their customer’s credit card or payment information or will they start using Multilateral Convention on Mutual Administrative Assistance in Tax Matters (MAC) with other countries to obtain this information? And what happens in case of non-compliance? Will this lead to potential penalties or will the Revenue Department simply start blocking their IP addresses?
Many practical questions still remain, and it is hoped that before the law is implemented (expected to be by 2021), these issues will at least be considered and addressed by the government in guidelines and secondary laws. But what is clear is that Thailand has jumped on the “digital services tax” bandwagon and it won’t be long before digital service providers and platforms need to start preparing for this new tax.
In our next article, we will be looking at how other countries are implementing their digital services tax, how they deal with some of the abovementioned practical issues and how companies can start preparing for this new digital services tax in Thailand.
Sukanok Suthinan
Nu To Van is partner, while Sukanok Suthinan is senior manager of tax and legal services at Deloitte Thailand.
 Tada Phutthitada president of the Thai Bond Market Association