Thailand’s export of jewellery and ornaments between January and May this year surged 108.01 per cent year on year to US$9.579 billion (Bt298 billion), according to Deputy Commerce Minister Weerasak Wangsuphakijkosol.
However, if gold shipments are not included, export of jewellery and ornaments have actually dropped 34.8 per cent to $1.984 billion. Shipment of gold, however, has risen 386.1 per cent to $7.595 billion.
He attributed the drop in exports to the Covid-19 pandemic, which has forced several countries to enforce lockdown measures. As a result, consumers have been cautious about spending.
The demand of gold, however, has risen as people are rushing to buy this asset as a safe haven at a time when the economy is sapped. He added that if there is no second wave of Covid-19 infections and countries continue to ease lockdown measures, Thailand’s jewellery and ornament exports should pick up in the second half of this year.
Jul 05. 2020A chain secures locked gates in front of a shuttered store in Madrid, Spain, on May 7. MUST CREDIT: Bloomberg photo by Paul Hanna
By Syndication Washington Post, Bloomberg · Enda Curran · BUSINESS, US-GLOBAL-MARKETS
The world economy is entering the second half of 2020 still deeply weighed down by the coronavirus pandemic with a full recovery now ruled-out for this year and even a 2021 comeback dependent on a lot going right.
It’s a scenario few if any predicted at the start of the year when most economists were banking on another year of expansion and a U.S. and China trade agreement was meant to give corporate and investor confidence a shot in the arm.
Instead, the rare pandemic forced swathes of the global population into what the International Monetary Fund dubs ‘The Great Lockdown.’ Central banks and governments responded with trillions of dollars in unprecedented support to prevent markets from melting down and to keep furloughed workers and struggling companies afloat until the virus passed.
Even with those rescue efforts, the world is still suffering its worst economic crisis since the Great Depression. While some gauges of manufacturing and retail sales in major economies are showing improvement, hopes for a V-shaped rebound have been shattered as the reopening of businesses looks shaky at best and job losses risk turning from temporary to permanent.
It’s an economic trajectory Federal Reserve Bank of Richmond President Thomas Barkin has likened to riding the elevator down, but needing to take the stairs back up.
“There is a real danger of confusing rebound with recovery,” Carmen Reinhart, the World Bank’s chief economist, said at the Bloomberg Invest Global conference on June 23. “True recovery means you are at least as well off as you were before the crisis started and I think we are a long way off that.”
Much depends on the spread of the coronavirus, a vaccine for which remains out of grasp. The World Health Organization warns the worst of the pandemic is still to come as cases top 10 million and deaths have risen beyond 500,000. And even in countries where the virus appeared contained, fresh flare ups are frequent.
The IMF estimates that by the end of this year 170 countries – or almost 90% of the world – will have lower per capita income. That’s a reversal from January, when it predicted 160 countries would end the year with bigger economies and positive per capita income growth.
It’s now likely that global gross domestic product by the end of 2021 will in many cases still be lower than where it was at the end of 2019, according to HSBC Holdings Plc economists led by Janet Henry. Bloomberg Economics describes it as ‘Goodbye Victory V, Hello Worry W.’
Central bankers remain on the alert to do more. Federal Reserve Chairman Jerome Powell has warned the outlook is “extraordinarily uncertain” and European Central Bank President Christine Lagarde has spoken of a “restrained” recovery that will change parts of the economy permanently.
To be sure, there are pockets of recovery that could gain traction. Morgan Stanley economists are sticking to forecasts of a V-shaped recovery, pointing to positive surprises in recent economic data, especially in the U.S. and euro region.
Global markets are split between investors who are betting on a V-shape recovery, and those expecting significant dislocations. The MSCI All-Country World Index of global stocks has gained nearly 40% from a March low, but is still down about 6% this year, as investors bet policy stimulus around the world will cushion the economic impact from the pandemic. U.S. 10-year Treasury yields have tumbled by more than 100 basis points this year to around 0.67%.
Lessons on how the recovery plays out are being drawn from Asia where the virus has been brought under control but the rebound has been mixed.
In South Korea, which flattened its infection curve months ago, the emergence of new virus clusters is casting a chill on shoppers.
China’s manufacturing activity climbed in June, as did other manufacturing gauges across the region, yet new orders continue to show weakness.
That worrisome outlook means businesses are navigating in the dark, according to Joerg Wuttke, president of the EU Chamber of Commerce in China, who expects the uncertainty to last for another couple of years.
“The recovery is not V, it is not W, it is looking like the top of a chainsaw,” he said. “Up and down and up and down and painful all the way.”
It also means that fast-expanding emerging economies won’t be the global growth engine they have been, with the World Bank predicting this group of countries will shrink 2.5% – their worst performance in data that starts in 1960. Latin America is now on the front lines of the virus.
A complete rebound to pre-crisis levels looks impossible until the virus is controlled – an outlook that’s especially true for sectors such as tourism, transport and entertainment where restrictions are expected to linger.
The hit to labor markets has been worse than initially estimated and will be impossible to repair in the second half of 2020 even under the most optimistic scenario, according to the International Labour Organization. It last week estimated that working hours in the second quarter were 14% lower than before the virus, equivalent to a loss of 400 million full-time positions.
Although U.S. companies added 4.8 million people to payrolls in June, only three in 10 jobs lost have been recovered and initial applications for unemployment benefits remain elevated. More than 2.8 million Americans lost their jobs for good in June.
“While a near-term mechanical bounce in economic activity in response to the easing of lockdown measures looks likely, we expect the subsequent climb to be long and arduous,” said Joachim Fels, global economic adviser at Pacific Investment Management Co.
There are other challenges too.
Record levels of debt will restrain how much additional support governments can roll out – on top of the $11 trillion fiscal stimulus already in train.
Governments are grappling with how to extend or terminate costly near-term measures to fund wages and keep companies alive, while at the same time gearing up for longer-term stimulus to drive a recovery.
That borrowing won’t come without side effects, such as keeping zombie companies going, according to Alicia Garcia Herrero, chief Asia Pacific economist with Natixis SA.
“If there is no clean-up of debt, going back to pre-crisis levels will take even longer,” said Garcia Herrero.
Meantime, central banks have slashed interest rates to new lows with some embracing negative borrowing costs. In a bid to cap market rates, multiple types of assets have been bought and policy makers continue to tweak their tool kit with hints of more innovation to come.
Morgan Stanley predicts $13 trillion in cumulative central bank balance-sheet expansion from the U.S., euro region, Japan and U.K. through the end of 2021.
Even with those steps, it’s too soon to conclude they will be enough, said Kazuo Momma, who used to be in charge of monetary policy at the Bank of Japan.
KPMG offers tips on how businesses can survive Covid-19 crisis
Jul 03. 2020Sasithorn Pongadisak, left, and Auaychai Sukawong
By THE NATION
KPMG, a professional services network, has launched a series of tips to help private enterprises in Thailand navigate the current climate and grow their business.
The tips are provided by KPMG Thailand’s experts, including Sasithorn Pongadisak, chief of private enterprises, advisory partner Surayos Chuepanich and tax partner Auaychai Sukawong.
The experts also provide tips on how family businesses and entrepreneurs pursuing mergers and acquisitions (M&A) or other investment deals minimise their risks.
They say businesses considering M&A must understand the process from start to finish so they know how to manage each step, from pre-deal, deal transaction to post-deal. They also need to have a clear idea of M&A objectives as well as an understand of the other party. Due diligence should also be conducted in terms of financial metrics, tax, as well as legal and operational steps.
Determining a purchase price is also one of the most important decisions to be made. Making the right preparations for M&A will also result in effective tax planning.
Since there were many changes in tax law over the past few years, entrepreneurs need to understand the principles underlying these changes.
KPMG is also planning to provide tips on managing human resources, system and processes to improve business.
Insiders sold shares as vaccine news hit the market
By The Washington Post · Christopher Rowland, Carolyn Y. Johnson · NATIONAL, BUSINESS, HEALTH, SCIENCE-ENVIRONMENT
As shares of biotech firm Moderna soared in May to record highs on news that its novel coronavirus vaccine showed promise in a clinical trial, the nation’s senior securities regulator was asked on CNBC about news reports that top executives had been selling their stock in the company.
Jay Clayton, chairman of the Securities and Exchange Commission, responded that companies should avoid even the appearance of impropriety. “Why would you want to even raise the question that you were doing something that was inappropriate?” he said.
Notwithstanding Clayton’s statement, there is little public evidence that company leaders slowed their stock selling. Now, corporate governance experts and some lawmakers say the trades could cast a shadow over Moderna, one of the biopharmaceutical industry’s most remarkable stories. The questions come as the 10-year-old company is leading the race in the United States for a coronavirus vaccine – a feat rooted in a government partnership formed years ago that could change the path of a disease afflicting the world.
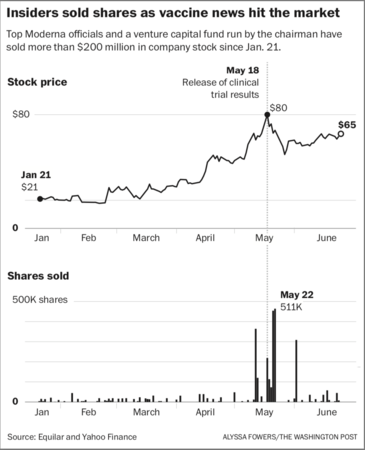
In total, seven corporate executives and board members as well as a venture capital fund run by Moderna’s board chairman collectively sold almost $101 million following Clayton’s comments. The trades were part of more than $200 million in sales by insiders since Moderna announced Jan. 21 that it was pursuing a vaccine in partnership with the National Institutes of Health. That’s according to an analysis of SEC filings that the national executive compensation research firm Equilar performed at the request of The Washington Post – the first such comprehensive examination of the company’s stock sales this year.
Insiders selling included Moderna Chief Executive Officer Stéphane Bancel, Chief Financial Officer Lorence Kim and Chief Medical Officer Tal Zaks. The trades were preprogrammed, according to the company’s required public disclosure filings, meaning they were made in accordance with a predetermined schedule or triggering event such as a share-price threshold. Moderna said it will not disclose any details of the preprogrammed trading rules for its executives.
On May 21 and 22, the co-founder and chairman of the company, Noubar Afeyan, reported selling $68 million worth of stock held by Flagship Pioneering, the venture capital fund he founded that is Moderna’s largest shareholder. Afeyan did not sell any of his personal stock holdings in Moderna, according to Flagship and public filings. These trades were not preprogrammed, according to the company’s public disclosures.
Moderna’s stock rose by 200 percent from January to June – as company news releases and news reports described early progress in its quest for a vaccine. In May, it was up as high as 300 percent after the release of the results of the clinical trial. The company made a public offering of stock on May 18 at the very peak of its share value.
Federal securities law requires officers, directors and large shareholders of publicly traded companies to report their trades in company stock to the SEC. Companies typically prohibit sales of stock by executives for 180 days after the initial public offering, specialists said.
The very first insider stock sales reported at Moderna occurred infrequently last fall, with the first in September 2019, 10 months after the company went public in a record-setting IPO in December 2018. Bancel began routinely selling shares starting in the fourth quarter of 2019 under his preprogrammed plan. The pace of selling picked up among Moderna’s other executives in 2020, according to the public filings.
“Executive sales are made under preplanned 10b5-1 plans, which are entered into during open trading windows in accordance with the company’s insider trading policy,’ ” said company spokesman Ray Jordan in an email. “As a matter of practice, Moderna does not intend to comment on any alleged or potential litigation or investigation; nor on purchases or sales by individual executives, investors or groups.”
Moderna did not make company officials available for interviews.
Bancel has a “long-term commitment to Moderna and to the development of the . . . technologies being developed by the company,” which he joined as its second employee nine years ago, Jordan added. “He has liquidated a small portion of his holdings each month through a planned 10b5-1 selling program. . . . Substantially all of his family’s assets remain invested in Moderna.”
The company has nearly 150 employees who operate under 10b5-1 plans, he added.
Flagship spokesman Gregory Kelley said in an email that the fund’s stock sales, which were not preprogrammed, “were made in accordance with [Moderna’s] policies and during an open trading window as determined by [Moderna’s] general counsel.”
Experts in securities law say the rules for preprogrammed stock trading plans are ambiguous enough that executives could gain unfair advantages, particularly when it comes to their control over the timing of release of market-moving data, and deserve scrutiny. The sales at Moderna in May raise potential concerns, the experts said.
“All of the activity in the days leading up to the announcement and the offering, and the days following the announcement, are ripe fodder for SEC investigation,” said Jacob Frenkel, a former top SEC investigator now in private practice as chair of government investigations and securities enforcement at the law firm Dickinson Wright. Frenkel said a likely subject of scrutiny would be what policies Moderna has for “blackouts” on executive trades during major news events and whether such policies were followed. The company said blackout dates are included in its insider trading policies, but the dates are not public.
The SEC said it would not comment. The agency typically does not publicly disclose whether it is investigating a company.
Nell Minow, an expert in corporate governance and vice chair at ValueEdge Advisors, said it is inadvisable for Moderna’s corporate insiders to be selling stock, particularly in the midst of major news about its leading product.
“It can send the market a signal that is opposite to all of the positive things that they are trying to communicate,” she said. “By definition, it is very concerning.
“Whether it is preprogrammed or not, it’s hard to believe that anybody who thought the company was going to be tremendously successful with this vaccine would be selling,” Minow said.
Harvey Pitt, a former SEC chairman who now heads Kalorama Partners, told CNN in May that the timing of the trades was “highly problematic” and that the SEC should review communications inside the company to find out “what was going on in people’s minds before all these transactions.”
Bloomberg in May estimated Bancel’s stake in the company as worth more than $2.2 billion, when measured at Moderna’s peak stock price. He has sold about $17 million worth of shares since Jan. 21, according to the Equilar analysis. Flagship’s 11 percent share of the company was worth $3.2 billion, Bloomberg said, and its sales of Moderna stock represented about 2 percent of that value. Given the large value of those holdings, the relatively small value of stock sales does not raise a major concern, said Jesse Fried, a Harvard Law School professor and expert on executive pay and insider trading.
“You don’t want to be exploiting a crisis to make money, but the truth is that any company that is going to sell the vaccine is going to be making money on the crisis,” Fried said, “and that’s great, because we want to incentivize people to wake up early in the morning and stay in their labs late at night coming up with something that will help us.”
But the Moderna sales are triggering political debate.
“Moderna executives used this opportunity to capitalize on the covid-19 crisis, and to add insult to injury, the value of their stocks increased based on the taxpayer-funded investment in the development of the vaccine,” Sen. Chris Van Hollen (D-Md) said in an email. Van Hollen is the sponsor of legislation that would require the SEC to revisit its rules for preprogrammed insider trades.
– – –
The enormous success of Moderna shows how pharmaceutical companies, often with help from the government, can achieve fantastic results even without delivering a product to market.
Its speedy response to the covid-19 pandemic was enabled by its vaccine technology based on messenger RNA, which carries genetic codes instructing human cells to produce what is known as a “spike protein” molecule. The spike protein, which was invented jointly by scientists at the National Institutes of Health and the University of Texas at Austin, triggers the immune system to create antibodies against the coronavirus. The technology allowed Moderna in March to become the first company to test a vaccine in a human, just 66 days after the coronavirus genetic code was published.
On May 18, Moderna announced partial clinical results from 45 human test subjects suggesting the vaccine was safe and triggered an immune response. It said it measured neutralizing antibodies in eight test subjects, which was seen as early evidence that its vaccine may work. The news release did not contain detailed data from the patients in the trial, and crucial test results on some subjects were not available at the time the release was issued.
The news drove the share price to a record peak of $80. On that day, the chief financial officer, Kim, who is leaving the company in a previously planned departure, sold $19.5 million in shares in preprogrammed trades, according to public filings. In all since Jan. 21, Kim sold $54 million in shares, according to the Equilar analysis. As of June 2, he still held $70 million worth of shares.
Minutes after the end of trading on May 18, Moderna announced it would issue $1.3 billion worth of new stock at $76 per share. The company said cash from the offering would be plowed into coronavirus vaccine manufacturing, including hiring 150 new production staff, as well as other company priorities. But as the stock dropped from its peak in subsequent days and weeks, plaintiff lawyers quickly announced that they would prepare class-action lawsuits, suggesting that the company’s news release overhyped the data.
Moderna said it “worked cooperatively” with NIH on the content of its news release and expects NIH to make detailed data from the Phase 1 trial public at a later date. NIH confirmed that it reviewed the data in the news release and said it was accurate.
The chain of events in the midst of the pandemic has generated negative attention for a company that is competing with much larger corporations – including Pfizer, Merck, Johnson & Johnson, and AstraZeneca – to develop the first coronavirus vaccine.
Unlike those companies, Moderna has no approved products and zero revenue stream from sales, according to the company’s disclosure reports. Fifteen drugs in its pipeline, ranging from virus vaccines to heart treatments and a cancer vaccine, are still in early or mid-stage development.
The company is built on the notion that cells inside the body can produce drugs and vaccines, if they are directed to do it by delivering the messenger RNA directly into the cells. Investors are wagering that Moderna’s technology will work for other medicines down the road, including more viral targets and a cancer vaccine, say drug industry specialists.
“If it works for this one virus, you can bet that it works for many, many others . . . and that kind of franchise will be incredibly valuable,” said Andrew W. Lo, the Charles E. and Susan T. Harris professor of finance at the MIT Sloan School of Management, who does not have holdings in Moderna but who has personal investments and financial ties to other biotechnology companies and biotech venture capital funds.
– – –
The Cambridge, Mass., company, founded in 2010, has attracted more than $5 billion in private-sector investment, according to company figures, including partnerships with Merck and AstraZeneca, multiple rounds of venture capital financing, and public stock offerings worth about $2.5 billion. The company has $483 million in government commitments to develop a coronavirus vaccine but said it has not tapped the money yet. Over its history, Moderna has received about $77 million in funding for various projects, the company said.
Moderna’s rapid response gave it a leg up in the markets. Older vaccines relied on deactivated or weakened virus, grown in chicken eggs, in a slow process. The new breed of RNA vaccines like Moderna’s can be designed on computers based on the genetic code of the virus and manufactured quickly. Pfizer also is working to develop an RNA-based coronavirus vaccine and began a Phase 1 trial in May.
Still, the delivery system needs to be proved safe and effective in large numbers of people.
“There is not a single drug approved with this technology. This is really the bet we are making, that all this is going to work,” said Otello Stampacchia, the founder and managing director of Omega Funds, a life sciences venture capital firm in Boston.
– – –
The foundation of the Moderna vaccine was laid years before a mysterious respiratory illness was reported in Wuhan, China. In 2012, another deadly coronavirus, Middle East respiratory syndrome, jumped from camels into humans. Barney Graham, the deputy director of the federal Vaccine Research Center, which is part of NIH, said in an interview that he wanted to use cutting-edge technologies that examined the precise shape of a virus – down to individual atoms – to design a vaccine against the threat.
But Graham and academic collaborators had to solve a problem. The target the scientists were interested in – the distinctive spiky protein on the virus surface – was unstable and tended to shape-shift.
Nianshuang Wang, a postdoctoral researcher then at Dartmouth, spent months trying to identify genetic mutations that would stabilize the shape-shifting spike protein, eventually finding a solution that worked in multiple coronaviruses. The paper, published in 2017, took persistence to publish – it was rejected five times.
“People generally at that time said, ‘Coronavirus is not a big concern,’ ” Wang said. “They didn’t get the idea that this can be a great technology in the future, to prevent another coronavirus pandemic.”
Graham was interested in using new technologies to speed up MERS vaccine development and in October 2017 began working with Moderna. The company’s technology could deliver messenger RNA to normal human cells that instructs them to churn out the spike protein with the crucial mutations. The presence of the spike protein in the body triggers the creation of antibodies against the virus. But with MERS sparking only small, occasional outbreaks, it wasn’t until January 2020 that the approach drew the world’s attention.
Even before anyone knew for certain what was causing a mysterious pneumonia in Wuhan, Graham and Bancel began talking about working together. Graham also called Wang’s boss, Jason McLellan, now at the University of Texas at Austin, to see if they could design a stabilized spike protein that could be used in a vaccine.
Researchers in Graham’s and McLellan’s labs designed the protein through computer modeling in a single weekend. Moderna scientists helped finalize the genetic sequence for the vaccine platform they had spent years developing. Within days, the company began producing the coronavirus vaccine in a factory south of Boston. The NIH and UT Austin teams filed a joint patent application on the mutated spike protein. Moderna has a “nonexclusive” license to the protein, which means that NIH can license it to other companies, NIH said.
In record time – 66 days after the genome of a never-before-seen virus was posted on an online server – the first doses were injected into human beings through a clinical trial supported by more than $700,000 in federal funding. Moderna announced the beginning of a Phase 2 trial in May and said its Phase 3 trial in 30,000 subjects is scheduled to start in July.
Bancel has said it may be known whether the vaccine works by Thanksgiving – a view echoed in an interview with Anthony Fauci, the director of the National Institute of Allergy and Infectious Diseases.
McLellan said that his laboratory has created a second version of the spike protein that is even more potent and that it has already signed an agreement with the Bill & Melinda Gates Foundation to ensure global access, which will enable companies with different technologies the ability to test and further develop potential covid-19 vaccines.
Two months after the first human subject was dosed with the Moderna vaccine, the public got its first glimpse of its potential effectiveness.
Before stock markets opened on May 18, Moderna issued a news release with positive but preliminary results of its Phase 1 safety trial. Eight trial subjects who received the vaccine had virus-fighting antibodies in their blood at levels similar or greater than people who have recovered from covid-19. Another 37 had promising immune responses, but tests were not available to see whether they had neutralizing antibodies.
As soon as markets opened on May 18, Moderna’s stock jumped. By the close of trading, it had risen more than 20 percent. But Moderna was criticized for releasing limited data by Fauci in an interview published by Stat on June 1.
“I didn’t like that. What we would have preferred to do, quite frankly, is to wait until we had the data from the entire Phase 1 – which I hear is quite similar to the data that they showed – and publish it in a reputable journal and show all the data,” he told Stat. “But the company, when they looked at the data, as all companies do, they said, wow, this is exciting. Let’s put out a news release.”
Two days later, Bancel offered an explanation for the company’s actions. A concern about leaks drove the decision to issue early information, he said in a June 3 video hosted by the Wall Street investment banking firm Jefferies that was publicly posted online.
Moderna had received preliminary data from NIH, which sponsored the Phase 1 trial, on May 14, Bancel said. The next day, Moncef Slaoui, a Moderna board member who had just left the company to go to the White House and assume leadership of President Trump’s Operation Warp Speed initiative to develop vaccines, expressed confidence in a Rose Garden news conference that a vaccine could be ready by the end of 2020. Slaoui said from the lectern that he had just seen positive data from a vaccine manufacturer. Slaoui did not identify the trial or manufacturer.
Moderna determined that too many people knew about the data, Bancel said, and that the company needed to publicly release limited results to level the playing field for all investors.
“I have no idea if tomorrow it’s going to be tweeted by somebody, it’s going to be mentioned at a conference, on TV,” he said. “That’s a risk our legal team said you cannot take.”
Jul 04. 2020If you keep your eyes open, you quickly pick up on those unwritten rules, says Janessa Cox-Irvin, global head of diversity and inclusion at AllianceBernstein. MUST CREDIT: Bloomberg photo by Amir Hamja
By Syndication Washington Post, Bloomberg · Michelle Davis · BUSINESS Here are 13 unwritten rules about being Black on Wall Street, according to people who’ve lived it:
1. Never forget: Despite all those promises about diversity, only about 1% of senior management is Black.
2. Be careful about pointing that out to the mostly White, mostly male trading desks.
3. Get used to hearing about the supposed lack of “qualified” Black applicants.
4. A 4.0 from Harvard isn’t enough. Assume some White Wall Streeters think Black colleagues are “diversity hires.”
5. Adopt a “White voice.”
6. Expect to hear complaints about bias training.
7. Put in long hours to combat stereotypes about “work ethic.”
8, Don’t ask for work assignments directly; expect to lose some to less-qualified White colleagues.
9. Hide anger or frustration.
10. Mind White colleagues’ personal space.
11. Don’t laugh too loudly.
12. Act as if all of this is normal.
13. Don’t talk about race.
Not everyone on Wall Street, Black or White, will agree with all those statements. These unwritten rules, and others like them, were gleaned from dozens of conversations with Black bankers and traders during the past month, as racism exploded into the national conversation.
We are expendable, says Dennis Creary, who runs a nonprofit called Blacks on Wall Street and sells software to big banks for Oracle. MUST CREDIT: Bloomberg photo by Amir Hamja
The interviews cut across ages, titles and experience, but all reflect the same sobering reality: Despite the years of talk and now town halls, Wall Street has mostly failed its people of color.
Few rank-and-file Black workers will say this on the record. Fewer still foresee wholesale change anytime soon in the financial industry, even as Black Lives Matter reaches into every corner of America.
True, promises have been made. Since the death of George Floyd prompted collective demands for action, Morgan Stanley and Wells Fargo & Co. have vowed to elevate Black executives. Goldman Sachs Group Inc. has required more bias training. JPMorgan Chase & Co. has expanded its mentoring programs. Bank of America Corp. has pledged money to fight inequality.
Yet the privileged realms of American finance still look much the way they did a decade ago, or even two or three decades ago.
The numbers tell one story: Today not a single chief executive officer of a major U.S. bank is Black, and only one of the more than 80 people included among the elite executive teams atop the six largest U.S. banks is Black. By some estimates, Black professionals account for 8% of the finance industry’s total – the same as 15 years ago. But their representation within trading and investment-banking divisions is much smaller.
At JPMorgan, Bank of America and Citigroup, the percentage of Black workers overall has been falling, not rising, in recent years. At JPMorgan, the nation’s largest bank, that number has dropped to 13% from 19% in a little over a decade.
But the figures are only part of the story.
In this moment of reckoning about race in America, firms have urged Black employees to talk openly about their experiences. Some are. But many worry this will only make their jobs and lives harder.
“There are certain things you might want to do, but you can’t,” says Dennis Creary, who runs a nonprofit called Blacks on Wall Street and sells software to big banks for Oracle. “The anger is there, but the fear of losing that job that you have worked for is also there.”
Creary adds, “We are expendable.”
As if to place an exclamation point on the moment, a Black executive who spent 16 years as the global head of diversity at Morgan Stanley is now suing the bank for racial discrimination. Marilyn Booker says she was fired for pushing for more and better training for Black financial advisers.
Morgan Stanley has strenuously rejected the allegations.
Just about every Black person you talk to in finance can tell you stories about subtle and not-so-subtle racism in the industry. Some have been complimented for being “articulate.” Others have been paid less than non-Black co-workers. Still others have been told they lack “technical” skills for a job, only to see it offered to a White colleague with similar credentials. Not long ago, in the Manhattan lobby of a major firm, a group of White bankers mistook a Black colleague for a security guard.
One Black banker recalled spending hours courting a White CEO, only to be excluded from the final pitch meeting. His boss told him a White banker would have a better chance of closing the deal.
Others say some managers are particularly reluctant to shake up lucrative sales and trading divisions. They say some people of color get passed over for internships or key trading roles out of concern they won’t fit in with the “culture” of White traders.
Janessa Cox-Irvin, global head of diversity and inclusion at AllianceBernstein, says she learned early on to measure her words and actions to fit in.
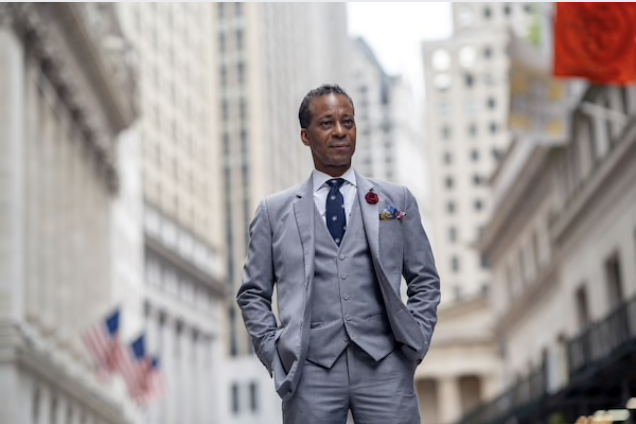
“If you keep your eyes open, you quickly pick up on those unwritten rules,” says Cox-Irvin, who has worked in the financial industry for 16 years.
Cox-Irvin says she’s careful not to play into White stereotypes of the “angry Black woman.” That means dialing back even seemingly small things, like showing excitement or gesturing with her hands.
Privately, some Black traders and bankers worry that the Black colleagues who speak out could end up hurting the entire Black community on Wall Street. They’ve expressed anxiety over the new focus on race.
“It’s Black people like ourselves that are saying, ‘We appreciate what you’re doing, but if there’s blowback, it’s going to affect the whole community, even those that didn’t speak up,'” says Lekan Lawal, a leveraged-finance banker at Goldman Sachs.
Others are quick to note that on Wall Street, as in the rest of America, the rage and grief that’s fueled Black Lives Matter isn’t universal.
As the fury over police brutality spilled into the streets, one Black trader’s White colleague told him he’d never felt safer around law enforcement.
Many Black employees practice the work-life equivalent of code-switching, tailoring their language and behavior to White surroundings.
Some have looked to connect by taking up skiing or golf. One trader at a major firm bought an album by Mumford & Sons, the English folk-rock band known for its twangy banjo picking, to have something to talk about with a White manager.
Black workers describe being bound by Wall Street’s unwritten rules even when they’re not on the official clock.
Creary, whose clients are banks, sees himself as an activist on race. But he goes incognito to Black Lives Matter protests to avoid offending his clients or his employer. “That fear of being filmed is still with me,” he says.
Many Black employees say White colleagues often question their qualifications, regardless of their credentials or performance, or view them as diversity hires.
“I’ve been in environments where I’m questioned,” says Roxann Cooke, who is in charge of JPMorgan’s bank-branch expansion efforts in New England and greater Pennsylvania. “When you’re the only one, it’s hard to be vulnerable because you’re trying to justify your position.”
Cooke is more optimistic than many that now is the time for change.
“I look at people speaking out and look at my organization coming together and saying we’re in this together – I feel hopeful that we’re going to continue to make progress,” Cooke says.
Others acknowledge that, even now, speaking openly about on race carries risks on Wall Street.
Lawal, the Goldman vice president, has been warned he’s too outspoken. “I’ve been told, ‘Lekan, it feels like you’re on a kamikaze mission, that you’re willing to sacrifice yourself.'”
He says he doesn’t care.
“There are people who have come before me,” Lawal says. “Colin Kaepernick was blackballed because he dared to complain that Black people were being killed. We won’t have a solution if the affected people continue to remain silent.”
Thai Airways International is speeding up formation of the business rehabilitation plan it will propose to the central bankruptcy court on August 17, said acting president Chansin Treenuchagron.
The Central Bankruptcy Court accepted the carrier’s petition for restructuring on May 27. The court will begin hearing the case on August 17.
The newly appointed acting president added that the plan will incorporate short-, middle- and long-term measures for rehabilitation, but declined to elaborate.
He said that THAI might have to consider seeking partners for its less competitive business units.
He added that THAI was trying to resolve its problems as soon as possible and needed collaboration from all involved parties to achieve the goal.
The panel in charge of the rehabilitation plan announced on June 30 that the airline would only shed 5 per cent of its 20,000 employees as part of the reorganisation effort.
Jul 04. 2020Payong Srivanich, president of Krungthai Bank
By The Nation
Bankers are calling on the central bank to provide more financial support to small businesses due to the lingering impact of the Covid-19 crisis.
Payong Srivanich, president of Krungthai Bank, voiced concerns about a slower recovery and called on the Bank of Thailand (BOT) to begin providing financial support to its corporate clients, especially small and medium-sized enterprises (SMEs).
He pointed out on Friday (July 3) that the central bank’s soft loan scheme, which allows SMEs to delay debt repayment for up to six months, comes to an end in October. He was referring to the Bt500 billion soft-loan scheme implemented by the central bank via commercial and state-run banks in April.
Despite this scheme, he said, there has not even been a partial economic recovery because businesses operating under the “new normal” are subject to far too many restrictions.
Payong added that he hopes extra measures will be in the pipeline soon so they can be enforced once this financial aid comes to an end. SMEs still need support, he argued.
Commercial banks have been trying to help SMEs by participating in the central bank’s soft loans scheme, he said, adding that bankers and the Bank of Thailand regularly discuss the issue of supporting borrowers who are suffering from the Covid-19 crisis.
He said the central bank has recently implemented Phase 2 of a measure to support retail borrowers, but this does not cover corporate clients.
Jul 03. 2020Pinya Nittayakasetwat, centre, General Manager, Gojek Thailand
By THE NATION
GET, the delivery and ride-hailing app, is rebranding as Gojek Thailand as its Indonesian parent company Gojek looks to merge Southeast Asia operations under one platform.
Under the rebrand, Thai users will be able to access Gojek services in Singapore, Indonesia and Vietnam. GoViet, the company’s brand in Vietnam, will also be updated to become Gojek.
“We are excited about this change, which demonstrates the strategic importance Gojek places on Thailand,” Pinya Nittayakasetwat, general manager of Gojek Thailand, said,
“Thailand is a highly competitive market, and the time is right for us to leverage Gojek’s strengths and scale to remain at the forefront.”
GET said it connects users in Bangkok to more than 50,000 drivers and more than 30,000 merchants, of which over 80 per cent are micro, small and medium enterprises.
Gojek boasts of being Southeast Asia’s leading technology group and a pioneer of the integrated Super App and ecosystem model, connecting users to over 2 million registered driver-partners, and 500,000 GoFood merchants across more than 200 cities in the region.
The firm says the new Gojek Thailand app will give users access to food delivery, ride-hailing, logistics and payment features.
By The Washington Post · David J. Lynch · NATIONAL, BUSINESS, CAREER-WORKPLACE ECON-ANALYSIS
Sales were stronger than expected when Macy’s reopened its first stores in early May, after a nearly seven-week coronavirus shutdown. But that initial surge soon fizzled, leaving the retailer’s brick-and-mortar business down more than one-third.
Some stores reopened in malls where restaurants and movie theaters remained closed, limiting foot traffic. Outlets in major cities suffered from the absence of foreign tourists. And recent coronavirus flare-ups across the South and West convinced executives they faced a grueling recovery that could take until 2022.
“The situation is really fluid. And it changes day by day,” Jeff Gennette, Macy’s chief executive, told investors this week on an earnings call.
The same could be said of the entire U.S. economy, which has defied the most pessimistic forecasts yet still faces an uncertain trek back to its former heights. With the unemployment rate at 11.1 percent, worse than at any point during the Great Recession, and output continuing to decline, the healing could go on for years.
Employers are rehiring workers faster than economists anticipated, at least as of mid-June when the latest Labor Department survey was taken. But more recent setbacks in the economic reopening, as the daily number of coronavirus cases topped 50,000 for the first time, have blackened the outlook.
“It’s going to be pretty slow going. The bottom line is this is all about public health, public health, public health,” said Narayana Kocherlakota, a former Federal Reserve Bank president. “This is absolutely a multiyear recovery.”
More than half of the country has now paused or reversed plans to reopen for business, according to Goldman Sachs. Almost four months after the first shutdowns, the health situation is getting worse, not better, in states such as Florida, Texas, Arizona and California. New national data on credit card spending, restaurant reservations and small-business hours show that the recovery from the recession that began in February may already be losing steam.
On Thursday, the Congressional Budget Office released its new forecast, calling for the economy to expand at an annual rate of 12.4 percent in the second half of the year, down from the 15.8 percent it projected in May. That represents unusually rapid growth, but it will follow a three-month period that is widely expected to be the worst in modern history.
The Atlanta Fed’s real-time model estimates that the economy shrank in the quarter that ended June 30 at a rate of 35 percent.
Still, the situation is not as bad as many economists feared. In March, as the economy plunged into the deepest recession in decades, many warned that the unemployment rate would hit 20 percent by summer.
On Thursday, in contrast, the Labor Department reported that the economy created 4.8 million jobs in June, shattering the record set in May. At the White House, President Trump took a victory lap, heralding the development as “spectacular . . . record setting . . . astonishing.”
The president boasted of the rising stock market, robust retail sales, and a revival of consumer confidence. With customary bravado, he took credit for the rebound while laying the blame elsewhere for the plummet that had preceded it.
“This is not just luck, what’s happening; this is a lot of talent,” Trump said. “All of this incredible news is the result of historic actions my administration has taken working with our partners in Congress to rescue the U.S. economy from a horrible event that was formed, took place in China, and came here.”
Indeed, Congress approved spending $3 trillion to rescue the economy while the Fed expanded its balance sheet by an additional $3 trillion to support lending to businesses, households and local governments.
Yet Democrats have charged that the president’s failure to combat the coronavirus by encouraging the use of masks and implementing a national testing program helped fuel the latest surge in cases.
The economy remains badly wounded. Nearly 19.3 million Americans are receiving unemployment benefits, almost three times the peak during the worst of the 2008-09 financial crisis and up from just 1.7 million in early March.
The situation is still so dire that the Fed for the first time in its 107-year history has created a program to buy the corporate bonds of blue-chip companies such as Apple, Walmart and AT&T to facilitate lending.
Trump’s salesmanship also risks opening a credibility gap between his rosy comments and reality. In a Fox Business interview on Wednesday, he again predicted a swift “V-shaped” recovery, an expectation that few economists outside his administration share. And he repeated his unfounded claim that the coronavirus will “just disappear” one day.
“We’re headed back in a very strong fashion with a ‘V,’ and I think we’re going to be very good with the coronavirus,” the president said. “I think that at some point that is going to sort of just disappear.”
Instead, the outlook is a start-and-stop recovery with the economy held hostage by a failure to contain the pandemic, some economists said. Adjusted for inflation, the economy will be smaller than it was at the end of 2019 until the middle of 2022, according to the CBO.
Megan Greene, an economist with Harvard University’s Kennedy School of Government, expects the unemployment rate to increase in July. Many small businesses that took advantage of a government loan program for small businesses may exhaust their borrowings next month, and enhanced unemployment insurance payments will also expire unless Congress acts.
“It’s a massive cash cliff for the economy,” she said.
Elsewhere, Apple, which had been among the first retailers to close during the initial pandemic shutdown, this week shuttered 77 stores in seven states for a second time. Credit and debit card spending, which had recovered steadily since mid-April, fell back in the week ending June 27, according to JP Morgan.
The investment bank cited findings from a panel of 30 million Chase cardholders and said the decline was “surprisingly widespread across states and demographic groups.”
Restaurant reservations also have lost ground in recent days. On July 1, bookings were down 64.7 percent from one year ago, having worsened from the 57 percent decline on June 27, according to the online dining service Open Table.
And Homebase, a provider of scheduling software, warned that small businesses were hitting a “reopening plateau.” After a rush to reopen in May, progress in cities such as Houston and Phoenix has stalled, the company said. Up to 20 percent of small businesses might not survive, it added.
“Going forward, my expectation is it will be more mixed,” said Nathan Sheets, chief economist at PGIM Fixed Income. “The biggest question is what happens with the virus. If we could get the virus out of the way, we have an economy that is itching to get back to normal.”
There is ample evidence that the pandemic retains its iron grip on the $21 trillion economy.
In Texas, United Auto Workers Local 276 last week asked General Motors to halt production at its Arlington assembly plant out of concern over the spreading virus, a request the automaker refused as unnecessary in light of company safety protocols. “Every day we are setting new records in the number of people who are testing positive in the Dallas-Fort Worth area,” the union said on its website.
In New York City, Mayor Bill de Blasio halted indefinitely plans to allow restaurants and bars to resume indoor dining.
In California, Gov. Gavin Newsom ordered mandatory business closures in 19 counties where the coronavirus is raging.
While the stock market gives off a scent of euphoria – the tech-heavy Nasdaq sits at a record high – bond investors are sending a different signal. The yield on the 10-year Treasury security sits at 0.67 percent, little different from where it traded in late March, and proof that traders anticipate anemic growth.
Continued cause for concern was evident in the 1.4 million Americans who filed for first-time unemployment benefits in the week ending June 27. That marked the 16th consecutive week that jobless claims have topped 1 million. Before March, the previous record had been 695,000 in 1982.
Companies in some of the states struggling amid the worst coronavirus outbreaks continue to let workers go, contrary to the president’s cheery forecast. In Florida, Levy Premium Foodservice, which handles concessions at sports facilities that are home to the NBA’s Miami Heat and Orlando Magic and Major League Baseball’s Tampa Bay Rays, notified the state of plans to lay off or reduce by more than 50 percent the hours worked for more than 1,400 employees.
It may be years before many Americans can count on complete recovery.
Over the past 70 years, the unemployment rate has declined from its recession peaks by 0.85 percentage points per year, according to a recent paper by Robert Hall, an economics professor at Stanford University, and Marianna Kudlyak, a research adviser at the Federal Reserve Bank of San Francisco.
The Fed expects the unemployment rate to be 9.3 percent at the end of this year. If the economy replays its previous performance, it would take nearly seven years for the economy to get back to February’s 3.5 percent jobless rate.
Experts advised investors to keep an eye on the US-China trade war and Covid-19 situation,as it could affect the baht and the Stock Exchange of Thailand (SET) Index next week.
The baht this week (June 29 to July 3) weakened to between Bt30.87 and Bt31.145, compared to the dollar due to strong US economic data.
US nonfarm payrolls in June rose more than analysts expected by 4.8 million jobs, while the US unemployment rate dropped for two consecutive months.
However, the US economy still faces slowdown risks because of the increasing number of new Covid-19 cases in the US.
A currency analyst at CIMB Thai Bank expected the baht next week to move between Bt30.80 and Bt31.30, advising investors to monitor the Covid-19 situation in the US, and conflict among countries, especially the US and China.
The SET Index on Friday (July 3) closed at 1,372.27, down 1.86 points or 0.14 per cent.
A stock analyst at Phillip Securities (Thailand) expected the index next week to fluctuate sideways between 1,340 and 1,400 due to mixed sentiments.
“For factors in foreign countries, the market is still under pressure from the US-China trade war and the second coronavirus wave in the US,” the analyst said. “For factors in Thailand, the market would benefit from the government’s tourism stimulus packages.”
The price of gold on Friday stood at US$1,774.56 per ounce, while the price in Thailand was Bt26,100 per baht weight.
A gold analyst at YLG Bullion International advised investors to sell some gold if the price rose over the resistance level between $1,779 and $1,790 per ounce.
“Meanwhile, we advise investors to buy gold for short-term speculation if the price does not drop below the resistance line between $1,747 and $1,758 per ounce,” the analyst said.

 A chain secures locked gates in front of a shuttered store in Madrid, Spain, on May 7. MUST CREDIT: Bloomberg photo by Paul Hanna
 Sasithorn Pongadisak, left, and Auaychai Sukawong
 If you keep your eyes open, you quickly pick up on those unwritten rules, says Janessa Cox-Irvin, global head of diversity and inclusion at AllianceBernstein. MUST CREDIT: Bloomberg photo by Amir Hamja
 Chansin Treenuchagron
 Payong Srivanich, president of Krungthai Bank
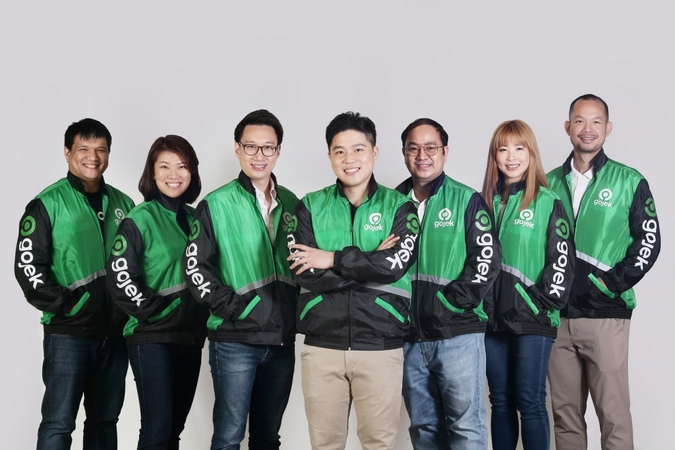 Pinya Nittayakasetwat, centre, General Manager, Gojek Thailand