The value of Thai electronics stocks has risen almost 20 per cent over the last month as European countries promote electric vehicles and the baht weakens, say analysts.
Among the beneficiaries is Delta Electronics (Thailand) (DELTA), whose share price has risen 14.68 per cent to Bt69.50.
Anekpong Putthapiban, assistant director at Asia Plus Securities, said electronic stocks gained positive sentiment from the baht falling to Bt31.2 against the dollar, European countries’ measures to promote use of electric vehicles, and moves around the world to ease disease controls.
“After many countries eased lockdown measures, investors may be thinking that the price of electronic stocks has bottomed out,” he said. “However, we advise people to avoid investing in these stocks because their price has reached maximum value, while these companies’ second-quarter performance is likely to drop.”
Meanwhile, a stock analyst at Capital Nomura Securities noted the price of Delta shares had risen by over 150 per cent from their low point in March this year, adding that the company’s performance is likely to recover faster than its competitors.
“We expect the company’s second-quarter net profit to be about Bt681 million, up 8 per cent quarter on quarter, but down 30 per cent year on year,” the analyst said.
“The company’s sales will increase by 4 per cent thanks to growth in telecommunications infrastructure and the European auto industry’s move to buy materials for electric vehicle manufacturing. Meanwhile, the company’s net profit in the second half of this year would increase in line with seasonal factors.”
The analyst added that Capital Nomura Securities has adjusted Delta’s net profit forecast from 16 per cent to 15 per cent in 2020 and from 12 per cent to 21 per cent in 2021.
“Aside from the recovery in automotive and telecommunication industries, the company also benefited from the weakening baht, so we expect Delta’s gross profit to increase from 20.5 per cent in 2019 to 21.2 per cent in 2020 and 22.4 per cent in 2021,” the analyst added.
The Finance Ministry has asked the Thai Credit Guarantee Corporation (TCG) to guarantee Bt30 billion in SME loans, but will set up a separate Bt50-billion fund to support small and medium-sized businesses hardest hit by Covid-19 and the economic contraction.
Finance Minister Uttama Savanayana said he has assigned the state-owned entity to extend guarantees for SME bank loans worth Bt30 billion.
“The pressing issue for SMEs now is lack of liquidity, and their next problem is how to use funding to upgrade themselves. We agreed to address their immediate problem first,” said Uttama after meeting with bankers and senior officials.
Once the existing fund is used up, then this further financial support may be extended, he added.
TCG president Rak Vorrakitpokatorn said guarantees for loans of Bt15 million-Bt20 million would be extended to eligible SMEs, down from previous programme’s Bt100-million limit. The Bt30-billion guarantee scheme will enable banks to lend up to Bt45 billion, benefitting 40,000 to 50,0000 SMEs, he added.
Meanwhile, Predee Daochai, Thai Bankers’ Association president, said that banks will look at businesses’ ability to repay debts before extending loans. He admitted that bad debt in the banking system was on the rise, but did not know by how much. The important thing was that the banking system was still functioning properly, he added.
Meanwhile, Uttama said the planned Bt50-billion SME support fund would be proposed to Cabinet in the next few weeks.
Thai SMEs have been hit hard by the Covid-19 fallout. The Bank of Thailand has rolled out a Bt500 billion programme of soft loans via commercial banks but only Bt100 billion in loan applications has so far been approved. Bankers wary of bad debts had asked the Finance Ministry to instruct the TCG to guarantee the loans.
By Syndication Washington Post, Bloomberg · Yakob Peterseil · BUSINESS, US-GLOBAL-MARKETS U.S. stocks traded mixed as investors considered whether a rising number of coronavirus cases will curb the global economic recovery. Treasuries jumped, with the five-year yield touching a record low.
Tech shares led declines, a dynamic that’s become increasingly rare as investors favored megacap companies seen as insulated from pandemic lockdowns. Most shares rose on the S&P 500 as the gauge fluctuated between small gains and losses after data showed record deaths in Florida, Texas and California from the virus. Gilead Sciences Inc. advanced after the company said its Remdesivir treatment cut covid-19 mortality risk by 62%. European shares edged higher.
With record deaths across America, as well as fears of a second wave in Asia, the spotlight is back on the spread of the coronavirus as investors head into the weekend. Fiscal and monetary stimulus buoyed markets thus far, but investors are looking for signals on what additional support may be in the works. Federal Reserve Bank of Dallas President Robert Kaplan, speaking on Fox Business, said he sees the need for more fiscal outlays.
“We’re going to see intermittent periods of shutdowns over the next year or so while we’re still grappling with this virus,” Erin Browne, a multi-asset portfolio manager at Pacific Investment Management Co., said on Bloomberg TV. “But I wouldn’t expect we’re likely to see a wholesale shutdown of the U.S. economy like we saw earlier this year.”
Elsewhere, China shares dropped as selling by state-backed funds signaled authorities wanted to slow the pace of gains following the Shanghai Composite’s eight-day winning run.
Oil traded below $40 a barrel in New York. In the U.K., yields on two- and five-year notes hovered near all-time lows amid speculation that the Bank of England may further ease monetary policy.
These are the main moves in markets:
Stocks:
– The S&P 500 Index was little changed as of 10:19 a.m. New York time.
– The Stoxx Europe 600 Index climbed 0.5%.
– The MSCI Asia Pacific Index dipped 1.1%.
– The MSCI Emerging Market Index sank 1.3%.
Currencies:
– The Bloomberg Dollar Spot Index fell 0.2%.
– The euro decreased 0.2% to $1.1309.
– The British pound rose 0.3% to $1.2642.
– The Japanese yen strengthened 0.4% to 106.76 per dollar.
Bonds:
– The yield on 10-year Treasuries fell two basis points to 0.60%.
– Germany’s 10-year yield declined two basis points to -0.48%.
– Britain’s 10-year yield declined two basis points to 0.14%.
Commodities
– West Texas Intermediate crude declined 0.1% to $39.58 a barrel.
Jul 10. 2020Prime Minister Prayut Chan-o-cha on Friday meets with his economic advisers, business leaders and some ministers to discuss extra measures to support small businesses and people adversely affected by the Covid-19 pandemic.
By The Nation
Prime Minister Prayut Chan-o-cha has changed the way he manages the economy by increasing collaboration with his economic advisers and business leaders.
Prayut postponed today’s meeting of the Council of Economic Ministers and instead held a meeting with his advisers, economic ministers and business leaders to discuss remedial and recovery plans after the Covid-19 outbreak.
Deputy Prime Minister Somkid Jatusripitak, who leads the Cabinet economics team, also attended today’s meeting.
Somkid downplayed the postponement of the economic ministers meeting, saying that economic management would run smoothly as he knows both the PM’s advisers and business leaders very well.
“It is better for the PM to have all the information, including from outsiders, before making a decision on economic measures,” said Somkid.
“PM Prayut is interested in how to support small and medium-sized enterprises and we have already talked with the Finance Ministry about measures to support SMEs, which will be submitted for Cabinet approval once the PM agrees,” said Somkid. He added that the Finance Ministry cannot solve many problems on its own and needed cooperation from other ministries run by different parties in the coalition, such as the Agriculture, Commerce and Labour ministries. The PM, as leader of the economic team, was in a good position to secure that cooperation “because coalition government needs to move together”, added Somkid.
Kobsak Pootrakool, secretary of the Council of Economic Ministers and the PM’s deputy secretary-general on political affairs, said the prime minister has changed the way he works under the “new normal” by listening more to his economic advisers. Previously, Prayut was merely updated by senior officials and talked with ministers.
Kobsak said the PM’s economic advisers and business leaders have proposed establishing a centre for economy recovery from the Covid-19 pandemic, similar to the government’s Centre for Covid-19 Situation Administration (CCSA) which has won success in containing the outbreak.
Meanwhile Paiboon Narintarangkul, chairman of the Federation of Thai Capital market Organisations, urged the government to make Thailand the hub for regional finance and capital markets. Others have proposed legal reform in order to make doing business in Thailand much easier.
Other business leaders attending today’s meeting were Kalin Sarasin, secretary-general of the Thai Chamber of Commerce. Suphachai Chearavanont, chairman of the Council of Digital Economy and Society, Ghanyapad Tantipipatpong, chairmen of the Thai National Shippers’ Council, Supant Mongkolsuthree, chairman of the Federation of Thai Industries and Predee Daochai, president of the Thai Bankers’ Association. Prayut’s economic advisers in attendance included Pailin Chuchottaworn, former deputy transport minister, Setthaput Suthiwart-Narueput, a member of the central bank’s Monetary Policy Committee, and Pirapan Salirathavibhaga.
The meeting came a day after the four ministers credited with running Thailand’s economy resigned from the ruling Palang Pracharat Party, though kept their seats in Cabinet. Prayut announced on Thursday he would reshuffle the Cabinet after talks with coalition parties. Prayut’s economic management has failed to impress observers since Thailand’s economy is currently the worst performer among Asean countries.
The Stock Exchange of Thailand (SET) Index dropped 15.31 points or 1.12 per cent closing at 1,350.50 today (July 10). Transactions, meanwhile, totalled at Bt64.196 billion with an index high of 1,363.28 and a low of 1,346.72.
During the morning session, a Krungsri Securities’ stock analyst said he expected the index to fall between 1,355 and 1,360 before rebounding due to uncertainty over the impact Covid-19 is having on economic recovery as the number of new cases is continuing to rise.
“In the US alone, there are more than 61,000 new Covid-19 cases daily, which has forced some states to impose lockdown measures again,” the analyst said.
“Plus, the SET Index is under pressure from the drop in the price of crude oil and the resignation of four Palang Pracharat Party executives.”
However, the analyst reckoned that the index would rebound from speculation in stocks of companies whose second-quarter performance will benefit from the weakening baht.
The top 10 stocks with the highest trade value today were STGT, AOT, CPALL, PTT, KCE, PTL, STA, PTTEP, EA and PRM.
As of 4.45pm, the price of crude oil dropped by US$0.94 or 2.37 per cent to $38.68 per barrel, while the price of gold rose by $9.10 or 0.50 per cent, to $1,812.90 per ounce.
Other indices in Asia were also on the slide:
Japan’s Nikkei Index closed at 22,290.81, down 238.48 points, or 1.06 per cent.
China’s Shanghai SE Composite Index closed at 3,383.32, down 67.27 points, or 1.95 per cent, while Shenzhen SE Component Index closed at 13,671.24, down 83.50 points, or 0.61 per cent.
Hong Kong’s Hang Seng Index closed at 25,727.41, down 482.75 points, or 1.84 per cent.
South Korea’s KOSPI Index closed at 2,150.25, down 17.65 points, or 0.81 per cent.
Taiwan’s TAIEX Index closed at 12,073.68, down 119.01 points, or 0.98 per cent.
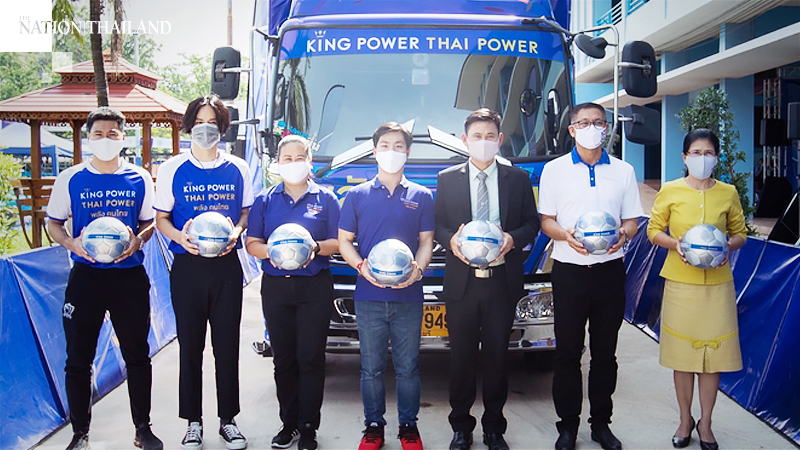
Apichet Srivaddhaprabha, assistant chief operating officer at King Power Group, fourth from left, presides over the launch of ‘Million Footballs, Million Power for Thai Youth’, a project in which footballs will be handed out to children in remote areas. The event was held at the Wat Nong Sala School in Nakhon Pathom province recently.
Also present were, from left, Tawatchai Kuammunkun from Fox Hunt football club, actor Jirayu La-Ongmanee, Krobkeaw Panyarachun from King Power, Min Prachubwan, deputy director of the Primary Education Service Nakhon Pathom Area Office 1, Bundit Laoaroon from the Nakhon Pathom Provincial Administrative Organisation and Chantana Phumma, director of the Wat Nong Sala School (Prachanukul).
Luxury mattress maker opens flagship store in new outlet complex
Jul 10. 2020
By The Nation
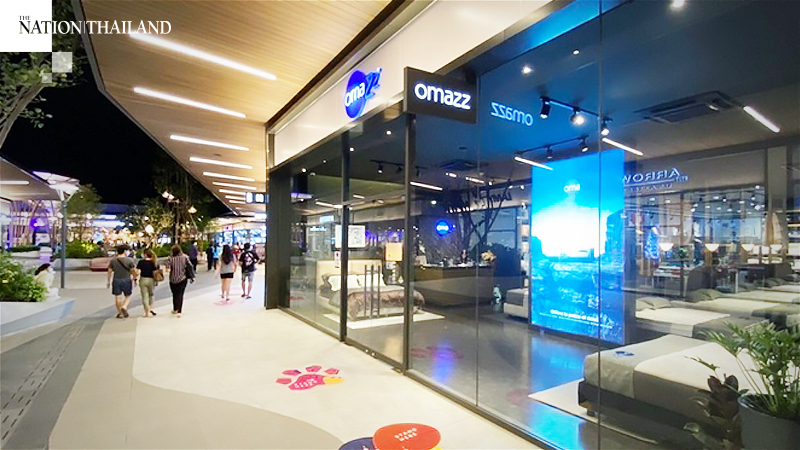
High-end luxury bedding manufacturer Omazz has opened a new flagship store at the Siam Premium Outlets Bangkok complex in Samut Prakan.
The 174-square-metre store, designed following a dark gothic minimalist style, features a full range of mattresses and bedding accessories made from natural materials.
A 60 per cent discount on selected products is also being offered at the new Omazz Gallery Store at Siam Premium Outlets.
CPF subsidiary to offer A+ rated debentures in August
Jul 10. 2020
By THE NATION
CPF (Thailand) (CPFTH), a subsidiary of Charoen Pokphand Foods (CPF), has signed up with the Securities and Exchange Commission (SEC) to offer unsubordinated and unsecured debentures to institutional investors and/or high-net-worth investors.
The offering comprises five series of debentures with tenors of four years and six months, seven years, 10 years, 12 years and 15 years, all of which have been assigned a credit rating of A+ from TRIS Rating.
CPFTH has appointed Krungthai Bank, Kasikornbank, Siam Commercial, Government Savings Bank, CIMBThai Bank, TMB Bank and Phatra Securities as joint lead arrangers for this batch of debentures, which should be offered by August 20.
Paisan Chirakitcharern, chief financial officer for CPF, said CPFTH’s business encompasses integrated operations in Thailand in relation to livestock, comprising swine, broiler and layer chickens as well as duck.
CPFTH’s operation covers three core livestock business lines, namely the production and sale of animal feed; breeding, commercial farming, and primary meat processing; and production of processed semi-cooked, fully-cooked and ready-to-eat meals, including outlets like CP Fresh Mart, Five Stars, Star Coffee and CP Kitchen. It also runs a Korean BBQ restaurant chain called “DakGalbi” and a seafood and international food buffet restaurant chain called “CP Hilai Harbour”.
Thai Otsuka joins hands with Nation Group in donating ‘Medical Food’
Jul 10. 2020
By THE NATION
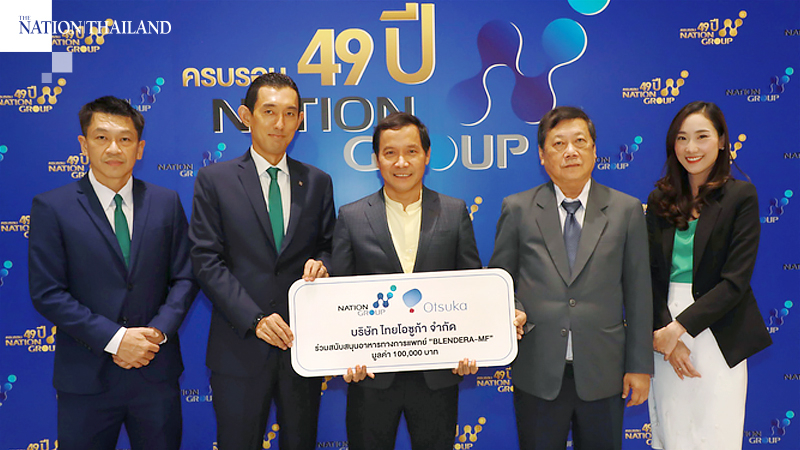
The chairman of Thai Otsuka Pharmaceutical Co Ltd, Thanan Suntayodom (4th from left), along with president Shinsuke Yuasa (2nd from left), director of BIV & CN Business Division Wattanachai Itsarasenarak (1st from left), and finance manager Thanasunun Suntayodom (5th from left) recently donated medical food ‘Blendera-MF” for those at risk of malnutrition to Yuttana Nualjaras, (3rd from left), editor and representative of Nation Group, at Interlink Tower in Bang Na district.
Uncertainty shrouds the housing market through 2020
Jul 10. 2020Clarksburg Town Center is a planned community of about 1,000 homes in Clarksburg, Md. When the pandemic seized the country, sellers retreated faster and in larger numbers than buyers, prompting the nationwide inventory of homes to dip precipitously. MUST CREDIT: Photo by Benjamin C Tankersley for The Washington Post.
By Special to The Washington Post · Dima Williams · BUSINESS, US-GLOBAL-MARKETS
Mending from the sudden sharp drop in activity due to the coronavirus crisis, real estate across the United States is heating up, rekindled by growing demand and insufficient supply.
The National Association of Realtors’ (NAR) pending home sales index, a future-looking indicator of completed sales based on signed contracts, posted a staggering comeback in May, the latest month for which data is available. The index spiked 44.3 percent, registering the highest month-over-month increase since its inception in 2001.
First-time home buyers Stuyve Pierrepont and his wife said they have seen this shift occur almost overnight.
The Pierreponts, who work in Washington, D.C. and previously rented in Northern Virginia, renewed their 18-month home search in early 2020. Prior to the viral outbreak, the couple looked at roughly a dozen homes. During the pandemic, they only saw four residences in person. But the couple wasn’t ready for the speed with which fellow home shoppers were scooping those houses off the market.
“It’s a seller’s market,” said Pierrepont, a finance professional who runs a blog about leading an environmentally conscious lifestyle. “We were back and forth on whether timing was right to buy a home, given everything that’s happening. The big surprise was that the markets we were considering didn’t slow down at all.”
The couple toured a house in Annapolis, Md., for example, which went under contract later the same day. “There were a couple of times when we saw places we really wanted, and they sold before we could act,” Pierrepont said. “We were really discouraged by that fact.”
Their real estate agent, Shane Hall of the Shane Hall Group, newly associated with Compass and formerly with TTR Sotheby’s, said in late June that Annapolis, which lies less than an hour east of the District of Columbia, had a single month of supply, meaning that if no new listings were to come on the market, all existing stock would be purchased in 30 days.
“That’s incredibly rare,” Hall said. “We just don’t have a ton of inventory. And we have a lot of demand.”
– – –
With the country’s economy tentatively reopening and shelter-in-place restrictions easing, housing experts forecast that home sales will rise through the summer. The biggest constraint is the number of listings, which are returning to the market only gingerly compared to the appetite for them.
The latter is in part whetted by historically low mortgage rates that are now hovering around 3 percent, nearly 2 percentage points below their level about a mere 18 months ago and where they are expected to remain this year. Annualized new mortgage applications have trended up for weeks.
“Today’s low mortgage rates are a true game changer,” said Ali Wolf, chief economist at Meyers Research, a new-home data and consulting firm. “As the economy reopens, it comes down to four words: Fear of missing out.”
Home buyers’ vigor has powered the national housing market, despite declines in mostly all economic indicators. For the most part, home showings – enhanced with hand sanitizer and face masks – have continued throughout the pandemic. The various services supporting the industry, from inspections to closings, have shifted to alternative modes such as the Internet, staying operational. And with the start of summer, home shoppers’ desire to make what is probably the largest financial commitment in their lives – in such an uncharted time – hasn’t seemed to slacken.
“If anything, that seems to be a ray of sunlight: We’re seeing buyers more active than expected,” said George Ratiu, senior economist with listing website Realtor.com. “Looking at our weekly inventory statistics, we’re seeing that total listings are down partly because new listings are down. But [also because] those homes that are on the market are clearly finding buyers quickly and that’s key.”
For instance, in the Tampa area in Florida, which has seen an influx of buyers from the Northeast because of the pandemic, active upscale inventory through June 23 was 26 percent lower than a year ago, said Jennifer Zales, luxury real estate agent with Coldwell Banker. At the same time, however, completed sales of homes above $1 million totaled 109, or three more than for the whole of June 2019, Zales said. Meanwhile, a little over 230 residences asking $1 million and up, including condos, townhouses and single-family houses, were under contract.
“We have a lot of pent-up demand from the spring season that did not happen,” Zales said. “I feel like somebody took my regular summer season, which is usually very regular, but dumps the whole spring season on top of the summer season. We’re extremely busy.”
This appears to be the latest recurring theme across the United States, even if the summer months traditionally are calmer with vacations and family activities stealing the focus from buying or selling a house. Beyond the next couple of months, angst about the fall, when the uncertainty of the presidential election mixes with a still-wobbly economic outlook and fears of a second wave of coronavirus infections, still permeates forecasts.
– – –
When the pandemic seized the country, sellers retreated faster and in larger numbers than buyers, prompting the nationwide inventory of homes to dip precipitously. After somewhat recovering from an all-time low in April, new listings remained about 22 percent below their level from a year ago in May, according to real estate brokerage Redfin.
This has not only exacerbated the chronic shortage of homes for sale, it has done so during the months when sellers are typically most engaged. A forecast by Realtor.com indicated the loss of spring inventory would translate to 15 percent fewer sales of existing homes in 2020.
“I think people are prepared to stay in their houses longer,” said Hall. “That was already a trend that’s been going on for the last five to 10 years.”
Despite a market tipped in their favor, sellers, especially those who still live in their residences, remain reluctant about letting strangers in. Increasing coronavirus infection rates in some states might strengthen this disinclination.
Moreover, home sellers are often also shoppers. Those not pressed to move might be loath to search for their next home amid tight inventory and rising competition. “It is now amazing to sell,” said Hall. “It is not amazing to buy.”
Yet Katie Day, a Houston-based real estate agent with Coldwell Banker, said she expects more homeowners to enter the market later this year to finally chase the housing aesthetics the pandemic has advanced as priorities.
“Probably toward the latter part of this year and into 2021, we will see more preference changes with people wanting to have a bigger home or wanting additional amenities in their house,” Day said.
Day’s remarks align with Realtor.com’s projection of a gradual increase of new listings through August before their numbers again hit the “historical trend” from September through December, when fewer homeowners generally decide to sell.
– – –
Because of the restricted supply of existing homes for sale, some buyers have flocked to new construction, especially single-family houses that, unlike their pre-owned counterparts that have been occupied, pose less risk associated with the coronavirus – and are more customizable.
Sales of newly built houses rose nearly 13 percent year-over-year in May, growing at a rate for that month not seen in more than a decade, according to the Census Bureau.
“There are just so few homes on the market today compared to last year, and last year already had historically low inventory levels,” said Wolf. “So, builders have been capturing market share left and right, selling homes at record May levels.”
This positive dynamic, though, might not alleviate the overall shortage of inventory. For years, builders have strained to build homes fast enough to meet demand. And, Wolf said, many of them have already sold their standing inventory in 2020. The Census Bureau’s data shows that most contracts in May were inked for houses under construction.
Meanwhile, new permits and housing starts in May continued to lag year-over-year, which could reflect builders’ sustained struggles in filling construction jobs and acquiring materials.
“The home supply shortage as the economy opens up is going to be even more severe,” Wolf said, “unless we all of a sudden see more existing homeowners put their homes on the market.”
– – –
The pronounced seller’s market has buoyed home values, contrary to early expectations of deflated prices resulting from a coronavirus-chilled real estate industry.
“We’re going to have this really surprising situation where, even though demand has certainly been impacted by the much weaker job market, supply has fallen even more,” said Mike Fratantoni, chief economist of the Mortgage Bankers Association. “Prices, as a result, are going up at the time that we’re in, in this very deep crisis.”
In May, the median price for all existing home types notched up 2.3 percent to $284,600, marking 99 straight months of yearly gains, the NAR reported. According to Realtor.com, in the third week of June, median asking prices grew at an annual rate of 5.6 percent, surpassing their pre-coronavirus pace.
“The increase in prices is fairly universal across most markets,” said Ratiu.
But not all cities have experienced price spikes.
A viral hot spot for months, New York City, for instance, saw the median sale price in its spiffiest borough, Manhattan, decrease about 18 percent in the second quarter, the largest annual slump in a decade, according to a joint report by real estate brokerage Douglas Elliman and real estate appraisal and consulting firm Miller Samuel.
In fact, median asking prices in May fell in all five boroughs, with the highest drop approximately 5 percent in Manhattan, according to Realtor.com.
The deflated home values rest on the backdrop of record low sales, which were a mere half of their year-ago number of 2,730. This is the most pronounced decline in 30 years of record-keeping.
The real estate industry in the city, though, only formally reopened in the second half of June with agents optimistic about a slow but steady recovery and even a silver lining for some home shoppers.
“For people who have been trying to move to Manhattan for a while and felt it’s so expensive, there’s some opportunity now for them to buy something they can afford,” said broker Lisa Lippman with Brown Harris Stevens.
– – –
Betsey Rider, who works in luxury goods sales and lives in Annapolis, and her husband, who is retiring this December, readied to sell their four-bedroom house, rebuilt a decade ago, later this year so they could move to a warmer climate.
But in the early days of the pandemic outbreak, three homes in their neighborhood of about 250 residences came on the market – and didn’t stay long.
“They sold within days,” Rider said. “I was shocked by that. At first, I found it really interesting that people were still house hunting.”
To tap the current demand and to evade any uncertainties down the road, the Riders decided to list the property. In early May they met with Hall, the Annapolis-based real estate agent, on a Saturday to discuss selling. The next day, having already tapped his industry network, Hall called to say that there were buyers from Texas interested in the home. That Monday, after a day of cleaning, the Riders showed their still-unlisted residence via a video phone call.
The offer followed quickly, a little under the $850,000 the Riders were going to ask. They accepted.
“We were happy with the price and the fact that we never had to list the house and go through all of [that process],” Betsey Rider said. “There were a few things that we were going to do prior to putting the house on the market that we ended up not having to do.”
The sale was completed in late June, after the Riders had already settled in a temporary rental before moving South.
According to the NAR, nearly 60 percent of the homes sold in May found new owners in less than a month. While Realtor.com reported slightly longer lead times, the company anticipates those spans to shrink as home buyers pick up the pace of making offers in competitive markets.
The Pierreponts, the first-time house hunters in the Washington area, experienced that quick tempo first-hand. After several homes they liked vanished to other fast-to-act shoppers, the couple in early June made a successful offer on a house in Deale, Md., about 30 miles east of the District, that had been for sale for a week. Asking $610,000, the residence sits on 1.7 acres and features a chicken coop, enough for the micro garden and farm the couple had dreamed of. The Pierreponts planned to close on the property on Saturday.
“We will still be able to work in Washington, D.C., and follow a career path,” Pierrepont said. “It gave us the best of both worlds in that sense. A longer commute is a small price to pay for having more usable land.”
– – –
The Pierreponts are among the many buyers who are leaving cities for the suburbs, secondary metropolitan and rural areas. While this exodus underlines Americans’ search for privacy amid the health crisis, it is in large part enabled by the rapid adoption of work-from-home arrangements that a number of companies have said would last beyond the pandemic.
“I believe that this is a permanent change,” said Lawrence Yun, chief economist with the NAR, about the movement to the suburbs and away from densely populated hubs.
Redfin found that a record 27 percent of searchers on its website in April and May looked to relocate, mainly to small towns from large cities.
For instance, New Yorkers have flocked to Florida and Southern California, where properties are generally larger and cheaper. Yet even local buyers in these states are searching for bigger, more remote homes.
“Even though Los Angeles is not a dense city compared to the vertical city that is New York, our local wealthy people are trying to get out to Laguna, Santa Barbara, Malibu, even Palm Springs,” said Ernie Carswell, luxury real estate agent with Douglas Elliman. “They’re buying beach homes. They’re moving farther from our populated areas.”
Cities such as Austin, Indianapolis and Des Moines are welcoming out-of-state home shoppers. Even second-home enclaves and resort towns like Aspen, Colo., are experiencing heightened demand.
“What we are seeing now is a huge uptick [in interest] in properties that are more rural and away from Aspen,” said Raifie Bass, real estate agent with Douglas Elliman. “So a farm or a ranch or a gentleman’s ranch properties that have a little bit more space. That market is stronger than it’s ever been. We’re seeing full-price offers on properties that have been on the market for a long time.”
Suburban and small-town markets are typically cheaper, but Ratiu said the ballooning interest in them would likely push prices up.
– – –
While the U.S. housing market is entering an invigorated summer season, characterized by low mortgage rates, rising home values and steep competition among home shoppers, uncertainty still shrouds the outlook for late 2020.
Even if some predictions point to a V-shaped coronavirus recovery, some forecasts, including Realtor.com’s, say the rebound would actually look like a W. Home selling and purchasing naturally slow down during the colder months, but factors such as a rise in new coronavirus cases and prolonged unemployment would exacerbate any seasonal declines – and soften home values.
“One of my biggest concerns is a second outbreak of the coronavirus and a second lockdown, which will be completely demoralizing, create more economic damage and people will remain unemployed for much longer,” said Yun.

 Finance Minister Uttama Savanayana
 Prime Minister Prayut Chan-o-cha on Friday meets with his economic advisers, business leaders and some ministers to discuss extra measures to support small businesses and people adversely affected by the Covid-19 pandemic.


 A 60 per cent discount on selected products is also being offered at the new Omazz Gallery Store at Siam Premium Outlets.


 Clarksburg Town Center is a planned community of about 1,000 homes in Clarksburg, Md. When the pandemic seized the country, sellers retreated faster and in larger numbers than buyers, prompting the nationwide inventory of homes to dip precipitously. MUST CREDIT: Photo by Benjamin C Tankersley for The Washington Post.

