Jun 14. 2020A man tends to vegetables in a field as emissions rise from nearby cooling towers of a coal-fired power station in Tongling, China, on Jan. 16, 2019. MUST CREDIT: Bloomberg photo by Qilai Shen. Location: Tongling, China
By Syndication The Washington Post, Bloomberg · Will Wade, Jeremy Hodges, Stephen Stapczynski
While the coronavirus pandemic is accelerating the death of coal in developed nations, the dirtiest fossil fuel is alive and kicking in Asia.
Demand for electricity plunged — and with it the need for coal — as factories around the world sat dormant and people spent months at home. In the U.S. and Europe, that’s expected to accelerate the shift away from the fuel. But in Asia, which makes up three-fourths of global consumption, the appetite for coal is roaring back and expected to continue growing after briefly being tripped up by the virus.
Coal is caught between conflicting geographies — one where its demise is celebrated in favor of cleaner options, and another where the cheap fuel powers rapidly developing economies. At stake is a $200 billion industry at the crux of the global fight to rein in carbon emissions that are driving climate change.
“The future of coal depends on Asian demand, which is still growing, and is offsetting the decline from the rest of the world over the next decade,” said Shirley Zhang, an analyst at Wood Mackenzie Ltd.
The U.S. coal industry has been hit hardest. As power demand slumped, American utilities shut coal plants first, crimping domestic consumption of the fuel. While exports have propped up miners’ earnings in past years, falling global prices have made international shipments less profitable, for both thermal coal for power plants and the metallurgical variety used to make steel.
The U.S. is expected to burn about 454 million tons of coal this year, the U.S. Energy Information Administration said in May, lowering the forecast 15% from its January outlook. The agency has revised down its target for exports by 24% to 63 million tons.
“Coal has really taken it on the chin,” said Benjamin Nelson, an analyst with Moody’s Investors Service. He’s not expecting a rebound next year, and instead expects to see a slow recovery that prompts utilities to shift further away from the fuel. “The longer the economic malaise, the more likely it is that coal plants will get shut down.”
The story is similar in Europe, where the green transition is more advanced and coal prices in May slumped to the lowest level since 2016, when the industry was beset by a wave of bankruptcies. The U.K. hasn’t burned coal for power since April 9, the longest coal-free period since the country opened the world’s first coal-fired public power station in 1882.
The economics elsewhere in Europe don’t stack up either. Planned coal expansions have been scrapped in Poland and the Czech Republic, while Austria and Sweden have closed their last plants during the pandemic. Even in Germany, where the fuel remains entrenched, coal supplied about 20% of the power mix in the first five months of the year, compared to 31% in 2019.
Utilities in the U.S. and Europe may accelerate some plant retirements because of lower demand from Covid-19, according to Carlos Fernandez Alvarez, senior energy analyst at the Paris-based International Energy Agency. “But overall, in the medium term, I don’t see a big impact. When demand recovers, a great part of this will come back,” he said by phone.
Asia, however, is another story. The continent remains coal’s stronghold and is slated to buoy global demand for the next decade as consumption drops elsewhere. Asia’s share in total global coal demand will expand from about 77% now to around 81% by 2030, according to IHS Markit.
While global consumption by 2030 is forecast to rise slightly to 3.68 billion tons of oil equivalent, according to IHS Market, Asia’s share of that total will expand from about 77% now to around 81% over new decade.
For China, which burns and mines about half the world’s coal, the fuel is key to economic health. Coal mining and washing employs about 3.5 million people and provides abundant fuel for the world’s top energy consumer and second-biggest economy.
China may add as much as 130 gigawatts of coal-fired generating capacity over the next five years to reach a peak of about 1,200 gigawatts and will dominate the nation’s generation mix, Woodmac analyst Frank Yu said in a May 22 report.
Economic growth and stimulus is the government’s current priority, and with coal accounting for about 65% of the generation mix, it’s critical to keeping China’s electricity prices low, Yu said. The pandemic may even slow the country’s efforts to move away from the fuel, according to Kevin Tu, a non-resident fellow at Columbia University’s Center on Global Energy Policy.
“Against the backdrop of rising anxieties over economic growth and energy security among Chinese decision makers, upgrading China’s climate ambitions will be politically challenging,” Tu wrote in a June 4 report. “Diminishing coal’s role in China’s energy mix will be more difficult, with potential long-term detrimental impacts on global carbon emissions and prospects for China’s renewable development.”
In India, the government of Prime Minister Narendra Modi last month reinforced its commitment to coal as part of broader Covid-19 stimulus measures, including more than $6 billion on coal transport infrastructure and offering 50 mining blocks for auction. Meanwhile, the annual output target for state-owned Coal India Ltd., the world’s biggest miner of the fuel, was boosted 18% to 710 million tons, an ambitious target fueled by government expectations that power demand will rebound. And its 1 billion-ton target by 2024 remains intact.
Southeast Asian nations including Indonesia, Vietnam and the Philippines are also poised to boost global coal demand over the medium term, according to IEA’s Fernandez Alvarez.
While Covid-19 means that Asian demand for coal is likely to fall year-over-year in 2020, that won’t become a new trend, according to IHS Markit analyst James Stevenson.
“We had been expecting Asian growth in the long term, and we still expect that,” Stevenson said by phone. “It will just be building off a lower base for 2020 because of Covid-19. We will return to growth”
The Asian growth isn’t necessarily going to be replicated in Africa where abundant renewable resources have gone largely gone untapped. In Sub-Saharan Africa total power generation will almost double by the start of the next decade to feed the rapid economic and population growth, particularly in major cities.
Coal generation made up over 57% of the region’s power needs in 2019, that number will shrink to 30% by 2030 as countries in the region add more renewable technologies at a faster rate than they ever have, according to BloombergNEF forecasts.
The Tourism and Sports Ministry will table before the Cabinet on June 16 plans requiring a budget of Bt20 billion to boost the domestic tourism sector.
Minister Phiphat Ratchakitprakarn said that the proposals involve three tourism packages, which will be offered during July-October.
The packages aim to help three groups of businesses: tour guides, hoteliers and the airlines.
The first package is for medical personnel numbering some 1.2 million, as they are on the frontline in dealing with Covid-19 outbreak, such as village public health volunteers. They will be given the budget for study tours or seminars to be arranged by local tour guide operators. It entails a cost of Bt2.4 billion.
The second package is to help hotels totalling 5 million rooms.
Initially the government might subsidise 40 per cent of room tariff for travellers. Applicants must be aged 20 and above to be eligible for the subsidy. They will have to register via a mobile application to download the e-voucher to enjoy the room rate discount.
The third package aims at helping low-cost airlines.
The government will subsidise 40 per cent of airfare for travellers who will pay the balance 60 per cent.
Reversing course just two days after news reports sparked a social media backlash, Starbucks says it will now allow employees to wear T-shirts and accessories in support of Black Lives Matter.
“We see you. We hear you. Black Lives Matter. That is a fact and will never change,” the company said in a letter posted Friday. “This movement is a catalyst for change, and right now, it’s telling us a lot of things need to be addressed so we can make space to heal.”
Earlier this week, and first reported by BuzzFeed, the company turned down a request from baristas and other employees who wanted to show their support for the BLM movement. In a memo to its 250,000-member workforce, Diversity Officer Zing Shaw said “there are agitators who misconstrue the fundamental principles of the Black Lives Matter movement – and in certain circumstances, intentionally repurpose them to amplifying divisiveness.”
The decision sparked backlash on social media, including calls to boycott the company, and came just days after Starbucks had issued a “Black Lives Matter” statement of solidarity and committed $1 million to racial justice groups as protests broke out across the country following the death of George Floyd, a black man, in police custody.
On Friday, in a posting signed by Shaw, Chief Operating Officer Roz Brewer and Executive Vice President Rossann Williams, the company said it is producing T-shirts with “Black Lives Matter” and other slogans for staff in the United States and Canada to “demonstrate our allyship and show we stand together in unity.” Employees, which the company refers to as “partners,” will have the option to wear them while working.
A company spokeswoman declined to say what exactly prompted the reversal – whether it was two days of social media calls for boycotts against the coffee chain or the current unrest in Seattle, the company’s home base and where protests have led to an activist takeover of a four-block, police-free autonomous zone.
Hailey Glick, who has worked as a Starbucks barista in Raleigh, N.C., since September, said she learned of the initial denial of BLM attire through an unofficial employee Facebook group. She said she initially thought the company was simply applying its official dress code policy, which prohibits personal accessories that advocate for a political, religious or personal issue – until her co-workers pointed out that the company sends employees shirts, cups and other merchandise to wear while on the clock during Pride Month.
“If we can stand up for LGBTQ rights, why can’t we stand up for black lives and people of color?” she said.
Glick’s manager knew she attended protests in Raleigh and was supportive, she said, but that might not be the case at stores in other cities.
“I was very pleased with the reversal of the decision, and I think it’s the right move. The only thing that I think makes me hesitate and probably makes the company hesitate too is how and where we draw the line,” Glick said. “What’s to stop someone wearing a MAGA hat or a MAGA shirt or a MAGA pin? I think what it ultimately comes down to is our values as a company.”
Bryant Simon, a historian at Temple University who wrote a book about Starbucks and American culture in 2009, said the company’s initial position was a “particular Starbucks dance.” The reversal, he said, came as a surprise.
“Lots of mass companies with a really big audience don’t want to have a public political statement and alienate their audience,” he said. “They can’t be Ben & Jerry’s. They’re just too big of a company for that. Their audience is too big, their investments are too big, their stores are in too many places for them to make a statement as strong as Ben & Jerry’s did.”
What’s tricky about Starbucks, Simon said, is that it markets its “third place” for customers (after home and work) without embracing the political discussion that comes with public spheres. It’s not just about the coffee.
“A kind of political presence has always been part of Starbucks proposition, the idea that they could make a difference in the world,” he said. “You’re buying some kind of identity, and that identity has a politics to it, but that’s something that is kind of a slippery slope when you’re a mass company.”
It’s not the first time the company has been in the spotlight for racial issues. When a female employee at a Philadelphia Starbucks store called the police on two black men sitting inside in April 2018, protests and a legal battle with the city’s police department thrust the company into reckoning with racial bias on a larger corporate scale. The company closed more than 8,000 of its U.S. stores the following month for an afternoon of anti-bias training.
Christina Chang, a diversity and equity consultant in Seattle, said she often uses that case in her anti-bias workshops with predominantly white groups as an example of how institutionalized racism shows up in day-to-day life.
“In the midst of everything of that’s happened, they are still so flat-footed,” she said. “How is that possible? The reason it’s possible is that at the end of the day, you still don’t have diversity at the top. You still don’t have people of color with different experiences who will sit down with them and say, ‘Hey that’s not cool.'”
Simon said he thinks that the company’s quick reversal is a case study for how the broader American public has mostly changed its attitude toward the Black Lives Matter movement.
Responses to the company’s quick reversal has been nuanced, ranging from applause and returning customers, to those who have now pledged to buy their coffee elsewhere rather than be served by a barista in a Black Lives Matter shirt, to racial justice activists who feel the company’s response was disingenuous and too little, too late.
“In this moment, when everybody is waking up, and for Starbucks to do this . . . it’s unforgivable,” Chang said. “No, we do not stop boycotting Starbucks. . . . They have struck out.”
Starbucks suffered a $3 billion hit to revenue since the pandemic began sweeping across the United States in March, forcing the company to temporarily shutter half of its 8,000 company-owned U.S. stores for nearly two months.
Glick said that during that time, Starbucks sent employees surveys to fill out about how their communities were affect ed by the pandemic and what local organizations were working to address those needs, which resulted in company donations. She said she’s expecting to receive a similar survey in response to racial injustice protests and the Black Lives Matter movement.
But Chang isn’t hopeful that the company culture will change until its board, leadership and store management reflects the racial and gender diversity of the country.
“The only way it’s every going to change is if we actually have representation at the top,” she said. “Not tokenism, not, ‘Oh we hired a chief diversity officer’ so we’re done.”
By The Washington Post · Joshua Partlow, David A. Fahrenthold, Jonathan O’Connell · BUSINESS, POLITICS, US-GLOBAL-MARKETS
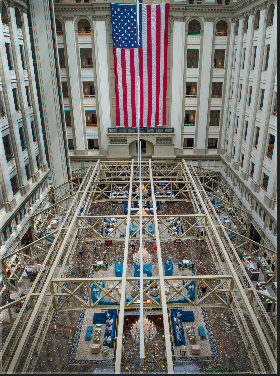
WASHINGTON — The head of President Donald Trump’s flagship hotel stood on Pennsylvania Avenue with face mask on and two thumbs up.
After three brutal months of empty hotel rooms and a skeleton staff, Mickael Damelincourt finally had something to celebrate: new sidewalk seating to safely welcome back Trump’s MAGA-loving customers. “Let’s get back to work,” Damelincourt tweeted on May 28.
By the next day, Trump was in his underground bunker, protesters swarmed downtown Washington cursing Trump’s name, and the hotel’s outdoor seating experiment was tabled.
The whiplash at Trump’s D.C. hotel is emblematic of the problems faced by his company, which was already suffering from a tarnished brand before the novel coronavirus hit. The fresh wave of political anger directed toward Trump complicates an already difficult recovery for the company.
Interviews with current and former Trump Organization employees and tenants, and emails obtained by The Washington Post, show the pandemic in particular has rattled operations at the company. As thousands of Trump’s hotel rooms empty, the company laid off or furloughed more than 2,800 employees and scoured for even the smallest savings. It eliminated flowers, chocolates and newspapers at its New York hotel and turned off lights in common areas in its Chicago hotel to save on electricity, according to letters that hotel management sent to investors.
“This was not just a step down,” Eric Danziger, the chief executive of Trump Hotels, told board members of Trump’s Chicago hotel on April 22, according to an account of his phone call obtained by The Post. “This was a steep dive.”
Trump’s business struggles present a potential conflict as he tries as president to manage a pandemic that has already claimed more than 110,000 American lives. The outbreak has devastated industries at the core of Trump’s business – travel, luxury tourism and hospitality – and the company’s fortunes largely depend on people’s willingness to travel and ability to gather in large groups.
Trump has handed day-to-day operations of the company to his eldest sons. Eric Trump did not respond to multiple requests for comment before this story’s publication. After this story published Friday, he tweeted that the company “had one of the BEST years in the HISTORY of the Organization in 2019” and that the details would be available in the president’s personal financial disclosure, likely to be made public later this month. He accused The Post of trying to harass the president and the company. “We have very little debt, tremendous cash flow & some of the greatest properties on earth, which have never been better, & are winning every accolade & award.”
The damage of the past months appears extensive. Out of Trump’s five top-earning hotels and resorts, four of them – in Miami, Las Vegas, Scotland and Ireland – shut down in March and remained closed through May. An analysis by The Post of Trump Organization revenue, based on Trump’s latest public financial disclosure, which covers 2018, indicate Trump probably lost out on tens of millions of dollars in revenue over the past three months.
– – –
Even before the pandemic, Trump’s polarizing presidency had sapped revenue from his business. At least two of Trump’s U.S. hotels – in Chicago and Miami – had reported sharp declines in business after Trump entered politics. The company’s hotel in Washington is now up for sale.
More recently, protesters have denounced Trump outside his New York, Washington and California properties, hurling invectives at these physical symbols of his presidency. At Trump’s golf course in Jupiter, Fla., the 18-year-old son of a former Republican congressman was arrested for spray-painting “B.L.M.” – an abbreviation for Black Lives Matter – on the entrance sign.
But along with the rest of the country, the Trump Organization has begun opening back up. Members can visit Mar-a-Lago, but only the beach club. Golfers can step out onto Trump’s course along the Potomac River and some, like him, even do so without a mask.
Eric Trump tweeted Wednesday that Trump’s Doral resort in Florida – the company’s highest-earning hotel – will be reopening next week. President Trump quickly chimed in on Twitter about this financial burden: “And the Trump family didn’t ask the Federal government for money to carry this and many other very expensive to carry properties!”
Because it is owned by the president, the Trump Organization was excluded from portions of federal relief funding.
One former Trump Organization executive said the company should get out of the hotel business, which accounts for about a third of company revenue.
“They have too many rooms to fill in a market where demand has suffered,” the former executive said on the condition of anonymity to discuss the company’s private financial situation. “He is too divisive a character in Chicago and NYC. In any market one wants to be neutral – he leaves many potential guests bitter and hostile.”
The picture is not all dire. The Trump Organization receives licensing and management fees for some Trump-branded properties that are owned by others; and there is no indication those fees have been disrupted. The company so far appears to have met its financial obligations even while seeking relief from creditors.
In late March, Trump’s golf club in Pine Hill, N.J. – which pays a monthly fee of $20,833 to use town-owned land – told the town it “may not be in a position to make [the payment] for a minimum of 120 days,” according to an email obtained via public-records request. But the next day, the club reversed itself and paid the fee, other emails said.
Some former employees expect the company to weather the current difficulties because Trump owns an array of major real estate assets and has fans to patronize his properties.
“I think he’s going to be fine,” said one former Trump employee who spoke on the condition of anonymity to discuss a former boss. “If you own all these things outright, it’s going to be a lot easier to get through it.”
And yet, the current crisis is now affecting even the strongest parts of the Trump business portfolio. The office buildings in New York and California that Trump owns wholly or in part are considered more insulated from politics than his hotels and clubs because they are leased to corporate tenants, and some buildings don’t use Trump’s name.
One of the tenants in Trump-owned buildings that is almost certainly asking to pay less is Starbucks, which wrote to its thousands of landlords May 5 asking for a year’s worth of reduced rent beginning June 1. The coffee chain rents space at Trump Tower in New York and at Trump’s D.C. hotel. In Washington, Starbucks pays Trump $14,118 per month, increasing to $15,787 a month in 2023, according to Trump Organization documents obtained by The Post.
“We are having ongoing conversations with our landlords in various markets regarding what may be commercially reasonable lease concessions in the current environment,” Starbucks Chief Financial Officer Pat Grismer told investors in April. Starbucks spokespeople didn’t respond to multiple requests for comment about rent negotiations at the Trump properties.
Other Trump tenants are now facing their own difficulties.
A massive Italian restaurant had been scheduled to open later this summer on the ground floor of a Wall Street skyscraper owned by Trump. But instead, as the coronavirus spreads, Nero.lab’s Italian Food Zone will probably have to adjust its initial concept – an 18,000-square-foot food hall where diners were to share communal tables and wait in lines for gelato and espresso. The Rome-based company’s chief executive, Alfredo Polizzi, remains optimistic about future prospects at 40 Wall Street. But he knows the restaurant won’t open until next year.
“We surely would’ve liked to do it sooner,” Polizzi said in an interview. “But given the situation, I don’t feel that would be wise.”
Another tenant at 40 Wall Street is Neapolitan Express, which operates pizza restaurants and food trucks in New York. The company has rented space in the building since 2015, said owner Max Crespo.
Crespo’s business has cratered – revenue dropped 27 percent in March, 55 percent in April, and 90 percent in May – but he has so far retained all 45 of his employees while also donating thousands of free pizzas to medical personnel and first responders. Just as things were opening up last month, protests and looting again drove away customers. The 40 Wall Street building got boarded up and spray-painted with anti-Trump graffiti, Crespo said.
“Our city’s on its knees right now,” said Crespo, 47, a lifelong New Yorker. “This is the worst I’ve ever seen it.”
Crespo said the Trump Organization collected full rent the past three months but also that Trump Organization employees have been “good partners” who “said if we have any problems going forward they can work with us.”
He pays the Trump Organization more than $20,000 per month but hopes to renegotiate and expects many restaurants across New York will not be able to continue operating at current rents.
“Obviously, I’m going to go and ask for a reduction in rent,” he said. “I’m sure they would work with us.”
Trump’s business is uniquely positioned to suffer from this pandemic. The luxury tourism and leisure sector that the Trump Organization inhabits has been devastated over the past two months as travel plummeted, international borders closed, and events and conferences evaporated.
Even when stay-at-home orders end and more people return to work, hotel operators and office building owners face tremendous uncertainty about how their businesses will recover. Hotels in the United States lost 82 percent of their business for the month of April compared with last year, according to hotel data analysis firm STR. Luxury hotels saw their businesses wiped out almost completely, losing 96.6 percent of their business in April after taking in just $60 million in revenue nationwide.
Analysts also expect the hotel industry to be one of the last sectors to recover given people’s aversion to travel during the pandemic.
Hotel experts predict the corporate meetings-and-events sector will be particularly slow to recover.
“I have no idea what corporate group [travel] looks like in a six-foot world,” said Jan Freitag, a senior vice president at STR.
Buffets? Open bars? Networking events? he said.
“There is corporate group demand that likely will not come back for four or five years,” he said.
This has meant layoffs on a large scale for Trump’s employees, with the steepest cuts at the hotels. Twelve Trump Organization properties in the United States and Canada laid off or furloughed employees, including cooks, waiters, housekeepers and valets, according to local filings.
Some of the job losses will not be temporary: At Doral, the company initially furloughed 560 employees, then later said in a filing that 250 of those jobs would be permanent layoffs.
Danziger, the chief executive of Trump Hotels, said in his call that the company could begin shifting toward using more part-time employees, who are not entitled to health benefits.
Even before the pandemic, there were signs that Trump’s politics drove away some potential customers.
“The vibe I got was that half of the guests wouldn’t feel comfortable ever coming to a meeting there,” said a former employee at Trump’s D.C. hotel who was involved in booking conferences. Some hurdles can be overcome with good salesmanship, the former staffer said, but “this wasn’t overcome-able.”
The staffer, who spoke on the condition of anonymity to preserve relationships in the hotel industry, was laid off last year because of lack of business.
The pandemic eliminated months of events across Trump’s company. At Doral, at least 10 events this year have been canceled or postponed, according to the groups planning the events.
Trump’s Mar-a-Lago Club was forced to shut down in late March, missing the last month of Palm Beach’s traditional winter social season. The club reopened its poolside Beach Club in mid-May, but with restrictions: The number of diners was limited, congregating was prohibited, and the club warned that “social distancing will be enforced” even in the Jacuzzi.
The club said it would now stay open a month longer than usual, to the end of June. One member, who spoke on the condition of anonymity to discuss the private club, told The Post that he planned to stay away anyway.
At the D.C. hotel, the patio seating plan was scheduled to restart again Friday. A previous attempt for outdoor tables earlier in Trump’s presidency ended after pedestrians regularly insulted hotel guests and staff, former employees said.
The oil and gas conglomerate PTT Plc has plenty of ammunition to help it deal with business risks and boost its liquidity, the group’s new president and chief executive officer Auttapol Rerkpiboon said on Friday (June 12).
He said PTT is ready to issue debentures worth Bt64 billion, of which Bt44 billion will be direct debentures while the remainder will be bills of exchange (B/E). This move is to boost the company’s liquidity and refinance existing debt which is nearing its due date. He added that the debentures will be issued as and when the company sees fit.
Auttapol also said that PTT has to be well prepared despite its strong financial status and liquidity. The Covid-19 outbreak and the global oil price war were two factors that affected its financial performance in the first quarter.
However, the CEO believes the situation will get better in the second half of the year thanks to the gradual easing of lockdown measures in many countries. He also doesn’t expect the global oil-price war to intensify, like it did in March and April, which resulted in a steep decline in the global price of crude oil.
Auttapol estimates the crude oil price will range at US$40 per barrel this year.
He also said that the lifting of curfew in Thailand from June 15 will renew the demand for oil and will also benefit PTT’s retail of non-oil products. However, he expects the sale of jet fuel to suffer a sharp decline this year.
He went on to say that PTT’s main mission is to maintain its strength in core businesses as well as to initiate new businesses for growth.
As for the impact the pandemic has had on the global economy, PTT has adjusted its operations to cope with the crisis by executing a cost-control policy of “decrease-discard-defer” to cut down on unnecessary activities, collaborate within the group for value-chain optimisation in order to manage price risks, demand, supply and inventory, as well as maintaining financial strength and stability.
Auttapol is serving a four-year term as the 10th president and CEO of PTT since May 13 this year.
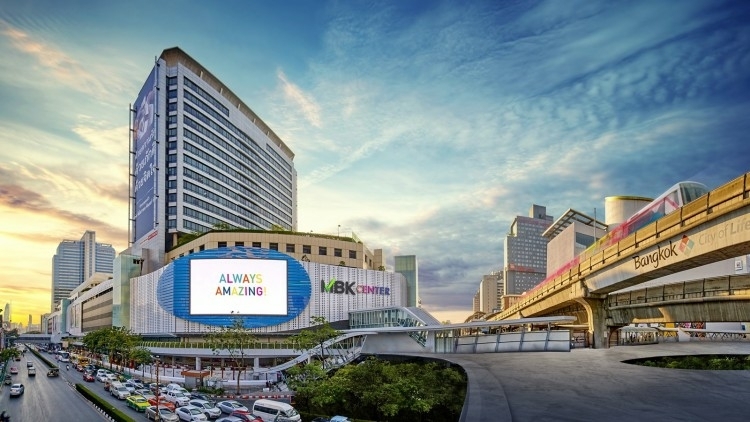
The operator of MBK Centre shopping mall is waiving rent on retail space in three of its halls until August this year.
Although the relaxation of disease control measures have allowed shopping centres to reopen, mall operators and traders are facing difficulties as the number of customers has fallen significantly.
MBK’s managing director Somphol Tripopnart said that the mall was allowing shop operators to use the ground floor’s Centre Hall, Phayathai Hall, and Patumwan Hall rent-free until August.
“The move is aimed at increasing outlets and reducing consumers’ expenses,” he said.
“Shops including Santa Barbara, John Langford, US Polo ASSN, and Luigi Batani are offering their products at discounted prices from June 15 to 28 this year,” he added.
By Bloomberg · David Goodman, Andrew Atkinson · WORLD, EUROPE
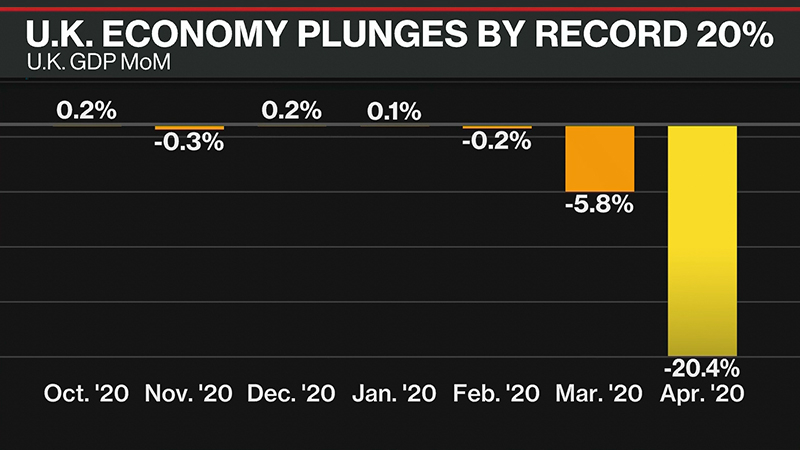
The U.K. economy shrank a record 20.4% in April as businesses and workers reeled under the lockdown designed to control the coronavirus pandemic.
The contraction means the nation has effectively seen almost 18 years of growth wiped out in two months. While a rebound is likely as businesses start to reopen, the grim figures will increase the pressure on the government and Bank of England to do more to support the recovery.
The hit to the economy rounds off a difficult week for Prime Minister Boris Johnson, who is facing mounting criticism from politicians and scientific advisers after they blamed his Conservative administration for making a series of grave mistakes since the beginning of the outbreak.
In addition to registering the highest death toll in Europe, the U.K. has also paid an heavy economic price. The OECD says the country could see one of the developed world’s deepest recessions in 2020, with output slumping more than 11% — the most for more than 300 years.
“April was the first month to be fully encompassed by the lockdown. But these figures are nevertheless shocking, and it goes without saying that this kind of fall in activity is virtually unprecedented, either in scale or speed,” James Smith, an economist at ING, wrote in a report.
Social-distancing rules and the prospect of a no-deal Brexit “all pose challenges to the U.K. economic recovery,” and will keep the pressure on the BOE to increase its bond-buying program when it meets next week, he said.
That view is shared by most economists, who expect purchases to be stepped up by at least 100 billion pounds. Bank of America Merrill Lynch economists said Friday they expect a package of measures in August, including cutting interest rates to 0%, making the terms of a lending program more generous and possibly implementing a weak form of yield curve control, which would keep bond-market rates around a certain, low, level.
More support is seen as vital as the U.K.’s outlook darkens. Unemployment is widely expected to reach rates not seen since the mid-1990s, with more than 7,500 job cuts being announced on Thursday alone as the lockdown hammers businesses from chemical manufacturers to airports. That’s despite massive government support that has left the taxpayer paying the wages of over 11 million people at a cost of 27 billion pounds ($34 billion) so far.
“We’ve always been in no doubt this was going to be a very serious public health crisis but also have big, big economic knock-on effects,” Prime Minister Boris Johnson said in a TV interview Friday. “We have been very badly hit by this.”
The damage in April was done by a 19% drop in the dominant services industry, where sectors such as air transport, travel agents and restaurants lost around 90% of their output. Manufacturing fell 24.3%, while construction plunged 40.1%. It means the economy was around 25% smaller in April than it was in February.
What Bloomberg Economists’ Say
“The U.K.’s death toll is one of the highest in the world and that could mean spending remains subdued, even as the lockdown is eased further. Thought of another way, it could be that demand acts as the ceiling on activity as the economy starts to recover, not supply,” Bloomberg senior U.K. economist Dan Hanson wrote.
“Unemployment, rising debt and business insolvencies will weigh on the recovery,” Ian Stewart, chief economist at Deloitte, said. “The economy is unlikely to return to pre-Covid levels of activity until 2022.”
Still, the pound was largely unperturbed by the plunge in output, which was expected by investors. It was up 0.1% at $1.2619 as of 12:00 p.m. London time on Friday.
Separate figures showed the trade deficit excluding volatile non-monetary gold and precious metals narrowed in April, with both exports and imports falling sharply as the pandemic disrupted shipment of cars, fuels, works of art and clothing.
By The Washington Post · Thomas Heath, Taylor Telford · BUSINESS, US-GLOBAL-MARKETS Stocks staged a bold finish on Friday, but it wasn’t enough to rescue markets from their worst weekly loss since March.
The three major U.S. indexes rose at least 1% to end a tumultuous week marked by new public health worries and dashed hopes for a swift economic recovery.
The Dow Jones industrial average bounced all over Friday, rising as much as 837 points before briefly sliding into negative territory. A late-session rally pushed it 477 points, or 1.9%, higher and settle at 25,605.54. The blue chips finished the week down 6.4% and off 11% for the year.
“It was a roller coaster of a week for the stock market,” said Kristina Hooper, chief global market strategist at Invesco. “The week began with stocks continuing their strong rally on excitement over reopening in the U.S.”
The Standard & Poor’s 500 index had an equally wild week, barely edging into positive territory for 2020 at Monday’s close. But the next three days were ugly, with steep losses in the broad market. The S&P 500 finished Friday at 3,041.31, a 39-point, or 1.3%, advance. The S&P lost 5% on the week and is down 6% for 2020.
The tech-heavy Nasdaq Composite jumped 1%, 96 points, on Friday to close at 9,588.81. The technology giants – Amazon, Facebook, Microsoft, Google-parent Alphabet and Apple – have kept Nasdaq above water for the year, elevating it 6.6%. It set three consecutive record highs this week and closed above 10,000 for the first time. The index is down 2.5% for the week. (Amazon founder and chief executive Jeff Bezos owns The Washington Post.)
Boeing, Dow Chemical and Raytheon Technologies paced the Dow upward on Friday. Nine of 11 stock market sectors were positive, with financial and real estate the big winners.
The week got off to a good start on momentum from a better-than-expected jobs report days earlier. The Dow, which had peaked at 29,551 in mid-February before going on to lose nearly a third of its value within weeks, had been on a steady climb. But by Thursday there was a sense the stock market had come back too far, too fast.
A spike in covid-19 cases and a sobering economic outlook from the Federal Reserve – which predicts unemployment will still be at 9.3% by year’s end – sparked a massive sell-off that sent the Standard & Poor’s 500 index skidding 5.9% and the tech-heavy Nasdaq Composite tumbling 5.3%. The Dow’s 1,861-point drubbing capped a three-day losing streak that erased 9% of its value.
“Stocks fell when Fed Chair Jay Powell threw cold water on optimism about a fast recovery for the American economy,” Hooper said. “The sell-off then picked up speed on concerns about a resurgence in infections. By the end of the week stocks rose modestly, sensing buying opportunities and recognizing that the Fed remains extremely accommodative.”
Even as much of the nation has reopened, the pandemic’s grip remains strong: the country surpassed 2 million coronavirus cases on Thursday, a staggering tally that far exceeds the number of infections reported in any other country. Eleven states reached their highest seven-day rolling averages of new cases on Thursday, according to data tracked by The Washington Post, suggesting a second wave could already be in motion.
The seven-day moving average of deaths has fallen steadily from its peak in April, but it has not halted as some White House officials had predicted.
President Donald Trump and his top economic aides fanned out Thursday to try to beat back the growing concern. They assailed the Fed’s projection that unemployment will remain elevated well into next year. The Trump administration also pushed back on the idea that it would allow the economy to shut down again in the face of rising cases, but Treasury Secretary Steven Mnuchin told reporters the administration is seriously considering a second round of stimulus payments.
Grim economic data poured in from around the globe this week, illustrating the depths of economic damage and indicating that the road to recovery will likely be rockier than many hoped. The United Kingdom reported its gross domestic product declined 20.4% in April – the largest drop on record; the Organization for Economic Development and Cooperation has warned the U.K. its economy will likely to be among the hardest hit, along with Spain and Italy.
Germany’s industrial production took its biggest hit ever in April, prompting some economists to call it the country’s worst month ever for the economy. The World Bank said the pandemic has created the biggest global recession since World War II and predicted GDP will contract 5.2% this year.
The past three months have been “a dizzying Space Mountain-like roller coaster for investors,” Wedbush Securities tech analyst Dan Ives said in comments emailed to The Post. “Yet, the stock market has come roaring back in a V shaped recovery.”
Consumer confidence also improved in May as many Americans got back to work, according to the survey results released Friday by the University of Michigan.
“The economy won’t come back on its own with just consumers emerging from the country’s three-month coronavirus pandemic lockdown,” Chris Rupkey, chief financial economist, wrote Friday in comments email to The Post. “The hope is that business confidence will return as well and investment spending will rebound to help power the economy forward once companies see that the consumer is back and is buying the goods and services they offer.”
The yield on the 10-year U.S. Treasury note ticked upward after a major drop Thursday as investors moved toward riskier ground. Bond yields rise as prices fall.
Oil prices saw their worst week in two months, with prices dropping on a report from the U.S. Energy Information Administration that demand may be slowing. Brent crude, the international benchmark, closed at $38.98 per barrel on Friday. West Texas Intermediate futures sold at $36.48.


 A man tends to vegetables in a field as emissions rise from nearby cooling towers of a coal-fired power station in Tongling, China, on Jan. 16, 2019. MUST CREDIT: Bloomberg photo by Qilai Shen. Location: Tongling, China
 PTT CEO Auttapol Rerkpiboon