Small firms still in dark on loan forgiveness as clock ticks #ศาสตร์เกษตรดินปุ๋ย

#ศาสตร์เกษตรดินปุ๋ย : ขอบคุณแหล่งข้อมูล : หนังสือพิมพ์ The Nation.

https://www.nationthailand.com/business/30387216?utm_source=category&utm_medium=internal_referral

Small firms still in dark on loan forgiveness as clock ticks

May 04. 2020
Closed businesses stand in the Bishop Arts District of Dallas on April 15. MUST CREDIT: Rebecca Smeyne/Bloomberg

Closed businesses stand in the Bishop Arts District of Dallas on April 15. MUST CREDIT: Rebecca Smeyne/Bloomberg
By Bloomberg · Mark Niquette · NATIONAL, BUSINESS, CAREER-WORKPLACE, RETAIL

Small businesses that struggled to get loans from a government pandemic relief program still don’t know how much they may have to repay after the government missed a deadline to give specific guidance.

The U.S. Small Business Administration was supposed to clarify by April 26 how loans it approved as part of the Trump administration’s multitrillion-dollar coronavirus stimulus package can be spent and still qualify to become grants.

Companies and lenders say they need more guidance on how to calculate the amount that’s eligible for forgiveness and what documentation is required to support the claims. That could leave small firms on the hook to repay loan proceeds they thought would be a grant. As a result, some business owners are holding onto the loans and may even return them, according to interviews with small business groups, lenders and borrowers.

The Paycheck Protection Program was designed as a lifeline for small firms, many of which were shuttered due to stay-at-home orders, have no revenue coming in, and may be forced to close for good. Time is short, since the funds must be spent within eight weeks after they’re received to qualify for forgiveness. Every day of uncertainty means making decisions is more difficult, the groups and business owners said.

“As soon as they got the money, they’re calling and saying, ‘OK, how do I spend this to make sure I get this forgiven, because I don’t want to mess this up,'” said Kimberly Rayer, a partner at Starfield & Smith in Pennsylvania, who advises lenders on SBA loan programs. “Borrowers are concerned, they would like to make sure that they don’t have to pay this money back.”

The uncertainty about how loans will be forgiven is just the latest stumbling block in the SBA’s chaotic effort to funnel about $670 billion to small firms across the country to counter the devastating effects of covid-19 on their operations. The initiative was intended to keep them afloat and keep employees on payrolls to be ready to reopen.

The initial round of $349 billion in funding ran out on April 16 in just 13 days after 1.66 million firms were approved for loans. The program relaunched April 27 with an additional $320 billion, and the SBA and Treasury Department reported on Sunday that 2.2 million loans totaling $175.7 billion from more than 5,400 lenders have been processed, with an average loan size of $79,000 – much lower than the $206,000 average in the first round. The totals, through May 1, mean less than half the additional funding remains available.

The program provides loans of as much as $10 million to small businesses affected by the outbreak. The law says borrowers don’t have to repay the loans if the money is spent on payroll plus mortgage interest, rent and utilities. An initial rule issued by SBA and Treasury said 75% of the proceeds must be spent on payroll and 25% on the approved expenses. The amount forgiven is reduced if owners cut jobs or wages, and any amount that’s not forgiven must be repaid at 1% interest in two years, with the first payment deferred for six months.

Business owners don’t have enough guidance about how they’re spending the money to ensure they’ll avoid having to repay it, said Holly Wade, director of research and policy analysis for the National Federation of Independent Business. Questions include whether expenses incurred during the eight weeks but paid later would qualify. They’d also like more flexibility about how the proceeds can be used and still qualify for forgiveness. Small business and industry groups are lobbying Congress and the Trump administration for changes.

“There’s just many questions where we don’t have an answer, and small business owners are concerned,” Wade said.

Congress said in the legislation creating the program that the SBA was to issue guidance and regulations for loan forgiveness “not later than 30 days after the date of enactment of this act,” which would have been April 26. Almost a week on, the agency hasn’t said when it will issue the guidance and didn’t comment for this report.

For more: Trump’s Rural Base Fared Better Than Coastal Cities in SBA Loans

The program was designed to have banks disburse loans to small businesses that SBA would guarantee, to get money into the hands of those in need as quickly as possible. Lenders can apply to have the agency reimburse them for the portions of loans that are forgiven, starting seven weeks after money is disbursed.

Lenders also want more guidance because they make the initial assessment about loan forgiveness, said Paul Merski of the Independent Community Bankers of America. The SBA and Treasury should produce a calculator to help lenders and borrowers determine loan forgiveness and simplify the process, he said.

The rollout of the small business relief program last month had numerous problems. SBA’s lending platform was quickly overwhelmed, and guidance to borrowers and banks – which has changed dozens of times since it launched April 3 – sowed confusion and caused banks to hold back on processing applications initially.

Large firms and national chains swooped in, picking up millions of dollars in loans and leaving many mom-and-pop businesses shut out. Almost 320 public companies received loans totaling $1.12 billion, according to data compiled by FactSquared.

After the Trump administration warned large firms with access to other capital about taking loans and Treasury Secretary Steven Mnuchin said all loans of more than $2 million would be reviewed for criminal liability, 29 companies had returned loans worth $183 million as of May 1, data show.

Texas hotelier Monty Bennett, a major donor to President Donald Trump whose companies are among the biggest known recipients of loans that total about $70 billion, according to regulatory filings, said Saturday he will return the money.

James Cummings, who runs 22 Great Clips franchises across North Carolina, said he received a loan for his hair salons toward the end of April, but is holding on to it until he gets more details on how the forgiveness will work. He’s hoping that the government will allow more flexibility in how he spends it.

Cummings said he needs to “be able to use this money when we reopen, or we’re literally going to have to pay it all back, every dime.”

The salon operator is among small business owners that are finding themselves caught in an additional bind: Even with a loan, they can’t pay their employees as much as the workers could get from unemployment benefits, but they can’t use more of the money to cover other expenses while waiting to reopen.

Many restaurants and other small business owners also say eight weeks of federal coronavirus relief won’t be enough, especially if they’re not ready to reopen during that time. Industry groups including the National Restaurant Association are seeking a number of changes, including an extension of the period when owners can use the loan and have it forgiven.

Advocates also want more flexibility to the rule on how the proceeds can be spent, but Mnuchin has defended the terms because the intent of the law was to keep workers employed.

Clara Osterhage, who owns hair salons in Ohio and other states, got her loan funds on April 26, but doesn’t know when she’ll be able to reopen and whether she can rehire workers. She said she needs more clarity about the rules and may end up having to return the money rather than having to repay with interest a two-year loan she can’t afford.

“It’s incredibly concerning,” Osterhage said. “I don’t know the rules of the game, and I have no control.”

The big keep getting bigger in the pandemic-rearranged economy #ศาสตร์เกษตรดินปุ๋ย

#ศาสตร์เกษตรดินปุ๋ย : ขอบคุณแหล่งข้อมูล : หนังสือพิมพ์ The Nation.

https://www.nationthailand.com/business/30387212?utm_source=category&utm_medium=internal_referral

The big keep getting bigger in the pandemic-rearranged economy

May 04. 2020
An employee holds a package at the Amazon.com Inc. fulfilment center in Tilbury, U.K,. in July 2019. MUST CREDIT: Jason Alden

An employee holds a package at the Amazon.com Inc. fulfilment center in Tilbury, U.K,. in July 2019. MUST CREDIT: Jason Alden
By Bloomberg · David McLaughlin · BUSINESS, TECHNOLOGY, US-GLOBAL-MARKETS, RETAIL

COMPANIES-ANALYSIS : Welcome to the post-pandemic U.S. economy. The biggest companies are getting even bigger. Midsize players are running on fumes. Brick-and-mortar stores are struggling to get financing just to make it to next month. Startups – the building blocks of a competitive economy – are disappearing.

It all adds up to a sobering challenge for U.S. antitrust enforcers: The pandemic risks worsening the very problems of rising concentration and declining competition that they were already trying to address before the outbreak.

For almost a year, the Justice Department, Federal Trade Commission, and state attorneys general have been investigating Alphabet Inc.’s Google and Facebook Inc. for possible antitrust infractions. Antitrust officials claimed those inquiries were hardly slowed down by the outbreak as they shifted to working remotely. As the economy reopens, enforcers may find themselves under pressure not to undertake actions that could hurt jobs.

The pandemic is playing to the strengths of the biggest digital players, as seen in their earnings results for the quarter ending in March. Amazon.com Inc. has gone on a hiring spree to keep up with a surge in demand from millions of homebound consumers. In what is normally a slow quarter, sales jumped 26% to a record $75.5 billion, though earnings fell 29% compared with the same period in 2019.

Alphabet’s revenue exceeded analysts’ expectations. Facebook’s shares soared on Thursday after its results eased some investor concerns about advertising weakness, though the real test could come in the months ahead. Investors were braced for one of the biggest annual sales declines in Apple Inc.’s history, but the company reported a surprising 1% revenue increase to $58.3 billion.

At the same time, retailers, restaurants, airlines and hotels are struggling – and more than 30 million Americans have suddenly become jobless.

Dominant companies were already on the march across industries, from the internet to wireless carriers and from health care to food processing, long before the virus hit. For years, antitrust experts and economists have been warning that markets were becoming less competitive, harming consumers and workers in the process.

Now, antitrust experts fear that as the largest companies increase market shares, decimated firms might disappear or have little choice but to sell out at fire-sale prices to stronger rivals – and that regulators and lawmakers will be under pressure not to stand in the way as the economy struggles to get up off its knees.

“If you have some shock to the system – a financial crisis, a war – one effect is the weakest firms in the market tend to fail,” said Daniel Crane, a professor at the University of Michigan who studies antitrust law. “I do worry that the world that recovers from this will be one characterized by firms having failed and pressure to consolidate.”

The 2008 financial crisis, in which a wave of bank mergers increased concentration, could offer a template for what’s to come. The banks that were “too big to fail” in 2008 got even bigger, with the blessing of policy makers who encouraged the strong to gobble up the weak.

By 2012, five banks – JPMorgan Chase & Co., Bank of America Corp., Citigroup Inc., Wells Fargo & Co., and Goldman Sachs Group Inc. – were about twice as large as they had been a decade earlier, relative to the U.S. economy, with $8.5 trillion in assets.

This time, embattled retail, restaurant, entertainment and travel industries could follow suit. Clothing chain J. Crew Group Inc. is preparing a potential bankruptcy filing, Bloomberg has reported. J.C. Penney Co. and Neiman Marcus Group Inc. are in talks with creditors about restructuring debt and might file for bankruptcy. Car-rental giant Hertz Global Holdings Inc. is trying to preserve cash and get leniency from lenders to avoid a bankruptcy.

New York University economist Thomas Philippon, whose book, “The Great Reversal,” documented how U.S. markets have become less competitive, said big companies gained access to Federal Reserve lending facilities in the $2 trillion coronavirus stimulus package. Meanwhile, millions of small firms were left with a poorly designed Small Business Administration loan program that’s been swamped by demand, including from larger companies with the ability to tap stock and bond markets.

“It will be harder for younger firms to survive, and they are the potential new competitors,” Philippon said.

Some are already closing up shop. Service, a travel app, folded after an investment deal and a backup plan to sell to Enterprise Holdings Inc. fell through in quick succession, said Michael Schneider, the chief executive officer. He had to inform his nine employees in Los Angeles that they were out of a job. “It feels like the end of the world,” he said.

Supply-chain bottlenecks from one industry’s high concentration level already have led to President Donald Trump invoking the Defense Production Act to keep food supplies flowing. On April 29, he ordered meat-processing giant Tyson Foods Inc. and other slaughterhouses to keep their plants open – despite covid-19 outbreaks that have sickened thousands.

Tyson and its top two rivals – JBS SA and Cargill Inc. – control about two-thirds of America’s beef production, the bulk of which is done in a few dozen giant plants. Pork and chicken are similarly dominated. Their tight control prompted Senators Tammy Baldwin, a Wisconsin Democrat, and Josh Hawley, a Missouri Republican, on April 29 to seek an antitrust probe of the meatpacking industry.

“This is 100% a symptom of consolidation,” said Christopher Leonard, author of “The Meat Racket,” which examines the protein industry. “The virus is exposing the profound fragility that comes with this kind of consolidation.”

The pandemic could reshape the American economy in myriad ways, as companies begin to teeter and corporate defaults are projected to soar. And the fallout won’t be limited to the U.S.

Jean-Paul Agon, the chairman of French cosmetics giant L’Oreal SA, alluded to that possibility on an April 16 earnings call. “It’s unfortunate, but it’s the Darwinian side of this industry,” he said. “We are pretty sure to be able to get out this crisis even stronger. So will there be opportunities for interesting acquisitions? We will see.”

Wall Street investment banker Ken Moelis echoed that sentiment. “The people who are going to survive this are obviously the biggest folks in their industry,” he said during Moelis & Co.’s April 22 earnings call. “I could see a large M&A wave in industries where you just have to consolidate out the middle, and we end up with very large concentrated industries.”

Even as the pandemic grinds deal-making to a halt, famed investors in struggling companies like Howard Marks’ Oaktree Capital Group are getting ready to pounce. Mastercard Inc. Chief Executive Officer Ajay Banga told investors on an April 29 conference call that the company is “keeping the powder dry” for acquisitions.

Fear of a consolidation wave has led Rep. David Cicilline, D-R.I., who chairs the House antitrust panel, to call for a moratorium on acquisitions.

“As millions of businesses struggle to stay afloat, private equity firms and dominant corporations are positioned to swoop in for a buying spree,” Cicilline said at an April 23 conference.

Two other Democrats, Sen. Elizabeth Warren of Massachusetts and Rep. Alexandria Ocasio-Cortez of New York, are proposing legislation to ban corporate mergers while the pandemic persists. Cicilline said in an April 28 interview with Bloomberg TV that he would try to get the ban included in the next stimulus measure.

The increase in concentration has sparked calls for tougher antitrust enforcement and proposals to overhaul how regulators police mergers and anti-competitive conduct. The issue was debated on the 2020 presidential campaign trail and has become an area of common ground for Democrats and Republicans who have raised concerns about the power wielded by big companies, particularly Google and Facebook.

Yet antitrust officials at the Justice Department and the FTC could face political pressure to pull back on enforcement, said Crane, the University of Michigan professor, who has researched how competition enforcement was ceded to other priorities during wars and financial panics. During World War II, for example, the Franklin Roosevelt administration implemented formal policies that shielded companies from antitrust prosecution.

As the pandemic accelerates Amazon’s grip on U.S. online retail sales – its market share already was about 40% – it could also permanently shift consumer behavior toward online shopping, further dooming physical stores and alarming antitrust overseers. On Friday, Rep. Jerrold Nadler, D-N.Y., the House Judiciary Committee chairman, called Amazon Chief Executive Officer Jeff Bezos to testify about his company’s treatment of third-party merchants on Amazon’s website.

Hospitals could be another area of consolidation. To deal with the virus outbreak, they are delaying elective surgery, which is worsening already squeezed finances at many providers. An April 6 report by Boston Consulting Group said the strain on hospitals would accelerate consolidation and the integration of independent physicians into health systems. Bloomberg Intelligence health-care analyst Glen Losev expects hospital operators HCA Healthcare Inc. and Tenet Healthcare Corp. to be buyers once the crisis recedes.

“Our health-care supply chain because of all the consolidation is already bottled-necked,” said Diana Moss, the president of the American Antitrust Institute, which advocates for aggressive merger enforcement. “Allowing more consolidation would mean more bottle-necking and more dominance and lack of flexibility.”

Sontirat taps entrepreneurs, experts for solutions to enable economic recovery #ศาสตร์เกษตรดินปุ๋ย

#ศาสตร์เกษตรดินปุ๋ย : ขอบคุณแหล่งข้อมูล : หนังสือพิมพ์ The Nation.

https://www.nationthailand.com/business/30387576?utm_source=category&utm_medium=internal_referral

Sontirat taps entrepreneurs, experts for solutions to enable economic recovery

May 09. 2020
By THE NATION

Energy Minister Sontirat Sontijirawong has urged entrepreneurs and experts to suggest solutions for helping the country’s economic recovery after the Covid-19 crisis.

He made his remarks after visiting the oil depots and gas stations of PSP Specialities in Samut Sakhon province on Friday (May 8). He said he aimed to hear out oil depot operators’ problems during the Covid-19 crisis.

“We found that the demand for various fuels had dropped as people have to stay at home to contain the spread of Covid-19.

“Therefore, we have asked energy business entrepreneurs and academics to propose solutions and recommendations to the government, so that measures can be implemented to help the economy recover after the Covid-19 crisis is resolved.”

He said that the economic cabinet is currently considering a recovery plan focusing on boosting the grass-roots economy.

“We have instructed ministers of related ministries to propose recovery packages to the Cabinet as soon as possible,” he said.

He added that the Energy Ministry will discuss an economic recovery package for energy next week, adding that they would focus on boosting the grass-roots economy.

“We will consider using the ministry’s budget and take loans under the emergency decree,” he said.

He said the Energy Regulatory Commission would announce next week the purchase of electricity not exceeding 100 megawatts.

“Meanwhile, we expect the community power plant project to be approved within June this year,” he said.

He added that the ministry would consider scrapping sales of some diesel and benzene fuels, which would help reduce storage cost and types of fuels.

“However, we will promote B10 and E20 biofuels to generate income for farmers,” he added.

Meanwhile, Sint Krongphanich, chief executive officer of PSP Specialities, said that oil sales in April this year had dropped by some 30 per cent due to the Covid-19 outbreak.

“We have advised the government to consider tax assistance to increase the liquidity of entrepreneurs,” he said.

More than a quarter of workers faced job losses or underemployment in April #ศาสตร์เกษตรดินปุ๋ย

#ศาสตร์เกษตรดินปุ๋ย : ขอบคุณแหล่งข้อมูล : หนังสือพิมพ์ The Nation.

https://www.nationthailand.com/business/30387553?utm_source=category&utm_medium=internal_referral

More than a quarter of workers faced job losses or underemployment in April

May 09. 2020
Photo by: The Washington Post — The Washington Post

Photo by: The Washington Post — The Washington Post
By The Washington Post · Alyssa Fowers · NATIONAL, BUSINESS

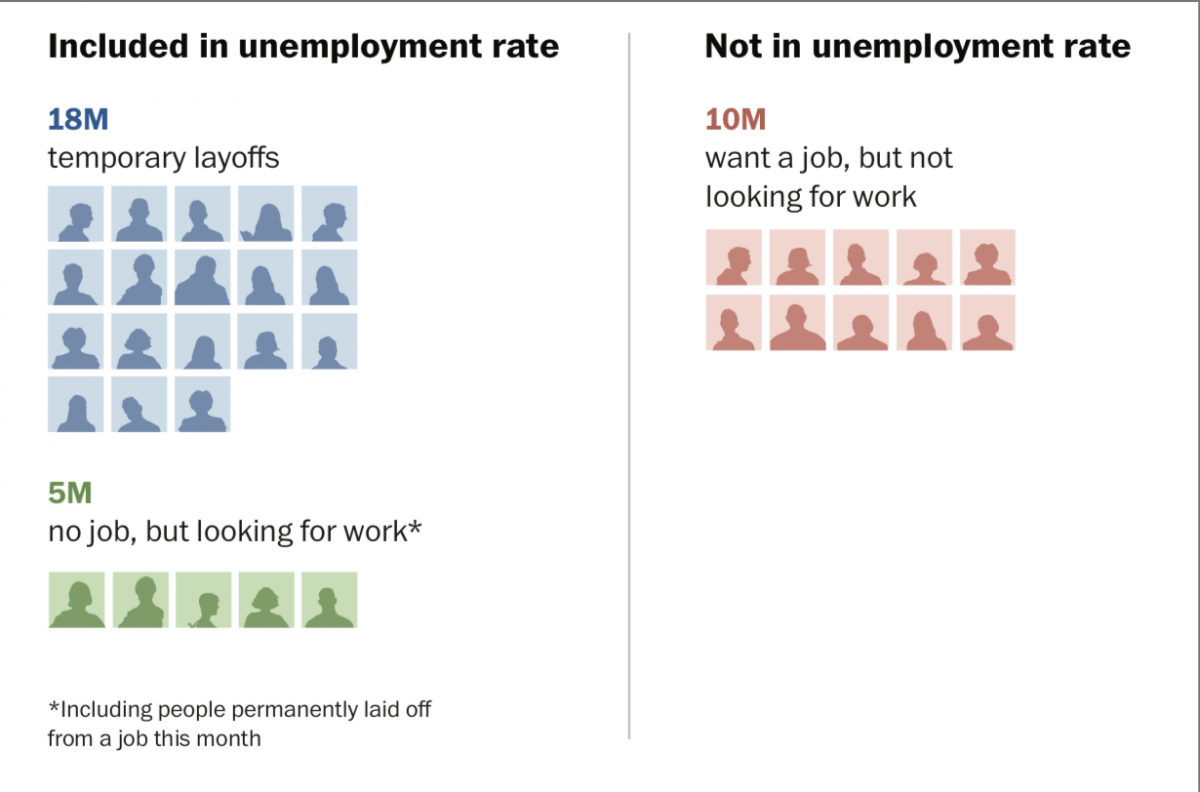
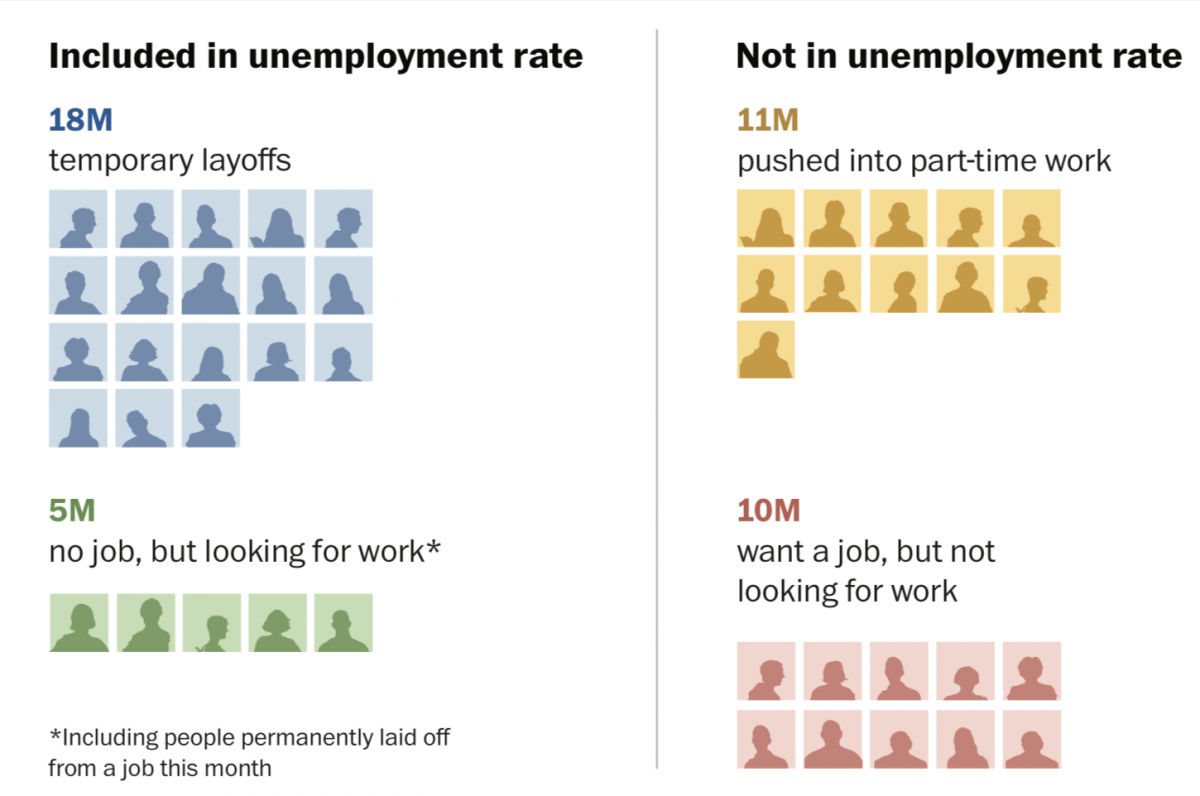
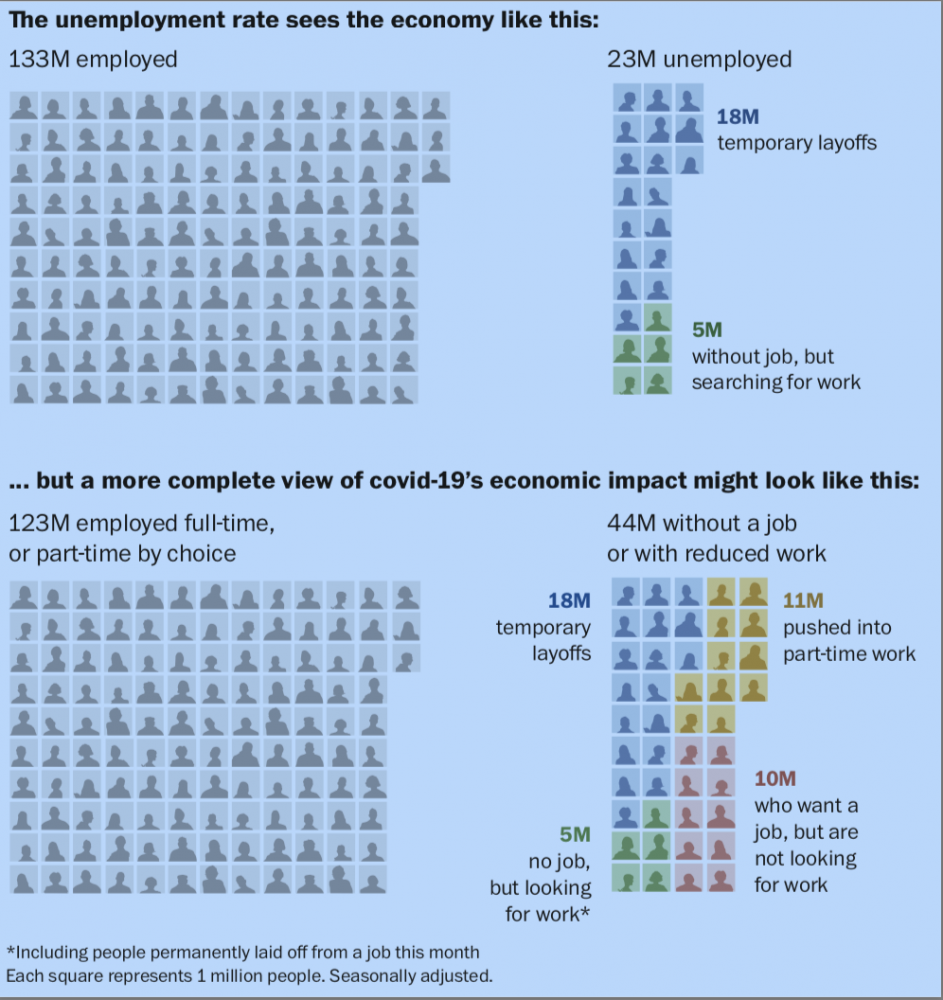
WASHINGTON – The U.S. economy is in trouble, and today’s staggering unemployment numbers only tell part of the story. More than 27 million people stopped working between March and April, but over a third of them are not included in the official unemployment rate of 14.7%.

Millions have been pushed into part-time hours, or want a job but aren’t currently looking for one. Taking these people into account, 26.4% of American workers are employed below their capacity.

Photo by: The Washington Post — The Washington Post

Photo by: The Washington Post — The Washington Post

The official unemployment rate looks only at the labor force: people who are currently working, who have been “temporarily” laid off but expect to be recalled to their jobs, or who are actively seeking work. In ordinary times, this calculation makes sense. Retired people or stay-at-home parents shouldn’t count among America’s unemployed.

Photo by: The Washington Post — The Washington Post

Photo by: The Washington Post — The Washington Post

But these are not ordinary times. During the pandemic, many people have stopped looking for work. They may not feel safe working, or they are discouraged by the lack of jobs available during stay-at-home orders. 9.5 million Americans who worked in March exited the labor force in May, according to this month’s job report. That’s twice the number that went from employed to out of the labor force in January.

Most people who leave the labor force want to return to work at some point. The Bureau of Labor Statistics collects information about people who are not in the labor force but want a job. That group jumped by 4.4 million between the March and April jobs report. If you added these Americans to the official unemployment rate, you’d get a new rate as high as 19.8%.

Photo by: The Washington Post — The Washington Post

Photo by: The Washington Post — The Washington Post

But for millions of workers, keeping their jobs didn’t mean avoiding hardship. The number of people working part-time nearly doubled, from 5.8 million in the March report to 10.7 million in the April report. Every month some workers choose to go part-time, but this trend was driven by those who had their hours cut by their employer or were unable to find a full-time job.

Working hours dropped more in some industries than others. Manufacturing workers dropped to an average of 38.3 hours per week, down from 40.4 in March. That may seem like a small drop, but in a typical jobs report, the average hours worked changes by about six minutes from the previous month.

It’s by far the largest drop in hours in manufacturing since the Bureau of Labor Statistics began tracking average hours in 2006. The construction and wholesale trade industries also saw large drops in weekly working hours.

Henry Farber, an economist at Princeton University, explained that cutting hours could save on hiring and training down the road. “Many employers are laying people off reluctantly and expecting to bring them back,” Farber said. “It’s expensive to hire and train new workers, and the best way to stay attached to your workers is cut hours but keep them on the payroll.”

On the other hand, the cost of health insurance may push employers to cut jobs, rather than hours. “The fact that we tie health insurance to work complicates the labor market in all kinds of ways,” Farber said.

So if you take the official unemployment figure, add in people who want a job but are not looking for one, and then include everyone who has been pushed into part-time work, you could say that 26.4% of people lost work or work hours in April. More than one in four workers has been hit by the coronavirus fallout.

Even these measures don’t capture the breadth of economic pain. There are millions more Americans who don’t earn paychecks on their own, like stay-at-home parents, but are just as affected by losses in household income. An entire generation of new workers has seen their education disrupted.

There is still a long way to go before the economy recovers. While many states are starting to reopen, the number of daily deaths from the virus has not dropped off yet. April is the first jobs report to truly capture the scope of the economic crisis, but it is just the first of many.

Stocks surge on one of the unhappiest days in American economic history: Here’s why #ศาสตร์เกษตรดินปุ๋ย

#ศาสตร์เกษตรดินปุ๋ย : ขอบคุณแหล่งข้อมูล : หนังสือพิมพ์ The Nation.

https://www.nationthailand.com/business/30387552?utm_source=category&utm_medium=internal_referral

Stocks surge on one of the unhappiest days in American economic history: Here’s why

May 09. 2020
By The Washington Post · Thomas Heath · BUSINESS, US-GLOBAL-MARKETS

The worst unemployment report in American history screamed across computer and television screens Friday morning, announcing that a breathtaking 20.5 million Americans lost their jobs in April.

The next 60 seconds saw the Dow Jones industrial average jump, a 300-point pop that extended through the opening bell and into afternoon trading. The Standard & Poor’s index 500, a broader indicator of corporate America, likewise surged roughly 1.4 percent.

Stocks held onto their gains and pushed them higher in the last hour. The Dow finished up 455 points, or 1.9 percent to 24,331, ending the week with a total gain of 2.4 percent. The blue chips closed above 24,300. The S&P 500 finished the day at a 1.7 percent gain, to 2,929, and closed the week up 3.4 percent.

The Nasdaq composite was up 1.5 percent Friday and nearly 6 percent on the week.

Wall Street often behaves counterintuitively, as its reaction to 14.7 percent unemployment can attest. But Friday’s gains speak to investors’ willingness to look beyond the economic wreckage wrought by the coronavirus pandemic. Here are seven reasons why:

1. The stock market is a future indicator, not a rear-view mirror.

Investors are betting on how companies will be performing a month from now, six months from now, even a year from now.

“Stock prices are based on expectations,” said Howard Silverblatt of S&P Dow Jones Indices. “The current bad news was already baked in, as is more to come. But the longer-term hopes and expectations are for a reopening and corporate recovery.”

The stock market has been one of the best real-time measures for gauging what investors are thinking. The S&P 500 index is a reliable indicator of future performance for America’s 500 largest companies. Its role as a business indicator is based on the collective wisdom of millions of investors who are wagering tens of billions of dollars a day based on untold bits of available information. The efficient market theory, as it is known to its adherents, holds to the belief that the market prices most stocks correctly, based on the information available.

2. Technology stocks are killing it.

Tech giants Amazon, Apple, Google-parent Alphabet, Microsoft and Facebook have been on a serious tear for years and are behind a big chunk of recent gains. Microsoft shares have jumped 17 percent and Amazon has soared 28 percent since the start of the year. Facebook, Apple and Alphabet’s gains are hovering near 3 percent.

The five stocks comprise 21 percent of the S&P 500. They have lifted the Nasdaq composite into positive territory in 2020 even as the coronavirus pandemic has devastated the economy. (Amazon founder Jeff Bezos owns The Washington Post.)

“These are the stocks that have empowered the economy and have been the job-creation engines,” said Ivan Feinseth of Tigress Financial Partners. “They are enabling people to work at home. Investors realize the value they provide and they create and believe they will continue to be successful. Like it or not, Facebook kept people who are isolated from being alone.”

3. There’s hope on the health front.

Despite the pandemic’s terrible toll – 76,000 American deaths and climbing – the global pharmaceutical industry has massed its resources to laser focus on finding vaccines and treatments.

Johnson & Johnson, Pfizer and biotech company Moderna are among the companies racing to find a vaccine.

The Food and Drug Administration signed off this week on Moderna launching the next phase of testing on its coronavirus vaccine candidate. The company began its testing on 45 healthy adults in March, becoming one of the first companies to begin human clinical trials for a covid-19 vaccine.

Gilead Sciences reported “positive data” in a clinical trial by the National Institute of Allergy and Infectious Diseases for remdesivir, another possible treatment.

The trial showed that “a drug can block this virus,” Anthony Fauci, director of the institute, said in a news conference Wednesday.

The hardest hit states of New York, New Jersey and Connecticut have reported progress against the disease, with deaths, infections and hospitalizations down from their peaks weeks ago. While the disease is spreading in other parts of the country, hospitals do not appear to be overwhelmed with virus victims.

Goldman Sachs published a report this week that shows improvements around the globe but some mixed results in the U.S. as more states relax their lockdowns and businesses begin to open.

“The new information on the coronavirus has improved in Europe but has turned a bit worse in the U.S. relative to expectations on average over the past two weeks,” Goldman said in its report. “Compared with the recent trend, the current number of new infections has been broadly stable globally on net. This reflects further declines in Europe, very few new cases in China, roughly stable but elevated gains in the U.S. and further rises in emerging markets.”

Ed Yardeni, president of Yardeni Research, said “there are some signs of success on the health front. The market is looking at the rate of change of virus cases and deaths, and it doesn’t look like its getting worse. The market is expecting it’s going to get better as it has in China and in Italy. It is extrapolating from those countries’ experience.”

4. Oil markets are calming down and prices are rising, which is good for a key industry.

The price of oil is not where it needs to be, but it is going in the right direction for producers. U.S. crude oil is back near $25 per barrel and Brent crude, the international benchmark, is up near $30.

Producers need $50 or so per barrel to make money, but current prices are far better than they were just a couple of weeks ago. Holders of U.S. crude were paying people to take oil off their hands last month.

There is still a massive oil glut, but with the U.S. shale industry shutting down wells at a swift rate, the balance between supply and demand is getting close. The U.S. pumped 13.1 million barrels a day a few weeks ago. Now it is closer to 12 million and heading south. Meanwhile, drivers around the world are slowly getting back on the road. Gasoline usage is still down 30 percent from pre-virus levels, but it has improved from the 50 percent decline in March.

“The oil price stabilization and rise is a ray of light that we are getting through this economic darkness,” said John Kilduff of Again Capital. “It’s clear there is pent-up demand waiting to be unleashed, and we are seeing that in the rebound in gasoline numbers toward normal levels.”

5. The Federal Reserve and the U.S. government have flooded the economy with trillions in cash and easy credit.

Investors have credited the central bank with saving the markets from collapse and preventing a new financial crisis from making the recession worse. As trading seized up in March amid the initial panic, the Fed swiftly launched plans to buy massive quantities of government, corporate and municipal bonds.

The Fed is launching a program to lend directly to Main Street businesses that fall in the crack between financial markets and existing small-business programs. But the unusual effort is only getting started.

“The Fed went from bazookas that had mostly run out of ammo and skipped helicopters and went straight to the B-52s carpet bombing tons of cash on the financial markets and the economy,” Yardeni said.

The super-low interest rates promulgated by the Fed have sent investors out of bonds and running to equities in search of returns, helping raise stock prices.

The Trump administration launched an unprecedented small-business loan program designed to prevent companies from laying off their workers, part of nearly $3 trillion Congress approved to counter the pandemic’s medical and economic toll.

6. The U.S.-China trade war truce looks like it may not unravel, which is good for the economy.

U.S. Trade Representative Robert E. Lighthizer and Treasury Secretary Steven Mnuchin on Thursday held a conference call with Liu He, China’s vice premier and point man on the trade deal, to make sure the “phase one” agreement was on track.

Trump has said he is unhappy with China, which he has held responsible for allowing the virus to take hold and spread. Secretary of State Mike Pompeo pointedly criticized the Chinese for its role in the virus, raising fears of retaliation. But more than 30 million unemployed, many economists say it would be a bad idea for the administration to engage in a trade war.

7. Shanghai Disneyland has sold out.

Disney said tickets to it’s park in Shanghai, which opens Monday, sold out in minutes. Although the park will only admit 30 percent of it’s capacity, peoples’ appetite to get out and spend money bodes well for the U.S. Disney is looked at as a model for crowd control, so hospitality and entertainment companies will watch closely.

New interest rule introduced to relieve load on borrowers, cut NPLs #ศาสตร์เกษตรดินปุ๋ย

#ศาสตร์เกษตรดินปุ๋ย : ขอบคุณแหล่งข้อมูล : หนังสือพิมพ์ The Nation.

https://www.nationthailand.com/business/30387535?utm_source=category&utm_medium=internal_referral

New interest rule introduced to relieve load on borrowers, cut NPLs

May 09. 2020
Thanyanit Niyomkarn, the Bangkok of Thailand’s assistant governor

Thanyanit Niyomkarn, the Bangkok of Thailand’s assistant governor
By The Nation

In a bid to ease debt-repayment burden on borrowers as well as minimise the number of non-performing loans, the central bank has come up with a new method of calculating interest.

This new method of calculating interest charged on overdue debt was enforced on May 1, Thanyanit Niyomkarn, the Bangkok of Thailand’s assistant governor, said on Friday (May 8).

She added that this new practice is fair for both the borrower and the lender as the interest charged will be based on actual instalments that debtors have defaulted on.

Thanyanit explained that in the past, if a borrower failed to pay an instalment, the bank would charge extra interest on that instalment plus interest on the remaining balance of the principle. Under the new system, however, interest will only be charged on the defaulted instalment.

For instance, an individual has taken a 20-year housing loan to be paid in 240 instalments, and has paid the first 24 instalments without fail. However, if the borrower failed to pay the 25th instalment, the bank would charge interest on both the 25th instalment as well as the remaining 215 instalments.

However, under the new practice, banks can only charge extra interest on the 25th instalment.

This new practice takes into account the interest of both the creditor and the debtor, or credit risk and affordability risk respectively, she said.

Since many people’s income has either reduced or even stopped due to the pandemic, they may not be able to pay their debts on time. Hence, this new method of interest calculation will ease some burden on them and potentially cut down on the number of defaulting debts, she said.

At the same time, fair and transparent banking services will boost consumers’ confidence as well as benefit the sector in the long run, she said.

Banks can apply this new practice for debts that were overdue before May 1.

People can call the central bank 1213 hotline for more details.

Fear, federal aid make it hard for restaurants to staff up #ศาสตร์เกษตรดินปุ๋ย

#ศาสตร์เกษตรดินปุ๋ย : ขอบคุณแหล่งข้อมูล : หนังสือพิมพ์ The Nation.

https://www.nationthailand.com/business/30387547?utm_source=category&utm_medium=internal_referral

Fear, federal aid make it hard for restaurants to staff up

May 08. 2020
A customer wearing a protective mask enters a Dunkin' location in the New York borough of Brooklyn on April 27, 2020. MUST CREDIT: Bloomberg photo by Gabby Jones.

A customer wearing a protective mask enters a Dunkin’ location in the New York borough of Brooklyn on April 27, 2020. MUST CREDIT: Bloomberg photo by Gabby Jones.
By Syndication Washington Post, Bloomberg · Leslie Patton · BUSINESS, RETAIL

Restaurant managers are scrubbing tables, adding sanitizing stations and printing new menus as they get ready to open their doors. The one thing some of them are missing? People to make and serve the food.

More than 20 million Americans lost their jobs in April during the covid-19 crisis, but restaurants are still finding it hard to hire help.

Some former employees are making more money now thanks to an extra federal emergency payment of $600 weekly on top of state unemployment benefits. Others have found new jobs or are staying home with kids. Many are simply too nervous to interact with the public before the coronavirus outbreak subsides.

The labor challenges compound the financial hurdles for the restaurant industry, which, according to the National Restaurant Association, has lost about $80 billion in sales through the end of April due to the coronavirus shutdowns.

Companies eyeing a return to normal operations, including Dunkin’ Brands Group Inc., Salsarita’s Fresh Cantina and Shake Shack Inc., are grappling with how to staff their restaurants.

“Some stores are definitely having a challenge,” said Scott Murphy, president of Dunkin’s Americas region. Especially in hard-hit areas such as New York City, he said, the restaurants are “having trouble getting workers.”

Tina Watson used to work every weekday at a Wendy’s in Santee, South Carolina. But with broad stay-at-home mandates going into effect in March, her hours were cut back sharply, reducing her $500 biweekly paycheck to less than half.

She doesn’t qualify for unemployment at the moment. Despite the financial strain, Watson, 41, is wary about working. Sometimes she can’t go because she doesn’t have anyone to watch her 11-year-old son, whose school is closed, leaving her restaurant short-staffed.

“I don’t think I’m going to be able to go back to work knowing my son can’t go to school and I don’t have a reliable sitter,” she said.

Of the job cuts announced from mid-March to late April, almost two-thirds have been in the entertainment and leisure sector including dining, according to consulting firm Challenger, Gray & Christmas.

U.S. government efforts to support people who have lost their jobs has had the unintended consequence of keeping some restaurant workers away. Under March’s federal stimulus act, people eligible to get state unemployment assistance get an extra $600 a week funded by the federal government through the end of July.

The median pay for food preparation workers was $11.92 an hour in 2019, according to the U.S. Bureau of Labor Statistics, or $476.80 for a 40-hour week.

Steve Joyce, chief executive officer of Applebee’s-owner Dine Brands Global Inc., said the extra federal assistance “creates in a lot of markets a relatively high reimbursement rate for a limited amount of time.”

This is why some restaurants are resorting to financial incentives to get workers back. Shake Shack, for instance, is offering an extra 10% in pay as a “thank you” to new hires, according to job postings in Texas and Seattle. Some Dunkin’ franchisees are using bonuses and free meals to keep staff on the payroll, while the parent company weighs a new-hire ad campaign.

Not every company is having such a hard time finding workers. Papa John’s International Inc. has brought on thousands in the last six weeks amid a broad hiring effort, which CEO Rob Lynch said is intended to get locations “appropriately staffed” to handle higher demand.

“I think people want to work now even more so than they did even four to five weeks ago,” he said. “We’ve been hiring like crazy and we’re going to continue to do so.”

In fact, companies may need to hire even more workers than they had before the pandemic, to deal with extra cleaning measures, said Peter Saleh, a restaurant analyst at BTIG. “They’re probably going to want to over-staff in this environment and be prepared.”

These type of “labor inefficiencies” have been flagged by restaurants planning their reopening strategies. And refilling the same position can introduce new costs, particularly if restaurants have to hire inexperienced workers.

“If you can’t bring back people you know, you have to go through training,” said Salsarita’s CEO Phil Friedman.

Salsarita’s has had to delay reopenings in certain locations, including South Carolina, because it can’t find enough people. Hourly staff particularly are reluctant to return because many have found new jobs or are nervous about working, and it could take weeks to fill out the ranks, Friedman said.

“It really is a day by day,” he said.

Stocks rise in wake of unprecedented job losses #ศาสตร์เกษตรดินปุ๋ย

#ศาสตร์เกษตรดินปุ๋ย : ขอบคุณแหล่งข้อมูล : หนังสือพิมพ์ The Nation.

https://www.nationthailand.com/business/30387544?utm_source=category&utm_medium=internal_referral

Stocks rise in wake of unprecedented job losses

May 08. 2020
By Syndication Washington Post, Bloomberg · Vildana Hajric · BUSINESS, US-GLOBAL-MARKETS

Stocks rose for a second day with investors embracing risk in spite of the biggest monthly loss in jobs in at least 70 years. The dollar weakened and oil gained.

Shares of energy, industrial and financial companies put the S&P 500 on pace for its first weekly gain in three. The latest jobs report showed a cut of 20.5 million workers in April, propelling the jobless rate to 14.7%. While that was the highest since the Great Depression, investors were anticipating the damage and speculating it will mark a low point during the pandemic-fueled economic slump.

“The jobs report marks a sobering moment in our history, while it also likely marks the bottom of the economic contraction with hope for a better remainder of the year,” said Bryce Doty, senior portfolio manager at Sit Fixed Income Advisors.

Meanwhile, oil headed for its first back-to-back weekly gain since February as output cuts from the biggest producers and a nascent recovery in demand began to rebalance a market awash with crude.

Stocks remained higher even after President Donald Trump cast doubt on the future of his “phase one” trade deal with China, saying Friday that he’s struggling with Beijing in the wake of the coronavirus pandemic.

Building and travel stocks pulled the Euro Stoxx Index higher while U.K. markets were closed for a holiday. Japanese equities led a surge across Asia. Italian bonds climbed before a sovereign ratings decision.

Equities have so far managed to weather miserable economic data as well as a string of poor earnings reports as investors bet on a swift recovery, but the strong rebound in risk assets has left others questioning whether further gains are warranted.

“There had been some concerns that unemployment would hit closer to 25%, so today’s data is in some ways a positive surprise,” said Seema Shah, chief strategist for Principal Global Investors. “Today’s data has been weighing on negative sentiment for several weeks, so just having it out of the way lifts a cloud.”

Elsewhere, gold fluctuated. Bitcoin rose briefly above $10,000 for the first time since late February.

Stocks:

– The S&P 500 Index gained 1% to 2,915.15 as of 10:29 a.m. New York time.

– The Dow Jones Industrial Average climbed 1.2% to 24,195.10.

– The Nasdaq Composite Index increased 0.6% to 9,084.85, hitting the highest in 10 weeks with its fifth consecutive advance.

– The MSCI All-Country World Index rose 1.2% to 488.42.

Currencies:

– The Bloomberg Dollar Spot Index decreased 0.1% to 1,246.87.

– The Japanese yen weakened 0.3% to 106.58 per dollar.

– The euro was little changed at $1.0838.

– The British pound was little changed at $1.2425.

Bonds:

– The yield on two-year Treasuries decreased two basis points to 0.12%, the lowest on record.

– The yield on 10-year Treasuries rose one basis point to 0.65%.

– Germany’s 10-year yield gained one basis point to -0.54%.

– Britain’s 10-year yield increased less than one basis point to 0.235%.

Commodities:

– West Texas Intermediate crude gained 3.8% to $24.39 a barrel.

– Gold weakened 0.2% to $1,718.97 an ounce.

What the brutal jobs report means for Trump #ศาสตร์เกษตรดินปุ๋ย

#ศาสตร์เกษตรดินปุ๋ย : ขอบคุณแหล่งข้อมูล : หนังสือพิมพ์ The Nation.

https://www.nationthailand.com/business/30387538?utm_source=category&utm_medium=internal_referral

What the brutal jobs report means for Trump

May 08. 2020
President Trump

President Trump
By The Washington Post · Aaron Blake · NATIONAL, OPINION, BUSINESS, HEALTH, POLITICS, WHITEHOUSE, ESSAYS, US-GLOBAL-MARKETS 

JOBS-BLAKE-ANALYSIS: The unemployment rate hit its highest point since the Great Depression on Friday, spiking more than 10 points to 14.7%. The toll of shutting down large portions of the American economy for the coronavirus outbreak hadn’t completely registered in last month’s report, but this one was predictably brutal.

With that jobs report comes further confirmation that a severe economic downturn will loom over the 2020 election. And traditionally, that has meant curtains for an incumbent president like Donald Trump.

But is that necessarily the case today? There are reasons to be skeptical.

The comparison to the Great Depression will be tempting, given the size of the economic challenges we face. After the market crash in 1929, Herbert Hoover went on to lose to Franklin D. Roosevelt in a landslide in 1932.

But there are two very important and very different questions here: 1) How bad and sustained will the current economic downturn be? And 2) How much do people actually blame that on the president rather than on a situation they believe to be largely out of his control?

While in a traditional economic downturn, it would be rather easy and logical to blame the policies of incumbent politicians, but this one is a special case. The pandemic was something that we were going to have to contend with, to one degree or another. What matters from there is how much people actually attribute the loss of life and economic strife to Trump and other leaders, and how much they think those leaders exacerbated an already-bad situation.

And on that front, things are indeed less dire for Trump than the jobs numbers might suggest – though that could certainly change depending upon the actual numbers and what lay ahead.

While the growing jobs and economic crisis has been well established by this point, Americans by and large still see the economy as one of Trump’s strong points. An Economist/YouGov poll this week showed 53% of people continue to approve of Trump’s handling of jobs and the economy – a number similar to where he’s been at for months. An NPR/PBS/Marist College poll from a couple weeks ago showed an even, 49%-to-49% split on that question.

The YouGov poll, similarly, showed people have more confidence in Trump than in presumptive Democratic nominee Joe Biden on the economy. It asked whether the economy would get better or worse if either man was elected. Voters were split on the question on Trump (36% said it would get better, compared with 35% who said it would get worse), but were slightly negative on Biden (30% better vs. 38% worse).

The poll also asked how each man would handle a recession, and again the advantage was to Trump. While Americans were split (43%-43%) on whether they were confident in his ability to manage a recession, just 33% were confident in Biden’s ability to do so, while 44% said they were “uneasy.”

To the extent the economic downturn is truly registering with people, it doesn’t seem to be something they lay at Trump’s feet – at least not yet. And it doesn’t seem to be a situation in which they are thinking a change would help. That could always shift as the coronavirus outbreak progresses, but views of Trump on that response track strongly with his overall approval numbers, and views of his handling of the economy (which are better than his overall numbers) haven’t changed much.

Regardless of those numbers, this is clearly something that concerns Trump a great deal. From the beginning of the outbreak, he has made clear how concerned he is about being robbed of what he hoped to make his signature reelection issue: the economy. He’s now pushing for a reopening of the economy despite a steady death rate and despite cases in the country still growing outside the early hotbed of New York City. This has led to tensions with health officials who worry that relaxing mitigation measures might not just lead to increased loss of life but force a longer outbreak – a situation that would logically lead, by extension, to more economic turmoil.

As Trump presses forward, though, he may be better served paying attention to how much people truly blame him for the economic troubles versus how much they blame the virus. Viewing this as a zero-sum game in which a bad economy means Trump loses is overly simplistic. It’s true that Trump is polling like an underdog right now, but that’s been the case for a while, and the fundamentals of the race don’t seem to have changed significantly yet. It’s entirely possible that whatever economic pain comes won’t be laid at his feet.

A prolonged outbreak resulting from a failure to appreciate the size of the crisis and easing up too early, though? That could be just as dangerous – if not more. And that’s a much simpler question for voters to ask themselves, if the situation in this country continues to be one of the worst in the world or even deteriorates.

U.S. jobless rate triples to 14.7% in sharpest labor downturn #ศาสตร์เกษตรดินปุ๋ย

#ศาสตร์เกษตรดินปุ๋ย : ขอบคุณแหล่งข้อมูล : หนังสือพิมพ์ The Nation.

https://www.nationthailand.com/business/30387536?utm_source=category&utm_medium=internal_referral

U.S. jobless rate triples to 14.7% in sharpest labor downturn

May 08. 2020
File photo

File photo
By Syndication Washington Post, Bloomberg · Katia Dmitrieva · NATIONAL, BUSINESS

In the harshest downturn for American workers in U.S. history, employers cut an unprecedented 20.5 million jobs in April and the unemployment rate more than tripled to 14.7%.


Back in February, before the coronavirus pandemic brought the U.S. economy to a standstill, the rate hovered at just 3.5%. That had been the lowest level in five decades. April’s is the highest since just after the Great Depression of the 1930s.

The Labor Department said the unadjusted unemployment rate in April would have been almost 5 percentage points higher had workers been classified as unemployed on temporary layoff, rather than employed but absent from work due to other reasons. Furloughed workers accounted for about 4 out of every 5 unemployed Americans.

April’s losses erase roughly all of the jobs that the economy had added in this past decade’s expansion and lay bare just how precarious employment is for vast swaths of Americans.

With a steep recession now in progress, the destruction of jobs heaps election-year pressure on President Donald Trump to restart the economy and show results by November. But with little containment of a contagious disease that’s killed 75,000 Americans and counting, business is returning unevenly and slowly if at all, and signs are mounting that many employers will be forced to make the cuts permanent.

In the minutes after the report, the Bloomberg dollar index pared its decline for the day while the yield on benchmark 10-year Treasuries rose to its highs of the session after the report. S&P 500 futures maintained their gains.

Key details:

– Average hourly earnings rose 4.7% from the prior month and 7.9% from a year earlier, skewed higher by the disproportionate loss of low-wage workers from payrolls — rather than any wage pressures boosting employee pay.

– The labor-force participation rate fell to 60.2% from 62.7%.

– The underemployment rate, which includes discouraged workers and those working part-time who want full hours, rose to 22.8% from 8.7%.

Almost every industry was hit hard. Leisure and hospitality employers cut 7.65 million, manufacturers cut 1.33 million positions and retailers 2.1 million. Even health care jobs fell by 1.44 million as non-Covid visits and elective procedures dried up or offices closed.

The job losses may also fan calls for a fourth round of fiscal aid from Congress on top of trillions of dollars already dispatched, even with signs many Americans are having difficulty tapping the funds. The Federal Reserve is likely to keep pumping money into the economy while leaving interest rates near zero for an extended period.

Trump said Friday that the massive U.S. job losses from the coronavirus outbreak aren’t a surprise and that he shouldn’t be blamed for it.

“It’s totally expected, there’s no surprise,” he said on Fox News Channel, where he was being interviewed as the report was released. “Even the Democrats aren’t blaming me for that. What I can do is I can bring it back.”

While the pandemic has crushed economies around the world, job losses hurt more in the U.S. than in most other developed nations. That’s because about 160 million Americans get health insurance through employers, and without jobs, they could face steep monthly premiums or lose coverage entirely — which may exacerbate the economic impact of Covid-19.

The response rate for the household survey — which determines the unemployment rate — was 13 percentage points lower than usual, as in-person visits were halted. The establishment survey’s response rate was in line with typical rates.