Big Oil’s big crisis: Saving sacred dividends from collapse #ศาสตร์เกษตรดินปุ๋ย

#ศาสตร์เกษตรดินปุ๋ย : ขอบคุณแหล่งข้อมูล : หนังสือพิมพ์ The Nation

https://www.nationthailand.com/business/30384367?utm_source=category&utm_medium=internal_referral

Big Oil’s big crisis: Saving sacred dividends from collapse

Mar 19. 2020
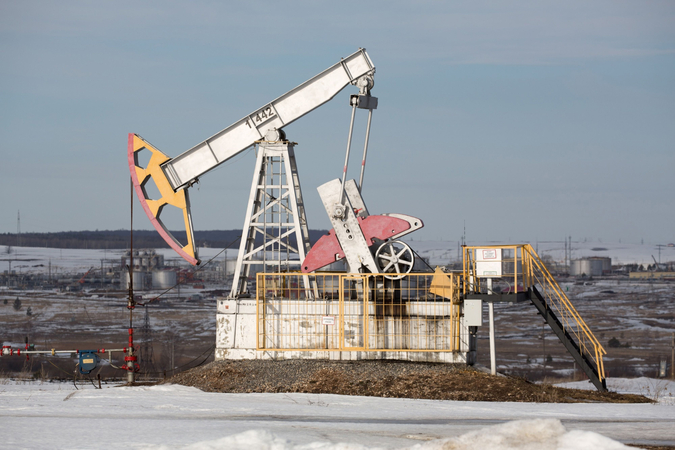
An oil derrick in an oilfield in Otrada, Russia, on March 5, 2016. MUST CREDIT: Bloomberg photo by Andrey Rudakov.

An oil derrick in an oilfield in Otrada, Russia, on March 5, 2016. MUST CREDIT: Bloomberg photo by Andrey Rudakov.
By Syndication Washington Post, Bloomberg · Laura Hurst, Kevin Crowley · BUSINESS, US-GLOBAL-MARKETS

To understand the crisis engulfing the world’s largest oil companies, just look at their dividend yields.

Exxon Mobil Corp., for decades considered one of the bluest of blue-chip stocks, is paying investors 10%. For Royal Dutch Shell, the Anglo-Dutch giant that hasn’t cut payments to shareholders since the Second World War, its 12-month dividend is equivalent to 14% of its current share price. BP offers a yield of 12.4%, and France’s Total 11%.Yields at those levels typically suggest one thing: a significant risk that shareholders may not get the money they’ve been promised.

No Big Oil executive would ever accept that’s true — at least for now. Even as management teams confront both the catastrophic demand destruction wrought by the spread of coronavirus and an oil-price war between Saudi Arabia and Russia, they’re determined to keep paying.

“Nobody wants to be the CEO who cuts the dividend,” said Noah Barrett, a Denver-based energy analyst at Janus Henderson Group, which manages about $375 billion. “They understand that any company that cuts, its shareholders will flow into competitors and be very, very hesitant to ever come back.”

To buy time, they’re taking the ax to capital expenditure. Exxon partially reversed course on an ambitious spending program on Monday, saying it’s weighing significant cuts after being downgraded by S&P Global Ratings. Shell’s outlook was revised to negative on Tuesday by the agency, and risks a rating downgrade unless it lowers its leverage and increases funds from operations.

Shell, Chevron Corp., and Total may also choose to save money for dividends by reducing their share-buyback programs, which are typically seen by investors as more discretionary than the quarterly cash payouts.

Chevron said last week that it’s reviewing options for cutting capital spending and curbing short-term production. BP Chief Financial Officer Brian Gilvary said the British major could curb spending by as much as 20% this year.

While market expectations for Big Oil dividends have reduced over the past two weeks, pricing in a 37% cut from 2019 dividends for European majors in 2021, Goldman Sachs analysts including Michele Della Vigna said that they do not expect a cut because of the current environment. “In past oil downturns, Big Oil on aggregate did not respond to challenging macro conditions through material dividend cuts,” they said in a research note Tuesday.

Even before the crash in prices, Big Oil was in a difficult place. The industry was the worst performing part of the stock market as investors fretted about its ability to navigate the energy transition, invest enough in keeping their businesses going and meet their obligations to shareholders.

“The situation as it stands looks pretty challenged for most of the oil majors, if you were to assume that prices will persist at these levels,” said Nick Stansbury, head of commodity research at Legal & General Investment Management, one of the largest shareholders of major oil companies. “If it sticks for six, nine months, then there will be serious questions raised about the sustainability of dividends.”

These companies’ sheer size gives them the financial flexibility to allow business to continue even in times of significant hardship. Beyond lower spending, Europe’s oil companies could opt to pay dividends to investors in scrip, where cash is substituted with new shares. BP’s Gilvary said this is one tool in his armory, but the company isn’t considering it right now.

Letting debt rise is another option, but Exxon’s downgrade shows the limit of that strategy.”They’re going to have to lean on the balance sheet,” Barrett said. “At some point though, borrowing to pay the dividend is not sustainable.”

Shell declined to comment on its dividend. Exxon spokesman Casey Norton referred back to CEO Darren Woods’s comments at the March 5 investor day when he said the company is “committed to a reliable and growing dividend.” The company has increased the payout each year for the past 37 years.

Maintaining and growing Chevron’s dividend is “top priority,” said spokesman Braden Reddall said by email, reiterating comments earlier this month from CEO Mike Wirth, who said Chevron is on track to raise its annual per-share payout for the 33rd time in 2020.

The flood of Saudi crude onto the market, coupled with slumping demand as the world’s largest economies stop people from traveling and spending, threaten to create an unprecedented oil surplus that could weigh on prices for a long time.

In an enduring slump, Shell’s first remedy would be to revise its share-buyback program. Chief Executive Officer Ben van Beurden already said in January the company would probably miss its target of buying back $25 billion of shares by the end of this year if the macroeconomic environment didn’t improve. Since then, oil prices have fallen by almost half.

Investments in clean energy could also suffer if there’s a lasting downturn. The big European oil companies have been outlining increasingly ambitious strategies to tackle their carbon emissions that will, eventually, require significant capital expenditure.

BP is the boldest so far, saying it will eliminate all its emissions from its own production and operations by 2050. Shell and Total have also made pledges to reduce emissions.

While it’s unlikely that European oil companies will backtrack on their green commitments, low crude prices are typically not good for alternative energy, said Stansbury.

Some oil companies, notably Occidental Petroleum Corp., have already responded to the current slump by cutting dividends. The debt-laden explorer will reduce its 2020 payment by about $2.2 billion, or 86%, setting up CEO Vicki Hollub for a showdown with investors to determine her future.

If Occidental’s decision sent a tremor through the market, then a dividend cut from BP or Shell would cause an earthquake. Those two companies paid out $22 billion in 2019, 20% of the FTSE 100 dividends. U.S. counterparts Exxon and Chevron hold the second and ninth spot as dividend payers on the S&P 500.

Persistent periods of low prices can dramatically reshape the industry. Between 1997 and 1999, Saudi Arabia competed against Venezuela for market share, sending Brent oil prices to as low as $10 a barrel. A wave of mergers followed, creating the era of the supermajors — Exxon coupled with Mobil, BP bought Amoco, Total combined with Elf, and Chevron merged with Texaco.

Throughout this turbulent history, these companies have managed to translate a very volatile commodity into dependable cash flows. If European oil companies can no longer fulfill that role it would be a serious concession, said Legal & General’s Stansbury.

“Cutting the dividend is “a decision no CEO wants to be associated with,” says Russ Mould, investment director at U.K. asset manager AJ Bell. “It can cost you your job.”

Ryanair to cancel almost all flights as virus locks down Europe #ศาสตร์เกษตรดินปุ๋ย

#ศาสตร์เกษตรดินปุ๋ย : ขอบคุณแหล่งข้อมูล : หนังสือพิมพ์ The Nation

https://www.nationthailand.com/business/30384371?utm_source=category&utm_medium=internal_referral

Ryanair to cancel almost all flights as virus locks down Europe

Mar 18. 2020
A Ryanair Boeing 737 landing at Dublin Airport on July 12, 2019. MUST CREDIT: Bloomberg photo by Aidan Crawley.

A Ryanair Boeing 737 landing at Dublin Airport on July 12, 2019. MUST CREDIT: Bloomberg photo by Aidan Crawley.
By Syndication Washington Post, Bloomberg · Siddharth Philip · BUSINESS, WORLD, TRANSPORTATION, US-GLOBAL-MARKETS, EUROPE

Ryanair Holdings, Europe’s biggest discount airline, said it expects to ground most if not all flights from next week as the coronavirus pandemic prompts people to avoid travel and governments lock down borders.

Starting March 24 the carrier will operate only “a very small number of flights to maintain essential connectivity,” mostly between the U.K. and Ireland, it said Wednesday.

The global airline industry needs government aid and bailout measures totaling between $150 billion and $200 billion if it’s to survive the coronavirus crisis, according to the International Air Transport Association. The group expects the outbreak to reshape the industry, with many airlines failing, others consolidating and entirely new groupings emerging.

Ryanair had said March 16 it would defer all capital and discretionary spending, halt share buybacks and freeze recruitment to hep preserve cash. It said then that the bulk of capacity would be cut.

Ryanair has a fleet of over 450 Boeing 737 narrow-body jets, as well as 25 Airbus A320 planes at its Austria unit.

Son’s empire wobbles as credit rout hits softbank debt load #ศาสตร์เกษตรดินปุ๋ย

#ศาสตร์เกษตรดินปุ๋ย : ขอบคุณแหล่งข้อมูล : หนังสือพิมพ์ The Nation

https://www.nationthailand.com/business/30384363?utm_source=category&utm_medium=internal_referral

Son’s empire wobbles as credit rout hits softbank debt load

Mar 18. 2020
Masayoshi Son, chairman and chief executive officer of SoftBank Group, in Jakarta, Indonesia, on Feb. 28, 2020. MUST CREDIT: Bloomberg photo by Dimas Ardian.

Masayoshi Son, chairman and chief executive officer of SoftBank Group, in Jakarta, Indonesia, on Feb. 28, 2020. MUST CREDIT: Bloomberg photo by Dimas Ardian.
By Syndication Washington Post,  Bloomberg · Ayai Tomisawa, Pavel Alpeyev · BUSINESS, US-GLOBAL-MARKETS

Investors are growing increasingly skittish about the stability of Masayoshi Son’s empire.

Son’s SoftBank Group Corp., one of Japan’s most indebted companies, had been chipping away in recent years at concerns about its ability to carry that burden. As the founder remade the telecom company into a tech investor, analysts reassessed the debt in terms of the value of SoftBank’s shareholdings, a gauge that had made its balance sheet appear more manageable.

But the coronavirus pandemic is threatening to undo that progress, as it pulls down equity markets and triggers the worst sell-off in credit markets since the 2008 financial crisis. It’s sparked a dramatic surge in the price of insuring against defaults around the world, including SoftBank’s. The company’s credit-default swaps have spiked to the highest in a decade.

“SoftBank has refinancing needs and constantly faces new fundraising needs, so it would be difficult to access funds if the current credit market turmoil continues,” said Hiroyuki Nishikawa, an analyst at S&P Global Ratings. The base scenario still remains that SoftBank has cash reserves to repay debt for the next two years, he added.

There has been no change in SoftBank’s financial policy of focusing on loan-to-value and having enough liquidity on hand to cover two years worth of bond repayments, the company said in an emailed statement. SoftBank said it is curbing new investments to match the current environment and acknowledged that fundraising costs are likely to rise going forward.

S&P cut its outlook on the group to negative late Tuesday, citing the broad market declines and the conglomerate’s plans for a share buyback. SoftBank shares plummeted 11% in Tokyo on Wednesday, the largest decline since 2012.

Indeed, its stock has plunged 38% in the last month. Its market value of 6.78 trillion yen ($63.5 billion) is now less than that of SoftBank Corp., the domestic telecom operation that sold shares to the public last year. SoftBank Group still owns about two-thirds of the unit, which on Wednesday rose 1.4%.

“No other company in Japan is as indebted and as exposed to the economic downturn as SoftBank,” Amir Anvarzadeh, a market strategist at Asymmetric Advisors in Singapore, who is short on SoftBank, wrote in a note to clients. It seems that Son’s “run of good luck has finally come to an end and his shoot-from-the-hip investment style is blowing up the group.”

The company is more vulnerable because of missteps at the Vision Fund, the $100 billion investment vehicle that Son set up to become the new centerpiece of his empire. The founder used the money to take stakes in scores of marquee startups, including WeWork and Uber Technologies.

But WeWork flopped in its effort to go public last year and fueled broader concern about the prospects for other money-losing startups. SoftBank engineered a $9.5 billion bailout for WeWork and had to take enormous writedowns on the value of its portfolio.

Then last month, activist investor Elliott Management Corp. disclosed a stake in SoftBank, arguing its shares were undervalued and that Son should buy back as much as $20 billion. SoftBank said on March 13 it would spend up to 500 billion yen ($4.7 billion) buying shares.

S&P responded by cutting its outlook for SoftBank, saying the decision “strongly underscores its aggressive financial management.” SoftBank shares, which typically rally with a buyback, have dropped about 18% since the announcement.

The company has traditionally enjoyed strong support from individual bond investors in Japan, thanks to the ubiquity of its brand in the country. The SoftBank name is on one of the largest wireless carriers, Japan’s leading web portal and the champion Fukuoka SoftBank Hawks baseball team. The question is whether this bedrock will hold if the current market turmoil persists. SoftBank has about 2.3 trillion yen of bonds and loans coming due in the next three fiscal years.

Son has argued that he has more than enough assets to cover the debts. The company’s most liquid investments, its stakes in Alibaba Group Holding Ltd. and the SoftBank Corp. unit, are worth about 13 trillion yen and 4.6 trillion yen respectively. Chipmaker Arm Holdings, owned entirely by SoftBank Group, is worth 2.7 trillion yen by the company’s own calculations.

“Clearly the bond market is worried, but we keep coming back to the Alibaba stake, which can more than cover SoftBank’s outstanding debt,” said Dan Baker, an analyst at Morningstar Investment Management Asia Ltd. “Selling during this turmoil means they would have to do it at a lower price, which might make it a last resort.”

SoftBank is taking steps to preserve cash. This week, the company told shareholders of WeWork that it could withdraw from an agreement to buy $3 billion of stock in the embattled co-working business.

Son has said that he wants to keep SoftBank’s loan-to-value ratio, a key metric looking at its net interest-bearing debt against the value of investments, below 25%. S&P said that the gauge would likely be about 30%-35% in the coming year or so.

“The announced buyback is a reminder that all strategic decisions will be taken by Masa Son, who in the face of market uncertainty continues to put SoftBank equity over creditors, without so much as a nod to risk management,” analysts at CreditSights including Mary Pollock wrote in a note.

Saudi Aramco will find it increasingly hard to serve two masters #ศาสตร์เกษตรดินปุ๋ย

#ศาสตร์เกษตรดินปุ๋ย : ขอบคุณแหล่งข้อมูล : หนังสือพิมพ์ The Nation

https://www.nationthailand.com/business/30384501?utm_source=category&utm_medium=internal_referral

Saudi Aramco will find it increasingly hard to serve two masters

Mar 20. 2020
By Syndication Washington Post, Bloomberg Opinion · Ellen R. Wald · OPINION 

Saudi Aramco released its first earnings report as a public company this week, and the oil giant’s management discussed the results with analysts on a call Monday. By itself, Aramco’s 2019 financial performance wasn’t as strong as 2018, but not overly disappointing. However, these numbers show that Aramco – or more accurately the Saudi monarchy, which controls it – may have some hard choices ahead in 2020.

Falling demand for oil from the coronavirus outbreak – combined with the significant drop in prices sparked by Saudi Arabia’s actions to boost output and offer discounts following the breakdown of OPEC+ talks – means that Aramco will make even less money in 2020. Despite Saudi Arabia’s recent announcement that it intends to sell more oil, its profit is likely to fall substantially in 2020, which will force the monarchy to choose whether Aramco will honor its responsibilities to all shareholders as a publicly traded company or whether it will focus on funding the Saudi government.

This is an inflection point for Aramco and Saudi Arabia. The kingdom receives more than 60% of its revenue from the oil industry, and while it has options to help meet its budget – debt, austerity, or new taxes – it is truly reliant on Aramco payments. The government receives funds from Aramco mostly in three ways: a 50% income tax, a royalty on barrels of oil produced and a dividend. With low profit expected in 2020, the cash transferred to the government for the income tax will be limited. With low oil prices, the royalty payments, which are 15% of the price of Brent, will be exceedingly low. And if the company upholds its commitment to public shareholders, there would be less profit left to pay a dividend to the government.

In 2019, net income for Aramco was $88.2 billion, down $22.9 billion from the year before. With Brent now trading significantly below its price at the start of this year, Aramco is looking at lower profits just like every other oil producer. Aramco is taking steps to increase its sales of oil, but it is also offering discounts to do that. In all, revenue will be down significantly, and everyone at the company and in the government must know that. The company plans to drop its capital expenditures to between $25 billion and $30 billion, down from $32.8 billion in 2019, but this won’t be enough to counteract the lower revenue.

Lower profit isn’t the only bad news for the Saudi government. If Brent averages $35 per barrel, the government only receives $5.25 in royalties for each new barrel produced. Even if Aramco averages production of 12 million barrels per day – a major increase from earlier this year – the government would only earn $23 billion in royalties from crude oil. Comparatively, in 2018, Aramco paid the kingdom almost $55.6 billion in royalties and excise taxes. Unless prices rise, the royalty shortfall will be significant.

When it comes to dividends, the monarchy will have to make some critical decisions. In 2019, the company paid $73.2 billion in dividends, of which $3.9 billion were paid to public shareholders as a prorated portion since the December IPO. But Aramco committed to provide public shareholders with their share of a minimum of $75 billion in dividends, starting in 2020. The government, the largest shareholder, isn’t supposed to receive any ordinary dividends until after non-government shareholders are awarded their portion, based on a $75 billion total payout. However, with a lower profit expected in 2020, there may not be enough profit to cover the entire public shareholder dividend. On top of that, the Saudi government may need some sort of special dividend to fund itself.

Free cash flow fell to $78.3 billion in 2019 from $85.8 billion the year before. If Aramco’s board, at the direction of the monarchy, provides a special dividend to the government, it could be pulling money from Aramco’s cash reserves. This would decrease the value of the company’s shares and hurt the Saudi population, 20% of whom bought into the IPO, often on leverage. It would also hamper any plans for another offering of company shares to raise further capital for the government.

The Saudi monarchy, with the assistance of a board that isn’t independent, could revisit its commitment to provide the $75 billion dividend to public shareholders. The company also could decide to give the government leeway on the reimbursements owed to Aramco for the energy and petrochemicals it supplies to Saudi Arabia. In 2019 this equaled $35 billion. But these would betray non-government shareholders and hurt the stock price. If Aramco’s board of directors fails to provide the $75 billion dividend to all public shareholders, and, worse yet, if it funds the government at the expense of the company, it will mean that the monarchy has proclaimed Aramco to be a tool for its power and not public firm at all. And, because it is listed solely on the Saudi exchange, there will be no recourse for any shareholders, except for the loss of faith in the company and a stigma on its shares.


This column does not necessarily reflect the opinion of Bloomberg LP and its owners.

Trump took credit during Wall Street’s highs, but what about its lows? #ศาสตร์เกษตรดินปุ๋ย

#ศาสตร์เกษตรดินปุ๋ย : ขอบคุณแหล่งข้อมูล : หนังสือพิมพ์ The Nation

https://www.nationthailand.com/business/30384390?utm_source=category&utm_medium=internal_referral

Trump took credit during Wall Street’s highs, but what about its lows?

Mar 19. 2020
Stock under Trump
Photo by: The Washington Post — The Washington Post

Stock under Trump Photo by: The Washington Post — The Washington Post
By The Washington Post · Christopher Ingraham · BUSINESS, PERSONAL-FINANCE, US-GLOBAL-MARKETS

MARKETS-ANALYSIS: Financial experts warned President Donald Trump against taking credit for Wall Street’s extraordinary bull run since the beginning of his administration. The foremost reason is that commanders in chief have little actual control over what happens in the markets.

From a purely political standpoint, presidents have tended to avoid claiming too much credit for the markets because stocks that go up inevitably come down. That’s a lesson Trump may be learning this week: On Wednesday, the Dow Jones industrial average came within 75 points of his Inauguration Day close.

Stocks Photo by: The Washington Post — The Washington Post

Stocks Photo by: The Washington Post — The Washington Post

Nearly all of the Trump-era gains, in other words, have been erased.

On Jan. 20, 2017, the Dow closed at 19,827. It soared over the next three years, peaking at 29,551 on Feb. 12 of this year. Within a span of weeks, the Dow plummeted roughly 10,000 points – nearly one-third of its value – as the coronavirus crisis has played out. On Wednesday, it shed another 1,334 points to settle at 19,899.

By comparison, according to investment research platform Macrotrends, the Dow was up 65% at the same point in President Barack Obama’s first term. Under President Bill Clinton, it had climbed 69 percent. The only president since Ronald Reagan to see worse market performance at a comparable point was George W. Bush, who was leading the nation through the aftermath of the Sept. 11, 2001, terrorist attacks.

Nearly all of these shifts are due to factors outside a president’s control. There are well-documented cases in which a market move can be unequivocally tied to the commander in chief’s actions. One of the most recent happened March 11, when Trump’s address to the nation caused Dow futures to drop “in real time with virtually each word Trump uttered,” as Philip Rucker, Ashley Parker and Josh Dawsey recently put it in The Washington Post.

Stepping away from politics, it is also worth noting that the stock market is a highly imperfect metric for the economy overall. Fully half of Americans own no stocks whatsoever, not even through such retirement accounts as a 401(k). Recent research has shown the media’s market obsession creates a portrait of the economy skewed toward the interests of the rich, leaving us with a poor understanding of how middle-class Americans actually are doing.

The reality is the rich are running much of the show. The median U.S. senator is a multimillionaire. Billionaires and the firms they own have an outsize influence on the economy, and market troubles like the ones we’re experiencing now have ripple effects that trickle down to decisions about who gets hired and who gets laid off.

White House, Democrats scramble to assemble massive spending packages as coronavirus fallout worsens #ศาสตร์เกษตรดินปุ๋ย

#ศาสตร์เกษตรดินปุ๋ย : ขอบคุณแหล่งข้อมูล : หนังสือพิมพ์ The Nation

https://www.nationthailand.com/business/30384461?utm_source=category&utm_medium=internal_referral

White House, Democrats scramble to assemble massive spending packages as coronavirus fallout worsens

Mar 20. 2020
File photo of Treasury Secretary Steven Mnuchin / Syndication Washington Post

File photo of Treasury Secretary Steven Mnuchin / Syndication Washington Post
By The Washington Post · Jeff Stein, Mike DeBonis, Erica Werner · NATIONAL

Treasury Secretary Steven Mnuchin on Thursday said the Trump administration is working on a plan that would send most Americans $1,000 within three weeks and an additional $500 for every child as a way to flood the country with money and try to blunt the coronavirus pandemic’s impact on the U.S. economy.

Mnuchin, speaking on Fox Business, said a second round of payments for the same amount could be sent within the next six weeks if the crisis continued. The White House’s urgency has intensified as economic forecasts have become increasingly gloomy. A J.P. Morgan Chase analyst forecast that the U.S. economy could shrink by 14% between April and June, which would mark the worst quarterly contraction since World War II.

Mnuchin’s comments are part of the rapidly evolving fiscal stimulus plan that the White House and congressional leaders are scrambling to assemble amid growing signs that large parts of the economy are grinding to a halt. House Democrats, meanwhile, are working on their own set of proposals, and negotiations with the White House are expected to begin very soon.

The White House until several days ago had sought to pass a large tax cut measure to try and boost the amount of money people took home, but that idea was panned by lawmakers from both parties and seemed ineffective given an expected spike in unemployment. So this week the White House shifted to a goal of sending cash payments to many Americans, as quickly as possible.

The Treasury Department has estimated that such an approach could cost $500 billion and serve as a large part of their $1 trillion economic rescue package it wants Congress to authorize immediately. They also are proposing helping small businesses obtain funding in a way that avoids mass layoffs, creating an emergency lending facility for airlines, and providing liquidity to another range of firms that have been hammered by cancellations and closures.

But many parts of the White House’s approach remain in flux, and lawmakers from both parties are debating a number of different ideas.

Some Republican senators want to cap the payments to prevent taxpayers who earn over $75,000 annually from receiving the checks, according to two people aware of the GOP’s internal negotiations, who cautioned the talks were fluid and the numbers could change. And some other Republican senators want to substitute enhanced unemployment benefits or small business payroll assistance for at least some of the direct cash assistance Mnuchin has proposed.

Mnuchin and Trump initially suggested the money could reach American taxpayers within two weeks, although Mnuchin on Thursday suggested it would take three.

“Most people, we have their information,” Mnuchin said, suggesting the money could be directly deposited in consumers’ bank accounts.

House Democrats, wary of being sidelined as a potential trillion-dollar stimulus bill is negotiated between the White House and Senate Republicans, are trying to assert their power by proposing their own sweeping coronavirus economic rescue package in the coming days.

But Democrats have their own issues to work through — including how to put their own stamp on what is emerging as the centerpiece of the Republican-led plan being drafted in the Senate that could be unveiled as soon as Thursday: an estimated $500 billion plan to deliver checks directly to Americans over the next 90 days.

Tensions over the shape of the package emerged in a conference call Wednesday of House Democratic leaders and committee chairmen.

House Majority Whip James Clyburn, D-S.C., and Financial Services Committee Chairwoman Maxine Waters, D-Calif., argued for outgunning Republicans on the size of the cash payments, according to three participants on the call.

Waters, for instance, circulated a plan Wednesday calling for $2,000 per adult and $1,000 per child monthly stipend until the crisis abates.

But other Democrats — including Speaker Nancy Pelosi — while not ruling out direct payments, urged a more balanced course. Multiple committee chairmen argued that beefing up existing safety net programs — such as unemployment insurance and Medicaid, as well as small business assistance, would provide more targeted and effective relief.

All Democrats on the call, according to the participants, agreed that any cash payments should be means-tested to exclude the wealthiest Americans, a sentiment the White House appears to share.

In a letter to fellow Democrats late Wednesday, Pelosi alluded to the debate as “ongoing discussions in our Caucus on how to put money quickly in the hands of Americans.”

“Our Chairs are suggesting ways which are structural,” she wrote. “For example, solutions include expanding eligibility for Unemployment Insurance which will expedite financial relief for more people. In terms of helping small businesses, solutions include funds to ensure that workers continue to be paid. Refundable tax credits including the [Earned Income Tax Credit] and the child tax credit continue to be priorities as Members discuss other cash payments in the days ahead.”

But to many Democrats, discussions revolving around esoteric subjects like refundable tax credits are both insufficient in the face of a national crisis and a political loser when compared to the relatively easy-to-grasp concept of a check to every household.

“I think members are really just concerned about, what’s the fastest way to go?” said one House Democrat, who spoke on the condition of anonymity to frankly describe conversations with colleagues.

Regardless of the cash-payments debate, House Democrats are eager to insert themselves in the debate after taking a lead role in shaping the second round of coronavirus pandemic response, which was passed by the Senate and signed by President Trump Wednesday.

House members left Washington after passing the second-round bill early Saturday morning, leaving the Capitol to the Senate this week as House Democrats try to do their business through emails and conference calls. The House’s operations were further thrown into disarray Wednesday after two members announced they had tested positive for covid-19, while several others who came in contract with them chose to self-quarantine.

Schumer and Senate Democrats have released a framework of their own — a $750 billion package that prioritizes a “medical surge,” federal funding for child care and a emergency liquidity for small businesses. Much of the bill is devoted to existing safety net programs — not cash payments.

But payments have backing among Senate Democrats, too — notably, a proposal from Sens. Michael Bennet (Colo.), Cory Booker (N.J.) and Sherrod Brown (Ohio) that would put an immediate $2,000 into the hands of every American adult and child, with more possibly to follow.

As layoffs skyrocket, America’s unemployment safety net is underprepared to help many in need #ศาสตร์เกษตรดินปุ๋ย

#ศาสตร์เกษตรดินปุ๋ย : ขอบคุณแหล่งข้อมูล : หนังสือพิมพ์ The Nation

https://www.nationthailand.com/business/30384464?utm_source=category&utm_medium=internal_referral

As layoffs skyrocket, America’s unemployment safety net is underprepared to help many in need

Mar 20. 2020
Veteran Sean McGuire was laid off Monday from his job as a dishwasher at a restaurant in Portland, Ore. He spent hours trying to apply for unemployment insurance, only to learn that he does not qualify. MUST CREDIT: photo for The Washington Post by Leah Nash.

Veteran Sean McGuire was laid off Monday from his job as a dishwasher at a restaurant in Portland, Ore. He spent hours trying to apply for unemployment insurance, only to learn that he does not qualify. MUST CREDIT: photo for The Washington Post by Leah Nash.
By The Washington Post · Heather Long, Abha Bhattarai · NATIONAL, BUSINESS

WASHINGTON – American workers are getting laid off at an unprecedented pace as the coronavirus outbreak shuts down much of the economy, and the government safety net to help the newly jobless appears ill-equipped to handle the surge in the unemployed.

More than a million workers are expected to lose their jobs by the end of March, economists say, a dramatic turnaround from February when the unemployment rate was near a record low. Ball State University economist Michael Hicks predicts this month could be the worst for layoffs in U.S. history.

The Labor Department reported Thursday that 281,000 people applied for jobless benefits last week, up 33% from the prior week. Economists say it’s only going to get worse. New York restaurateur Danny Meyer’s Union Square Hospitality Group let 2,000 workers go this Wednesday. Pebblebrook Hotel Trust, which oversees 54 hotels, laid off 4,000 employees Tuesday. MGM Resorts and Caesars have begun letting staff go, along with countless smaller restaurants, bars, gyms and coffee shops.

The surge is straining state unemployment offices, which deliver benefits to the jobless so they can buy food and pay rent. On Monday, there were so many people trying to file for unemployment insurance in New York, Oregon and elsewhere that the websites crashed. Newly laid off workers waited hours on poorly staffed phone lines, they said.

As Americans turn to unemployment insurance, some are finding they don’t qualify. Or if they do, the average payment of $385 a week is modest. In some states, there’s a week-long waiting period before the first payment arrives.

“Workers expect unemployment insurance to be there for them in a downturn. A bunch of workers are about to find out that it’s not,” said Martha Gimbel, a labor economist at Schmidt Futures who was formerly at Indeed.com. “This is a real-life nightmare. Every hole we allowed to grow in our social safety net is hitting us all at once.”

Sean McGuire lost his job as a dishwasher at a popular Portland, Ore., brunch spot on Monday. The restaurant owners gave him brisket, onions and an apology. He spent the rest of the day trying to apply for unemployment, only to be turned down.

“I was on hold with the Oregon Department of Labor for over an hour. They were inundated,” said McGuire, a 30-year-old Army veteran who served in Iraq a decade ago. “When I finally spoke to a person, they told me I don’t qualify.”

McGuire moved to Oregon on Jan. 1, but he hasn’t worked long enough in the state to receive benefits. He tried to apply in New York, where he previously worked, but the website crashed. After another long wait on the phone, he was told he had not met the requirements there, either, because he quit a previous job. Most states require at least six months of work to qualify for any benefits. Now he’s worried about paying his $1,200 monthly rent on a short-term Airbnb through June.

Many of the newly jobless haven’t been able to file for unemployment benefits yet because the Web portals in their states are down. The problems are exacerbated by low staffing levels at state unemployment offices that didn’t expect such a surge any time soon. In mere weeks, the pandemic is on track to usher in a magnitude of unemployment that took months to reach during the Great Recession.

In Seattle, Ian Vermeers was laid off from his job at a Regal Cinemas movie theater on Monday. He’s been staying up all night to submit his application online and by phone – to no avail.

“I figured maybe things would get better in the middle of the night, but it’s 8 a.m. now and I still haven’t gotten through,” he said Wednesday. “Every time, I’m immediately hit with, ‘Sorry, our system is not working right now.'”

Many economists are urging Congress to quickly boost funding for state unemployment insurance. The Families First Coronavirus Response Act that President Donald Trump signed Wednesday included $1 billion to help states with administrative costs of processing unemployment insurance, but additional stimulus will be needed to cover more people. Twenty-three states were already running low on money in their unemployment trust funds before the pandemic hit.

Congress also has the power to increase the amount of unemployment dollars laid off workers receive and to extend benefits to self-employed and “gig” workers, as happens during natural disasters. Sixteen states have such restrictive criteria that fewer than 20% of laid off workers in the state are able to get unemployment benefits, according to the left-leaning Center on Budget and Policy Priorities.

“I’m terrified that states aren’t recession-ready anymore,” said Michele Evermore, senior policy analyst at the National Employment Law Project. “States have reduced the amount of benefits and access to benefits in a way that means that very few people can apply for unemployment insurance and receive it.”

Contractors, tipped workers, full-time students and undocumented workers often do not qualify for unemployment benefits, labor advocates said. Waiters and hotel staff who lose jobs are especially vulnerable, because they tend to move jobs frequently and rely on tips – factors that states handle differently. Plus, many states require applicants to prove they are searching for full-time work, although a few states including Texas have begun waiving the requirements.

Shawna, an exotic dancer who spoke on the condition she be identified only by her first name, found out Monday by text message that she would be out of work for at least two weeks. Unlike the bartenders and bouncers who work with her at a gentlemen’s club near Philadelphia, she does not qualify for unemployment insurance because she is a contractor.

She used to make $1,300 in a good week. Now the 31-year-old isn’t sure how she’ll be able to pay her rent or afford food without a steady income.

“The whole system is set up in a really bad way for us,” she said. “We are completely on our own right now.”

So far, the wave of coronavirus-related layoffs has disproportionately hit service workers in typically lower-paying jobs. Many lack adequate savings and say they don’t know where to turn as restaurants, bars, cafes and shops across the country shut their doors indefinitely.

Nellie Hana, a full-time student and line cook at an Olive Garden in Buffalo, New York, said managers this week told kitchen staff they had a choice: They could be laid off and file for unemployment, or they could keep working five hours a week processing to-go orders.

For Hana, unemployment wasn’t an option. Full-time students don’t typically qualify for unemployment benefits. She chose to keep working, even though that means her $600-a-week job will now bring in less than $70 each week.

“I have no choice but to wait this out,” said Hana, 20, who is majoring in media production at SUNY Buffalo State College. “I have student loans and bills to pay. Rent is coming up. Past that, I don’t know how I’m going to eat.”

Rich Jeffers, a spokesman for Olive Garden’s parent company, Darden Restaurants, said the company has not laid off any employees, though many restaurant workers have had their hours reduced to zero, as mayors and governors order dining rooms to close. The company, he said, is providing emergency pay of up to two weeks to affected employees.

For workers, one of the most frustrating aspects is the uncertainty. No one knows how long the pandemic and near-lockdown of the economy will last, and some workers have found themselves in limbo – not technically laid off, but also not getting paid.

Several big companies, such as Marriott International, are furloughing tens of thousands of workers. Halliburton announced furloughs of 3,500 employees at its Houston campus starting next Monday, because of the huge hit to oil prices this month. Furloughs allows workers to keep their health-care benefits, though they have no income coming in.

American Eagle is among a growing number of retailers closing its stores through late March. The company has pledged to pay employees for the hours they are scheduled in coming weeks. But an employee in a New York store said managers recently scrapped the original schedule and created a new one that only includes managers, which means she – and the majority of her co-workers – won’t be paid.

“I’ve worked up to 40 hours a week for more than three years,” said the employee, who spoke on the condition of anonymity because she feared retribution at work. “I’ve never received zero hours. I don’t know what to do.”

American Eagle didn’t return a request for comment.

Workers whose hours are severely reduced are supposed to be eligible for partial unemployment benefits, but state rules vary, and workers often have to file an appeal if an initial claim is denied.

One proposal in the works that could help the unemployed is a move backed by the White House to send $1,000 checks directly to workers, possibly twice. That’s just a small comfort for McGuire, however, who made more washing dishes in Portland.

“If you’re in a major city, that $1,000 doesn’t pay your rent, let alone health care, transportation and food,” he said. “My financial situation is in complete disarray.”

Weaker outlook for Thai economy amid further deterioration #ศาสตร์เกษตรดินปุ๋ย

#ศาสตร์เกษตรดินปุ๋ย : ขอบคุณแหล่งข้อมูล : หนังสือพิมพ์ The Nation

https://www.nationthailand.com/business/30384440?utm_source=category&utm_medium=internal_referral

Weaker outlook for Thai economy amid further deterioration

Mar 20. 2020
By The Nation

Thailand’s economy shows no signs of a turnaround. The coronavirus outbreak has dealt a further blow to activities, and the consumer confidence index declined in February to the lowest level since April 1999. Domestic financial markets, even bond markets, continue sell off, said Tim Leelahaphan, economist at Standard Chartered Bank (Thai).

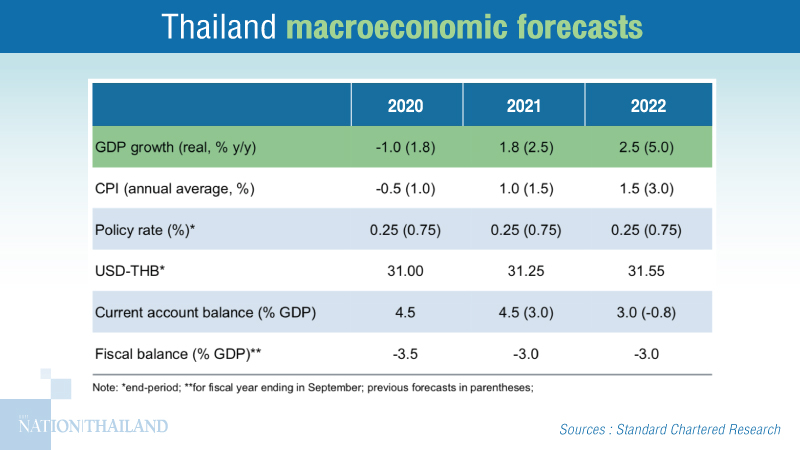
“The bank has sharply lower our 2020-22 GDP growth forecasts to reflect the worsening coronavirus outbreak – both globally and domestically – and our recent downward revisions for China, the US and the euro area as we are expecting recessions in the US and euro area).

We now forecast Thai GDP growth at -1.0 per cent this year, versus +1.8 per cent previously, with Q1 growth at -3.0 per cent year on year. We expect a return to positive growth in 2021-22, but at lower levels: 1.8 per cent in 2021, compared to 2.5 per cent previously, and 2.5 per cent in 2022 from the previous projection of 5 per cent,” said Tim.

The bank also lowers  inflation forecasts for the 2020-22 period to reflect economic weakness and low oil prices, expecting average CPI inflation of – 0.5 per cent in 2020 (1.0 per cent previously), 1.0 per cent in 2021 (1.5 per cent previously) and 1.5 per cent in 2022 (3.0 per cent previously).

Tim  expects a substantial current account (C/A) surplus of 4.5 per cent in 2020, but now expects larger surpluses in the subsequent years due to lower imports amid a slowing economy, lower oil prices and a strong expected recovery in inbound tourism.” We revise up our 2021-22 C/A forecasts to 4.5 per cent of GDP (from 3.0 per cent ) and 3.0 per cent (from -0.8 per cent ),” said Tim.

External accounts to remain strong

The timing of the tourism recovery is difficult to predict, but we now expect it to be delayed beyond Q2/2020. The latest data from the Tourism Authority of Thailand (for February) shows that arrivals plunged 44.3 per cent year on year; arrivals from China fell 85.3 per cent. The Songkran (Thai New Year) festivities in April have been called off, and the granting of visas on arrival or visa exemptions for a total of 21 countries has been cancelled until the situation improves. However, the government has said it may consider classifying China as less risky as the rate of new cases there has moderated, according to a Bloomberg report.

Current low oil prices will support the C/A surplus given Thailand’s status as a net commodity importer. In addition, we do not see a large increase in investment-related imports in the foreseeable future. The current government appears to be focused on providing a short-term boost to the economy via private consumption rather than reviving investment, according to the bank.

Fiscal policy needs to step up

We expect fiscal deficit forecasts of -3.5 per cent of GDP for 2020 and -3.0 per cent for both 2021 and 2022. The Cabinet has approved phase one of a Covid-19 stimulus package combining tax benefits, soft loans for businesses and relief measures for households, but without additional spending. These measures are expected to inject about Bt400 bn (2.4 per cent of GDP) into the economy, according to the Fiscal Policy Office (FPO); we think the impact will depend on private-sector take-up of the measures.

While these measures have provided an initial boost to sentiment, they may have a limited impact on private consumption or the economy as a whole. We believe more effective fiscal spending is needed – particularly in the form of public infrastructure investment – before the private sector will respond. A personal income tax cut could be more effective; the Palang Pracharath Party, the biggest party in the government coalition, promised such a cut as part of its election campaign. However, this might not materialise soon, as the Finance Ministry has indicated that it would be reluctant to reduce a steady source of revenue.

Politics: Potential risk

Political noise is rising, even if risk remains low. Students and supporters of the now- defunct Future Forward Party (FFP) have held small protests and gatherings since 21 February, when the Constitutional Court ruled to dissolve the opposition party for violating election laws. The bank does not see a significant risk that this will escalate into street protests at this stage, as coronavirus concerns are likely to deter large gatherings.

Monetary policy

Tim expects the Bank of Thailand (BOT) to deliver a 25 basis point rate cut at its scheduled meeting on March 25, taking the policy rate to a new low of 0.75 per cent. Given recent decisions by other central banks, we do not rule out an intermeeting move prior to March 25, or a deeper cut of 50 basis points . In line with the downgrades to our economic outlook, the bank now sees the policy rate being cut further by 25 basis points each in Q2 and Q3, taking the rate to a record-low 0.25 per cent at end of this year.

However, the BOT faces limitations on its ability to be as dovish or aggressive as other central banks. Further deep cuts without a clear positive impact or the desired market response could risk complicating the BoT’s monetary policy-making ability. Policy rates below 0.5 per cent could create transmission difficulties, with banks unable to match the BOT cut, given their mandatory contribution to the bailout fund as the central has yet to announce an adjustment to the contribution, he said.

At this stage, the Standard Chartered bank expects the central bank to provide assurances that policy will remain accommodative for as long as needed, along with verbal intervention in the FX market, though this is not needed given current under-performance of the baht and liquidity measures. “In this context, we believe fiscal policy needs to do more of the heavy lifting to support the economy and avoid the need for zero or negative interest rates; fiscal stimulus measures announced so far appear to have had limited effectiveness, according the bank.

Australia joins QE club as first recession in 29 years looms #ศาสตร์เกษตรดินปุ๋ย

#ศาสตร์เกษตรดินปุ๋ย : ขอบคุณแหล่งข้อมูล : หนังสือพิมพ์ The Nation

https://www.nationthailand.com/business/30384455?utm_source=category&utm_medium=internal_referral

Australia joins QE club as first recession in 29 years looms

Mar 19. 2020
By Syndication Washington Post, Bloomberg · Michael Heath · BUSINESS, WORLD, ASIA-PACIFIC

Australia’s central bank joined the international fold with the announcement it will enter the government bond market to lower yields, having exhausted its remaining conventional policy ammunition.

Reserve Bank Governor Philip Lowe’s unconventional approach set out Thursday after an emergency meeting differs from his European and U.S. counterparts, who pledged to buy a certain amount of government securities to keep yields down. Instead, he’ll aim to keep three-year government bond yield at 0.25%.

Lowe also cut the cash rate to 0.25%, a level he has nominated as the effective lower bound, noting it wasn’t a coincidence that policy makers in the U.S., New Zealand and the U.K. all eased to the same level. Similarly, in line with other central banks, the RBA governor set out forward guidance by saying he expects to remain on hold for “some years.”

Australia’s economy is spiraling toward its first recession since 1991 and its credit markets are under stress from investors worldwide trying to head for the exits. In a speech after the policy announcement, Lowe didn’t try to sugar coat the months ahead, saying “we are expecting a major hit to economic activity and incomes in Australia that will last for a number of months. We are also expecting significant job losses.”

Qantas Airways on Thursday furloughed most of its 30,000-strong workforce and scrapped all international flights.

The RBA also announced a term funding facility of at least A$90 billion ($50 billion) for the banking system, with particular support for credit to small and medium-sized businesses.

In a complementary program, Australia’s government will invest up to A$15 billion to allow smaller lenders to support consumers and smaller businesses during the coronavirus outbreak, according to a statement from the treasurer. Prime Minister Scott Morrison is also developing a follow-up spending package to expand on the A$17.6 billion program announced last week.

The combined fiscal-monetary salvo aims to keep firms open and workers in jobs.

Australia now finds itself in uncharted territory: The country was a poster-child for its response to the 2008-09 financial crisis and worldwide downturn. It deployed a combination of fiscal and monetary policy that allowed the economy to escape the recession that enveloped most of the developed world, without ever adopting unorthodox monetary policies.

Prime Minister Kevin Rudd’s administration had been in office less than a year when credit markets seized up. The government put together two packages worth more than 4% of GDP and the central bank cut interest rates by 425 basis points. Andrew Charlton was Rudd’s chief economic adviser at the time and ran point on the fiscal stimulus.

“The key feature of the Australian response to the global financial crisis was speed and size,” said Charlton, now director of consultancy AlphaBeta in Sydney. “We wanted to use our fiscal firepower to keep the economy going, not to restart it after it had stalled.”

It’s a similar approach today.

In a speech explaining Thursday’s moves, Lowe said the board expects “the cash rate will remain at its current level for some years, but not forever.” Lowe said he expects that the yield target will be removed before the cash rate is increased, once the economy improves.

In a move to relieve the margin squeeze facing banks, the RBA said it’ll pay lenders 10 basis points on funds deposited with it overnight, rather than the usual 25 basis point discount to the cash rate. It’s trying to avoid the type of stress banks in Japan and Europe have faced in a low-rates world.

By targeting a flat yield curve over three years, the RBA is hoping to put more cash into the pockets of households that tend to have variable mortgage rates. It’s also seeking to lower borrowing costs so businesses will be tempted to expand again once the worst of the virus shutdown passes.

By saying it’ll also buy semi-government securities, the RBA aims to avoid a blow out in yields on state government debt relative to commonwealth bonds. It will make purchases “across the yield curve” to achieve its target and avoid dislocations.

The yield on Australian government three-year bonds tumbled after the policy statement and traded about 16 basis points lower at 0.34% as of 6:38 p.m. in Sydney. The Aussie dollar is trading higher from intra-day lows of 55.10 U.S. cents at 56.68 U.S. cents.

Lowe noted the Australian dollar had come down “a reasonable amount.” “Liquidity is thin, but it hasn’t been to a point where we needed to intervene, but we are prepared to if liquidity conditions deteriorate,” he said in response to a question.

Australia’s credit markets have been stressed and the RBA has been pumping liquidity into the financial system in recent days to help calm them.

Lowe said the timing and strength of the economy’s recovery after the virus depends “in part upon how successful we are, as a nation, in building that bridge to the other side.” Ever the optimist, he pointed out that Australia has “fantastic” fundamentals.

Oil rollercoaster has crude rebounding after drop to 18-year low #ศาสตร์เกษตรดินปุ๋ย

#ศาสตร์เกษตรดินปุ๋ย : ขอบคุณแหล่งข้อมูล : หนังสือพิมพ์ The Nation

https://www.nationthailand.com/business/30384451?utm_source=category&utm_medium=internal_referral

Oil rollercoaster has crude rebounding after drop to 18-year low

Mar 19. 2020
By Syndication Washington, Bloomberg · Sharon Cho, Alex Longley · BUSINESS, US-GLOBAL-MARKETS 

Oil rebounded after plunging to the lowest level in 18 years as policymakers across the globe try to strengthen economies against the impact of the coronavirus pandemic.

Futures rose as much as 18% in New York, the most since December 2008, following a 24% rout in the previous session. Prices have cratered over the past two weeks as major producers hike output in a fight for market share while demand plummets. Signs of stress are already showing in some corners of the world with Canadian oil at a record low and some North Sea fields becoming uneconomic.

The European Central Bank has unleashed an emergency bond-buying program, while the Senate cleared the second major bill responding to the outbreak in an attempt to kickstart the economy. White House economic adviser Larry Kudlow said the government might take equity positions as part of corporate rescues.

Countries are ramping up measures as the global spread of the virus continues to gather pace with the number of confirmed cases in Europe now exceeding China. Italy’s death count has surged to almost 3,000, while the U.K. imposed tighter controls on movement of people including closing all schools.

“We are heading into the most oversupplied market in the history of the oil market,” said DNB Bank senior analyst Helge Andre Martinsen. “We might hit full utilization of global oil inventories in the months to come.”

As the world’s biggest oil producers boost supply, Rep. Sen. Kevin Cramer of North Dakota called on President Donald Trump to ban crude imports from Russia, Saudi Arabia and other OPEC members in response to recent action taken by them to “distort energy markets” when demand is already weak.

The Saudis ordered state-run Aramco to keep output at a record high of 12.3 million barrels a day over the coming months. But in a surprise move Thursday, both Saudi Arabia and Iraq cut the rebates on freight costs they give to customers, effectively lifting prices.

See also: Some Oil in Canada Has Already Tumbled Below $10 a Barrel

The higher supply is increasingly taking its toll on the oil market’s structure. Brent’s six-month timespread is currently at its most bearish since 2009, indicating a big glut. As a result, traders are eying lucrative opportunities from storing oil on tankers and hoping to sell it at a profit later.

With crude’s price weakness getting more entrenched, traders are increasingly trying to assess the impact on U.S. production this year. On Thursday, a barrel of Permian oil was cheaper than a meal at a steakhouse in the region’s Midland heartland, a sign that producers are struggling to cover their operating costs.