Gold price falls amid uncertainty caused by Covid-19 and strengthening dollar #ศาสตร์เกษตรดินปุ๋ย

#ศาสตร์เกษตรดินปุ๋ย : ขอบคุณแหล่งข้อมูล : หนังสือพิมพ์ The Nation

https://www.nationthailand.com/business/30384404?utm_source=category&utm_medium=internal_referral

Gold price falls amid uncertainty caused by Covid-19 and strengthening dollar

Mar 19. 2020
By The Nation

The price of gold dropped by Bt400 per baht weight on Thursday morning (March 19), the Gold Traders Association reported.

Buying price of a gold bar was Bt22,700 per baht weight and selling price Bt22,800, while buying price of gold ornaments was Bt22,285.20 per baht weight and selling price Bt23,300.

The prices dropped from Wednesday’s close (March 18) when buying price of a gold bar was Bt23,100 and selling price Bt23,200, while buying price of gold ornaments was Bt22,679.36 and selling price Bt23,700.

Gold contracts in COMEX futures to be delivered in April dropped by US$47.90 to $1,477.90 per ounce on Wednesday’s close as investors sold gold to hold cash amid uncertainty following impacts from the Covid-19 outbreak.

Also, gold price was under pressure from the strengthening dollar, making the gold contract price more expensive for investors who hold other currencies.

US President Donald Trump said that he would hold a press conference on Thursday about “the most important issue” from the US Food and Drug Administration relating to Covid-19.

The latest information from Johns Hopkins University stated that currently, the number of Covid-19 infected people worldwide was 201,436, while the death toll was 8,007.

In the US, 6,496 people have been infected and 114 people have died.

SET continues slide as global recession looms #ศาสตร์เกษตรดินปุ๋ย

#ศาสตร์เกษตรดินปุ๋ย : ขอบคุณแหล่งข้อมูล : หนังสือพิมพ์ The Nation

https://www.nationthailand.com/business/30384402?utm_source=category&utm_medium=internal_referral

SET continues slide as global recession looms

Mar 19. 2020
By The Nation

The Stock Exchange of Thailand (SET) Index on Thursday (March 19) morning dropped by 32.41 points, or 3.09 per cent, to 1,015.74.

A stock analyst at Krungsri Securities expected the index to slide to between 1,020 and 1,030 before rebounding.

“Investors are still under pressure due to uncertainty following the rapid spread of Covid-19 that would cause a global economic recession and the decline in crude oil price to the lowest point in 18 years, which would cause a negative sentiment for energy and petroleum stocks,” the stock analyst said.

The analyst expected the index to rebound due to positive sentiment from the European Central Bank (ECB), which announced it would buy assets with a limit of 750 billion euros to deal with the economic impact from Covid-19.

“In addition, the US Senate has approved the Families First Coronavirus Response Act with a limit of US$1 trillion to mitigate the impact of Covid-19,” the stock analyst said.

“Moreover, Thailand’s Ministry of Finance is prepared to propose additional measures to take care of people and businesses affected by the Covid-19 impact to the Cabinet next week.”

The analyst recommended three groups of stocks for investors:

● Defensive stocks which pay high dividends, such as ADVANC, INTUCH, and TTW.

● Retail stocks, which gained buying power after the government returned Bt30 billion electricity metre insurance, such as CPALL, HMPRO, and BJC.

● Financial stocks, which gained from interest rate cuts, such as MTC, SAWAD, and KTC.

Negotiations intensify on Capitol Hill over massive stimulus legislation as coronavirus fallout worsens #ศาสตร์เกษตรดินปุ๋ย

#ศาสตร์เกษตรดินปุ๋ย : ขอบคุณแหล่งข้อมูล : หนังสือพิมพ์ The Nation

https://www.nationthailand.com/business/30384392?utm_source=category&utm_medium=internal_referral

Negotiations intensify on Capitol Hill over massive stimulus legislation as coronavirus fallout worsens

Mar 19. 2020
Photo by: The Washington Post — The Washington Post

Photo by: The Washington Post — The Washington Post
By The Washington Post · Erica Werner, Jeff Stein, Mike DeBonis · NATIONAL, BUSINESS, POLITICS, CONGRESS, WHITEHOUSE, PERSONAL-FINANCE, US-GLOBAL-MARKETS

WASHINGTON – The Trump administration and congressional leaders rushed on Wednesday to assemble a massive stimulus package aimed at preventing the U.S. economy from plummeting into its worst collapse since the Great Depression, as fears about the coronavirus pandemic brought much of American life to a standstill.

The administration’s $1 trillion proposed rescue plan, which forms the basis for fast-moving negotiations on Capitol Hill, includes sending two large checks to many Americans and devoting $300 billion toward helping small businesses avoid mass layoffs. Priorities laid out in a two-page Treasury Department document also include $50 billion to help rescue the airline industry and $150 billion to prop up other sectors, which could include hotels.

The White House is vetting these proposals with Senate GOP leaders before engaging more fully with Democrats, so the package is certain to evolve in coming days.Democrats, meanwhile, are eyeing their own priorities, largely aiming to shore up safety net programs and the public health infrastructure, as well as send money directly to American taxpayers, while shunning corporate bailouts. Rep. Maxine Waters, D-Calif., proposed on Wednesday having the Federal Reserve send $2,000 to every American adult and $1,000 to every American child until the crisis ends.

The emerging government stimulus package could be unprecedented in its size and velocity, dwarfing the $800 billion stimulus law passed during the Obama administration and the $700 billion Troubled Asset Relief Program enacted during the Bush administration. All told, between several legislative packages advanced on Capitol Hill and other actions the government has taken, the White House is pushing an economic plan that is “over $2 trillion and counting” to try to arrest the coronavirus’s economic wrecking ball, a senior administration officials said. The official spoke on the condition of anonymity to reveal details of the planning.

The Dow Jones industrial average fell 1,338 points on Wednesday, or 6.3 percent, virtually wiping out all of the stock market’s gains during Trump’s entire presidency. Trump told reporters Wednesday that under a “worst case scenario,” the unemployment rate could jump to 20 percent, twice its peak from the financial crisis. A JPMorgan Chase research note predicted the economy would shrink by 14 percent between April and June, the worst contraction in Post-World War II history.

“People want to go big,” Trump said at a news conference when asked about the size of the direct payments to Americans. “Everybody seems to want to go big and they want to get to the recovery.”

The global impact of the virus continued to skyrocket. Italy’s coronavirus death toll increased by 475 on Wednesday, the largest daily increase recorded in any country. New York state, meanwhile, has roughly 2,500 confirmed cases, more than all but 10 countries in the world.

As the U.S. government continued to scramble and escalate its response, Trump ordered Navy hospital ships to states on the coasts. The U.S. and Canada agreed to close its entire border to “nonessential travel,” and Ford and GM announced they would temporarily cease production at their North American plants. A growing number of business groups are petitioning the White House and Congress for economic relief as the total number of U.S. cases approached 8,000.

“The concentration of this drag at its most intense is far bigger than during the 2008 financial crisis,” said Bruce Kasman, managing director and Head of Economic Research at JP Morgan Chase.

The Senate on Wednesday also voted to approve a House-passed bill that would spend some $100 billion on paid leave, unemployment insurance, and free testing to people impacted by the coronavirus fallout. That vote sends the legislation to Trump for enactment. That followed the passage of another law earlier this month of an $8.3 billion emergency spending package for the public health system.

But attention on Capitol Hill was focused on the next step, as lawmakers faced the need for urgent action to pass a major stimulus bill to stabilize the economy before they, too, are forced to abandon work. Hanging over the Capitol was the threat of coronavirus infections that have already reached into Congress with several congressional aides infected and a number of lawmakers announcing voluntary self-quarantine after coming into contact with infected individuals.

Wednesday evening brought news of the first lawmaker to contract the disease: Rep. Mario Diaz-Balart, R-Fla., who said he’d been notified that he had tested positive after developing symptoms Saturday, but was already feeling better.

Senate Majority Leader Mitch McConnell, R-Ky., announced a new process for voting Wednesday aimed at lengthening the time for votes so senators don’t congregate in the well of the Senate. He urged his members to prepare to act.

“I want to repeat, again, the Senate’s going to stay in session until we finish phase three, the next bill, and send it over to the House. Republicans hope, shortly, to have a consolidated position along with the administration and we intend to sit down with our Democratic colleagues, see what we can agree to,” McConnell said on the Senate floor. “I would recommend senators stay around, close. Just how long it will take to get through these steps is unclear, but as everyone knows we are moving rapidly because the situation demands it.”

The new $1 trillion Trump plan would seek to spend $500 billion toward the cash payments to individual Americans, though some people wouldn’t qualify if their income is over a certain level. The Treasury Department outline says the funds would be paid out in two equal amounts, beginning on April 6 and then again on May 18. White House officials have eyed making each check $1,000, but those talks remain ongoing and the amount could grow.

The White House discussions with Republicans would aim to spend another $50 billion to help rescue the airline industry and $150 billion to prop up other sectors, which could include hotels, among others. Some Democrats have raised concerns about how these funds might be used and have called for putting restrictions on firms that receive emergency assistance to assure that employees aren’t laid off while executives pocket large bonuses. The Treasury proposal suggests an “airline industry secured lending facility” that would allow it to make direct loans to “U.S. passenger and cargo air carriers.”

Treasury would determine the interest rates and other terms of any loans, but they would include limits “on increases in executive compensation until repayment of the loans.”

Trump said Wednesday that the exact sums were in flux as negotiations progressed on Capitol Hill.

“We’re coming up with numbers. Haven’t gotten there yet, but certainly the hotel industry, cruise ship industry, the airlines — those are all prime candidates,” said Trump. It’s unclear if the president’s own hotels could stand to benefit from any such bailout.

Republicans were on Wednesday trying to resolve internal divisions over the direct checks proposal and other parts of the administration’s request. Sen. Lindsey Graham, R-S.C., a skeptic of the payments, was working with Sen. Mitt Romney, R-Utah, on a potential compromise in which the funding for the second direct cash payment would instead be used to increase unemployment benefits, Romney told reporters.

Sens. Josh Hawley, R-Mo., and Rick Scott, R-Fla., have also criticized the push for industry bailouts, with Hawley echoing Democratic demands they must incorporate workers’ needs.

“If you’re coming to me and just saying, we just want a bunch of taxpayer money, just give it to us, I’m not going to do that,” Hawley told reporters.

Republican senators are also working out the details of the cash payment plan and whether the checks should be for more than $1,000, according to two people familiar with internal conversations. Administration officials have suggested $1,000 is a minimum for the proposed benefit payment.

Some Republicans said they were prepared to do what they had to, like it or not.

“The amount of spending, does it give everybody pause? A little bit. But you know what? It needs to be done,” said Sen. Joni Ernst, R-Iowa.

The approach being taken by McConnell and the administration of negotiating among themselves and then looking for Democratic buy-in irritated some Democrats. It stands in contrast to how the last coronavirus bill was negotiated, when McConnell stood on the sidelines as House Speaker Nancy Pelosi, D-Calif., worked directly with Mnuchin.

“It’s a totally partisan approach. … That, to me, sends absolutely the wrong signal to the American public that we’re actually trying to function and put the country first,” said Sen. Mark Warner, D-Va. Some bipartisan talks were already underway, though, as Sens. Marco Rubio, R-Fla., and Susan Collins, R-Maine, worked on small business provisions with Democratic colleagues.

One of the goals of the White House’s decision to seek $300 billion for small businesses in the plan would be to help firms continue paying employees, as there has already been a wave of layoffs, particularly at restaurants and other companies where business has suddenly halted.

These credits, which Treasury is calling “Small Business Interruption Loans,” would come with a 100 percent government guarantee. Eligible borrowers would have 500 or fewer employees, and the loan amounts would be targeted to finance six weeks of payroll, capped at $1,540 per week per employee. The loans would come from U.S. financial companies but would have U.S. government backing. The Treasury Department would have the power to issue regulations about interest rates and loan maturities.

The package doesn’t, at this point, include some of the big tax cuts that Trump had sought only a few days ago. White House officials pivoted away from the tax cuts after Democrats and Republicans largely panned the idea, and Trump expressed concern that it would take too long for these benefits to filter through to the economy.

The White House also sent Congress a separate emergency funding request for $46 billion for “ongoing preparedness and response efforts” to the coronavirus. This would include new funding for the Department of Defense, the Department of Veterans Affairs, the Centers for Disease Control and Prevention and the National Institute of Allergy and Infectious Diseases.
U.S. markets falls sharply as rampant volatility takes hold #ศาสตร์เกษตรดินปุ๋ย

#ศาสตร์เกษตรดินปุ๋ย : ขอบคุณแหล่งข้อมูล : หนังสือพิมพ์ The Nation

https://www.nationthailand.com/business/30384388?utm_source=category&utm_medium=internal_referral

U.S. markets falls sharply as rampant volatility takes hold

Mar 19. 2020
By The Washington Post · David J. Lynch, Thomas Heath, Taylor Telford · BUSINESS

Mounting signs of an unprecedented global economic contraction sent financial markets tumbling on Wednesday, with stocks closing at their lowest point since President Donald Trump’s second week in the White House.

The Dow Jones industrial average sank nearly 1,339 points or 6.3% to finish at 19,898.92. Both the broader Standard & Poor’s 500 index and the technology-laden Nasdaq lost about 5%. Trading at one point was halted for the fourth time in six sessions when stocks tripped a circuit-breaker designed to prevent panic selling.

Bond prices also fell, sending yields higher, and oil prices plunged to an 18-year low amid continued uncertainty over the duration of the coronavirus shutdown.

Even the prospect of roughly $1 trillion in emergency federal aid, including $1,000 checks for taxpayers and an airline industry bailout, was not enough to halt the retreat. Dire predictions about the global pandemic’s spread and its likely economic toll discouraged traders.

After growing without interruption since mid-2009, the U.S. economy will likely shrink in the second quarter at an annual rate of 14% – a staggering decline that exceeds the worst of the global financial crisis, according to economists at JPMorgan Chase. A sudden stop that began in China, where the virus originated, is now rippling through the U.S., Europe and vulnerable emerging markets, likely shrinking global output for the entire year.

Tomorrow’s Labor Department report of initial jobless claims is expected to show evidence of the first layoffs triggered by the pandemic. Ian Shepherdson, chief economist for Pantheon Macroeconomics, said he expects claims to reach 250,000 this week, up from 211,000 last week and to top 1 million next week.

“The thing that has me the most concerned is the speed and severity of what’s playing out here,” said Gibson Smith, a prominent bond fund manager with Denver-based Smith Capital Investors. “There’s just a lot of stress in the system.”

Indeed, markets for U.S. government and corporate debt strained to handle a flood of sell orders. Investors sold 10-year Treasury securities to raise cash, sending prices down and yields up to 1.2%. The 10-year yield has more than doubled since March 9, when stocks and bonds began plunging in tandem. Bond prices and yields move in opposite directions.

Treasurys have been whipsawed during the coronavirus pandemic as investors seeking a safe haven initially drove bond prices up and yields down, said Mark Heppenstall, chief investment officer of Penn Mutual Asset Management. In the past week, as institutional investors sought to raise cash by selling treasuries, prices sagged while yields jumped.

Some analysts said concern over Washington’s unprecedented spending plans, which will balloon the already swollen federal budget deficit and debt, were behind the latest moves.

“Global fixed income markets this morning have lost confidence in the ability of the governments of the world to finance the fiscal stimulus they are proposing,” Carl Weinberg, chief international economist for High-Frequency Economics, wrote in a note to clients. “Traders, investors and speculators have looked at the size and cost of the fiscal stimulus proposed by the United States and other governments – especially Italy – and decided to sell sovereign debt of all kinds.”

Investors said corporate debt markets also are not yet operating smoothly. Companies have taken advantage of record-low interest rates in recent years to load up on debt. That strategy worked well so long as short-term borrowings could be periodically refinanced.

Now, some cash-strapped companies that are not earning enough to make their loan payments may struggle to roll over their debt, said Anne Van Praagh, head of global credit strategy for Moody’s Investors Service.

Like most investors, Moody’s anticipates a wave of credit downgrades and corporate debt defaults. Energy companies hit by the abrupt oil price decline and businesses that are most exposed to the evaporation of consumer spending – such as airlines, hotels, cruises, and automakers – face the greatest risk.

“We’re going to go into a period of severe and extensive credit shock across many regions, sectors and asset classes,” she said. “This is unprecedented.”

Amid unpredictable day-to-day changes in market conditions, former Fed Chairs Janet L. Yellen and Ben Bernanke called for the central bank to begin purchasing high-quality corporate debt as part of its economic rescue efforts – something it has never before done.

“The Fed’s intervention could help restart that part of the corporate debt market, which is under significant stress,” the pair wrote in The Financial Times.

Meanwhile, the Dow’s plunge from its all-time high of 29,551 on Feb. 12 has eliminated one of the president’s favorite campaign arguments. As stocks soared since the 2016 election, Trump repeatedly took credit at campaign rallies and in White House remarks. He drew attention to the market setting all-time highs and boasted about the effect on voters’ investment accounts.

As late as Feb. 24, the president took to Twitter to talk up stock prices, tweeting: “Stock market starting to look very good to me.”

The Dow has lost more than 8,000 points since then.

Shares of Boeing, once the showcase of the bull market, closed just below $102, less than one-quarter of its March 2019 peak. Trump has pledged federal aid for the wheezing aerospace giant.

“If 2008 was the Great Financial Crisis, this is the Great Virus Crisis,” said Ed Yardeni, president of Yardeni Research. “It’s all at once a health crisis, financial crisis and economic crisis. We need to fix the health part of it before we have it solved, but we can take financial and fiscal steps to blunt its effects. We are starting to do that now.”

All three major U.S. stock indexes are in a correction, having declined beyond 20% from their highs.

The Dow marked its eighth straight day of 1,000-point swings, which was considered unthinkable until recently. Stocks are moving on every news conference, financial proposal, headline and medical utterance. The blue chips closed up more than 1,000 points Tuesday off news of a $1 trillion stimulus proposal from the White House.

But that gain was wiped out on Wednesday, as investors sold stocks despite extreme government intervention aimed at cushioning the economy against a coronavirus-fueled recession. The Federal Reserve began the week by slashing interest rates to near zero and reviving a financial crisis-era “quantitative easing program,” and on Tuesday the central bank announced plans for a special fund to keep credit flowing during the coronavirus outbreak.

“The longer the economy is in a deep freeze, the strain is only going to increase,” said Heppenstall. “There’s just so much uncertainty surrounding the coronavirus. It makes it hard for anyone to plan.”

European markets also tanked Wednesday as governments introduced sweeping, blank-check stimulus moves to prop up their economies, with the benchmark Stoxx 600 index closing down more than 4% as oil and gas stocks plunged. Germany, Spain and the United Kingdom have hurled hundreds of billions in rescue package funding at the virus. French President Emmanuel Macron went so far as to promise that no French company will be allowed to fail because of the coronavirus impact, saying the government would provide assistance through loans or delayed tax payments and even nationalize industries to keep them afloat.

Yields on Italian debt rose to 2.3%, roughly twice what they were less than one week ago.

“People are panicked,” said Nancy Tengler of Tengler Wealth Management. “If there’s too much stimulus, then the market take is things must be really bad. And if there’s not enough, then there’s no leadership. People are worst-case-scenario-ing it.”

Bids planned for Red Line extension project in June #ศาสตร์เกษตรดินปุ๋ย

#ศาสตร์เกษตรดินปุ๋ย : ขอบคุณแหล่งข้อมูล : หนังสือพิมพ์ The Nation

https://www.nationthailand.com/business/30384351?utm_source=category&utm_medium=internal_referral

Bids planned for Red Line extension project in June

Mar 19. 2020
By THE NATION

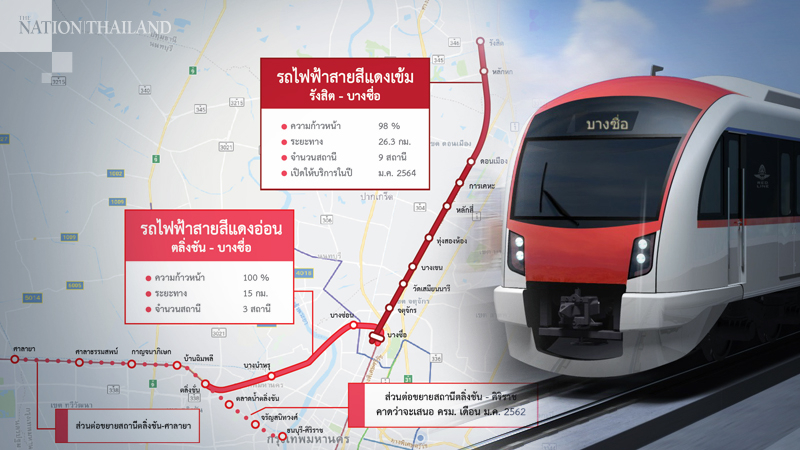
The State Railways of Thailand (SRT) is expected to call bids for the extension project of the suburban Red Line mass transit system in June, said acting governor Worawut Mala today (March 18), adding that the work will be split into three contracts.

The Bt21.6- billion project comprises the Rangsit-Thammasat University ( Rangsit campus) section costing Bt5.97 billion; the Talingchan-Siriraj Hospital section, Bt5.98 billion; and the Talingchan-Salaya sector worth Bt9.67 billion.

Start of construction is expected next year.

Meanwhile, construction of the Bangsue central station is expected to be completed in June while the Red Line mass transit system’s Bangsue-Rangsit section and Bangsue-Talingchan section with a total of 13 stations will commence commercial operations in January next year. Fares for the two routes will be from Bt15 to Bt50.

The state agency plans to set up a company to operate the Red Line routes. It will ask for Cabinet approval to borrow a loan of Bt3 billion as the company’s registered capital.

Banks told to step up relief efforts for borrowers #ศาสตร์เกษตรดินปุ๋ย

#ศาสตร์เกษตรดินปุ๋ย : ขอบคุณแหล่งข้อมูล : หนังสือพิมพ์ The Nation

https://www.nationthailand.com/business/30384353?utm_source=category&utm_medium=internal_referral

Banks told to step up relief efforts for borrowers

Mar 19. 2020
Central bank governor Veerathai Santiprabhob

Central bank governor Veerathai Santiprabhob
By The Nation

The Bank of Thailand has asked banks to accelerate and widen financial assistance for businesses affected by the Covid-19 pandemic.

After the February 28 announcement of the central bank’s incentives encouraging banks to offer relief measures to their clients, 30,000 borrowers have seen their debts restructured with a combined value of Bt234 billion through rate reduction and extension of repayment periods, Central bank governor Veerathai Santiprabhob said on Wednesday (March 18).

Some banks have even set up one- stop service for this purpose, he added.

However, the number is insignificant when compared to the vast spread of businesses reeling from the Covid-19 impact, he said.

Bankers have been asked to step up and widen relief measures in support of borrowers, especially small and mid-sized enterprises, Veerathai said .

Moreover, they were also told to brace for plan B should the virus spread intensify. For example, they would have to prepare enough cash in case more money are being withdrawn for various purposes. Banks also have to make sure capacities of their electronic payment systems can cope with a sudden spike in transactions, he said.

Central bank will work closely with commercial banks and state-owned financial institutions to ensure smooth functioning of the financial system at this time, he added.

Veerathai held the VDO conference on Wednesday with bankers on the business impact of the virus and its latest development .

U.S. stocks, global debt, oil tumble #ศาสตร์เกษตรดินปุ๋ย

#ศาสตร์เกษตรดินปุ๋ย : ขอบคุณแหล่งข้อมูล : หนังสือพิมพ์ The Nation

https://www.nationthailand.com/business/30384373?utm_source=category&utm_medium=internal_referral

U.S. stocks, global debt, oil tumble

Mar 18. 2020
By Syndication Washington Post, Bloomberg · Robert Brand · BUSINESS, US-GLOBAL-MARKETS 

Financial markets continued to spasm Wednesday, with U.S. stocks reversing Tuesday’s rally, as the economic fallout from the pandemic outpaces the massive response from governments and central banks.

The S&P 500 fell almost 6%, wiping out Tuesday’s rally, sparked when the Trump administration considered upward of $1 trillion in spending and the Federal Reserve dusted off crisis-era programs to stabilize financial markets.

Treasuries were steady after the biggest yield jump since 1982 and municipal bonds extended deepest rout since 1987 as markets braced for the potential flood of spending. European bonds came in for a bashing. Oil dropped to an 18-year low. The dollar strengthened a seventh straight day, while the pound hit its lowest level against the greenback since 1985.

Governments have pledged or are considering massive fiscal support to offset the economic shock from the pandemic, with the Trump administration moving toward a big package, but the virus continues to spread at a pace that is forcing massive shutdowns across the globe.

“The missing fundamental ingredient for a sustainable recovery in risk appetite is some evidence that the growth of global Covid-19 infection rates is peaking,” said Paul O’Connor, head of multi-asset at Janus Henderson Investors. “Clearly, we are not there yet.”

The planned U.S. stimulus could amount to $1.2 trillion, aiming to stave off the worst impact of a crisis that already looks set to plunge many of the world’s economies into recession. Meantime, the Federal Reserve reintroduced additional crisis-era tools to stabilize financial markets. Those responses came after stresses appeared in the short-term funding markets.

“I don’t think we’re out of the woods yet in terms of liquidity,” Mark Konyn, chief investment officer at AIA Group in Hong Kong, told Bloomberg TV. “It’s a question of when the fiscal measures will have the most efficacy.”

In Germany, Angela Merkel said the government will not rule out joint European Union debt issuance to help contain the impact.

These are the main moves in markets:

Stocks:

– The S&P 500 Index fell 5.7% to 2,385.51 as of 11:26 a.m. New York time.

– The Dow Jones Industrial Average decreased 5.8% to 20,004.37, the lowest in more than three years.

– The Nasdaq Composite Index dipped 4% to 7,041.18.

– The MSCI All-Country World Index declined 4.7% to 404.20, the lowest in more than three years.

Currencies:

– The Bloomberg Dollar Spot Index gained 1.5% to 1,272.78, hitting the highest in more than three years with its seventh straight advance and the largest rise in almost four years.

– The Japanese yen depreciated 0.3% to 108.04 per dollar, the weakest in more than two weeks.

– The euro declined 1.1% to $1.0879, the weakest in more than three weeks.

– The British pound decreased 2.1% to $1.1798, reaching the weakest on record with its seventh consecutive decline.

Bonds:

– The yield on 10-year Treasuries dipped one basis point to 1.07%.

– Britain’s 10-year yield increased 20 basis points to 0.756%, the highest in almost 10 weeks on the biggest climb in more than six years.

– Germany’s 10-year yield advanced 16 basis points to -0.27%, hitting the highest in eight weeks with its seventh straight advance.

– Ireland’s 10-year yield gained 15 basis points to 0.499%, reaching the highest in about 10 months on its fifth consecutive advance.

Commodities:

– West Texas Intermediate crude fell 13.2% to $23.39 a barrel, the lowest on record with the largest fall in more than a week.

– Gold depreciated 1.8% to $1,501.13 an ounce, the weakest in 12 weeks.

German bunds post longest losing streak in 2 ½ years #ศาสตร์เกษตรดินปุ๋ย

#ศาสตร์เกษตรดินปุ๋ย : ขอบคุณแหล่งข้อมูล : หนังสือพิมพ์ The Nation

https://www.nationthailand.com/business/30384372?utm_source=category&utm_medium=internal_referral

German bunds post longest losing streak in 2 ½ years

Mar 18. 2020
By Bloomberg · John Ainger · BUSINESS, WORLD, US-GLOBAL-MARKETS, EUROPE

German bonds — some of the safest assets in the euro area — are throwing a tantrum. Bunds, as they’re called in the market, have fallen for seven consecutive days, taking their yield more than 60 basis points higher from a record low of -0.91%. It’s their longest run of losses in two-and-a-half years.

For traders, it is bringing back memories of 2015, when German bonds sold off rapidly following a weak auction. That snapped a rally built on expectations for quantitative easing from the European Central Bank.

In terms of sheer speed, the sell-off is even quicker this time round — it has seen the biggest five-day jump in yields since 1990.

The ECB is currently seen as being almost out of ammunition to combat another slowdown, yet governments are finally taking up the baton with huge spending pledges. While Germany has very stringent debt-limit rules, those are showing signs of coming loose as the coronavirus disrupts the economy.

“A move in 10-year bund yields back above zero is not sustainable but it is a very real possibility over the next week,” said Richard Kelly, head of global strategy at Toronto-Dominion Bank in London. “We are in the eye of the storm for market pricing in both the liquidity strains and fiscal fears.”

Other factors are at play too. Fund managers are looking to sell assets in a bid to hold cash, which provides more flexibility and also allows them to prepare for potential redemptions by investors. There are also calls for euro-wide bond issuance, which would dampen the allure of bunds. Liquidity too is very poor, exacerbating the sell-off.

“Market participants are selling everything that still has value to build up defenses against outflows or liabilities they are facing,” said Christoph Rieger, head of fixed-rate strategy at Commerzbank. “A lot of longs had been built in recent weeks.”

German 10-year yields rose as much as 23 basis points to minus 0.21%, the highest level since January. Those on 30-year bonds rose into positive territory for the first time since February.

Still, the prospect of the whole curve soon emerging from negative territory is an unlikely one for ING Groep.

“It is possible only if the ECB confirms they intent on letting markets to their own devices,” said Antoine Bouvet, senior rates strategist at ING. “It is a possibility but honestly given the degree of volatility, I think the probability of them realizing their mistake is growing fast.”

Warren Buffett says negative rates are puzzling, but not scary #ศาสตร์เกษตรดินปุ๋ย

#ศาสตร์เกษตรดินปุ๋ย : ขอบคุณแหล่งข้อมูล : หนังสือพิมพ์ The Nation

https://www.nationthailand.com/business/30384369?utm_source=category&utm_medium=internal_referral

Warren Buffett says negative rates are puzzling, but not scary

Mar 18. 2020
Warren Buffett, chairman and chief executive officer of Berkshire Hathaway Inc., speaks to media Omaha, Neb., on May 3, 2019. MUST CREDIT: Bloomberg photo by Houston Cofield.

Warren Buffett, chairman and chief executive officer of Berkshire Hathaway Inc., speaks to media Omaha, Neb., on May 3, 2019. MUST CREDIT: Bloomberg photo by Houston Cofield.
By Syndication Washington Post, Bloomberg · Katherine Chiglinsky · BUSINESS, US-GLOBAL-MARKETS

Warren Buffett said the prospect of negative interest rates is a bit confusing. “They puzzle me, but they don’t scare me,” Buffett said in a Yahoo Finance interview when asked if negative rates frighten him.

U.S. policymakers have been seeking to grapple with the economic fallout of the coronavirus pandemic, with the Federal Reserve on Sunday cutting its benchmark interest rate by a full percentage point to near zero. While Fed Chairman Jerome Powell said at the time that he did not think negative rates would be appropriate policy in the U.S., markets have seen the yield on the 10-year U.S. Treasury dip as low as 0.31% earlier this month.

Buffett, the chairman and chief executive officer of Berkshire Hathaway Inc., said earlier this month the effects of the virus and an oil shock were “a big one-two punch.” He later announced that shareholders would be barred from attending his company’s annual meeting given the spread of the virus.

The billionaire investor has long favored investing in stocks over bonds, building up an equity portfolio that topped $248 billion at the end of last year. Buffett said in his annual shareholder letter, released in February, that it was almost certain that equities would outperform long-term, fixed-rate debt instruments in the long run if current interest rates and low corporate taxes were to persist.

But he cautioned in the Yahoo Finance interview, conducted last week and released Wednesday, that he’s not an expert on forecasting the path of rates.

“I have never been able to predict interest rates,” Buffett said. “Interest rates are important, but we don’t think they’re knowable.”

Boeing asks for ‘at least $60 billion’ as Trump expresses support for bailout #ศาสตร์เกษตรดินปุ๋ย

#ศาสตร์เกษตรดินปุ๋ย : ขอบคุณแหล่งข้อมูล : หนังสือพิมพ์ The Nation

https://www.nationthailand.com/business/30384304?utm_source=category&utm_medium=internal_referral

Boeing asks for ‘at least $60 billion’ as Trump expresses support for bailout

Mar 18. 2020
File photo by Syndication Washington Post, Bloomberg

File photo by Syndication Washington Post, Bloomberg
By The Washington Post · Aaron Gregg · NATIONAL, BUSINESS

WASHINGTON – President Donald Trump said in a press conference Tuesday that he supports a bailout for Boeing, which has been reeling from the combined economic fallout of the global pandemic and a prolonged safety crisis involving its flagship commercial jetliner.

Without providing details on a bailout package the president said “we’ll be helping Boeing,” which previously confirmed it was in discussions with top government officials about short-term access to cash. Boeing’s stock price has lost 44% of its value in the past five days alone.

Trump alluded to troubles with the 737 Max jet, which has been grounded for more than a year after equipment problems played a role in two deadly crashes.

“It was unthinkable what happened to Boeing…. unthinkable,” Trump told reporters. “Probably I would [have] considered it the greatest company in the world prior to a year ago now they get hit 15 different ways. They were doing a getting… it was coming along well and then all of a sudden this hits. So we’ll be helping Boeing.”

Shortly after the president’s comments Boeing published a statement saying there should be a minimum of $60 billion in “public and private liquidity, including loan guarantees” for the aerospace manufacturing industry. The details of a potential bailout have not been announced.

“We appreciate the support of the President and the Administration for the 2.5 million jobs and 17,000 suppliers that Boeing relies on to remain the number one US exporter, and we look forward to working with the Administration and Congress as they consider legislation and the appropriate policies,” Gordon Johndroe, vice president of communications at Boeing, said in a statement sent to reporters.

“Until global passenger traffic resumes to normal levels, these measures are needed to manage the pressure on the aviation sector and the economy as a whole,” Johndroe wrote.

The company confirmed Monday that it had been in discussions with the “government leaders” about short-term access to public and private funds.

“Until global passenger traffic resumes to normal levels, these measures are needed to manage the pressure on the aviation sector and the economy as a whole,” Johndroe wrote.

Boeing’s request for public help underscores the dire financial straits the company finds itself in, as dual crises threaten to severely complicate its return to financial health. On March 13, the company drew out the full amount of its $13.8 billion private loan, citing concerns about whether it would have access to cash should the markets worsen. It also completely halted new hires.

The coronavirus pandemic and its related market volatility came at a time when Boeing’s business was already vulnerable. The company has struggled to convince regulators that the 737 Max ― the newest version of its best-selling jet ― is safe to fly after two deadly crashes in Ethiopia and Indonesia killed hundreds of people. After Boeing leadership admitted that the jet’s flight control systems played a role in both crashes regulators have continued to find problems with the plane, repeatedly pushing back the jet’s re-certification timeline. It shut down its 737 Max production lines late last year after experiencing its toughest year in company history.

Boeing has suffered along with the broader aviation industry as travel bans have slowed new bookings. Last week Goldman Sachs analysts predicted there would be 7% decline in air traffic this year that will prompt many airlines to defer purchases of new planes.