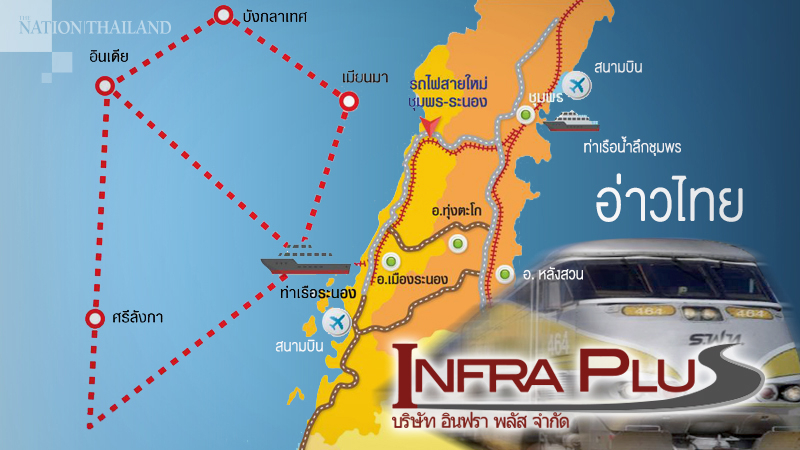
The Office of Transport and Public Policy and Planning has hired Infra Plus Consulting for Bt22 million to conduct a study on its plan to build an efficient transport link between the Eastern Economic Corridor (EEC) and the South through Ranong province.
The move is part of the government’s plan to create a transport link between EEC, covering the provinces of Rayong, Chonbur and Chachoengsao, and other parts of the country.
The study should be completed by July next year, the office’s deputy director general Wilairat Sirisoponsilp said.
The plan focuses on upgrading the deep sea port in Ranong and turning it into a trading gateway for the Andaman Sea to accommodate the transfer of goods from EEC to countries that are members of the Bay of Bengal Initiative for Multi-Sectoral Technical and Economic Cooperation (BIMSTEC) as well as to Europe, Middle-East and Africa.
BIMSTEC comprises Bangladesh, Bhutan, India, Nepal, Sri Lanka, Myanmar and Thailand.
NESDC to tap Bt100 billion for funding labour training
EconNov 16. 2020Deputy Prime Minister Supattanapong Punmeechaow
By The Nation
The National Economic and Social Development Council (NESDC) would propose new projects worth Bt100 billion to the Cabinet related to labour skills training and for investments in projects in the communities, council secretary-general Danucha Pichayanan said.
The projects would be funded from the Bt400-billion budget, which is part of the proposed Bt1-trillion borrowing to fund Covid-19 stimulus programmes, added Danucha, who is secreary of the state committee tasked with screening budget requests under the borrowing plan.
The Bt100-billion spending is also in line with Deputy Prime Minister Supattanapong Punmeechaow’s policy to invest Bt400 billion focused on labour upskilling and reskilling.
Meanwhile, Supattanapong has instructed the Eastern Economic Corridor Office and the Board of Investment to seek ways to lure more foreign investment into Thailand.
Earlier, EEC Office secretary-general Kanit Sangsubhan said that the EEC office would adjust its five-year investment plan to adapt to the changing global situation.
The 2020-24 plan for infrastructure and targeted industries would be revised in light of US president-elect Joe Biden’s strategy to promote eco-friendly businesses.
Kanit said the EEC would focus more on trade and investment collaboration with the US, as well as woo foreign investment in new technologies such as 5G wireless broadband.
By The Washington Post · David J. Lynch · NATIONAL, BUSINESS, US-GLOBAL-MARKETS The uncontrolled coronavirus outbreak is prompting government officials across the nation to impose new restrictions on consumers and businesses, sapping the economy’s momentum and delaying the recovery of millions of jobs lost during the recession.
Washington’s failure to provide additional financial support is compounding the economic distress. Though Federal Reserve Chair Jerome Powell this week repeated his call for a fresh round of pump-priming, the economy for now is left to navigate a winter of disease and loss unaided.
On Friday, Virginia Democratic Gov. Ralph Northam tightened limits on restaurants and indoor gatherings, effective at 12:01 a.m. Monday, while the governors of California, Oregon and Washington state issued a joint statement discouraging travel and advising visitors to quarantine upon arrival for 14 days. The mayor of New York City, meanwhile, warned parents that public schools could close as soon as Monday.
Similar measures are taking effect or under consideration elsewhere, including Chicago, where the mayor on Thursday issued a stay-at-home advisory just hours before Illinois Democratic Gov. J.B. Pritzker threatened a mandatory statewide order. The renewed clampdown is reminiscent of the worst days of the pandemic in early March when sports leagues, movie theaters and restaurants abruptly went into hibernation in hopes of curbing the contagion.
Those steps were only partly successful and came at great cost. By the end of June, the economy had shrunk by $2.2 trillion – more than Italy’s entire annual output. Now as communities around the country inch toward new shutdowns, the economy is again at risk. Consumers are growing more pessimistic about the future, according to the latest University of Michigan confidence gauge. And even before new restrictions were announced, they had begun cutting back on spending.
“We see stronger growth in 2021. But we need a bridge to get there,” said economist Gregory Daco of Oxford Economics. “The outlook is honestly quite dark.”
The backsliding comes after a stronger-than-expected rebound from this spring’s abrupt recession. A bit more than half of the 22 million Americans who lost their jobs when nonessential businesses closed have returned to work, and today’s 6.9% unemployment rate is well below the double-digit figures that most Wall Street economists originally had forecast. Output expanded in the third quarter at a record rate.
Yet with more than 11 million still jobless, the United States is in danger of squandering the hard-won progress it has made in rebuilding the economy. On Friday, House Speaker Nancy Pelosi, D-Calif., said the rampaging virus represented “an emergency of the highest magnitude.” But she and Senate Majority Leader Mitch McConnell, R-Ky., have held no talks on a new rescue package.
In El Paso, local officials have deployed 10 mobile morgue trailers to handle a backlog of corpses. The county’s top elected official this week extended a shutdown of nonessential businesses until Dec. 1, ordering residents to stay home and avoid travel.
The pandemic has driven roughly 300 companies out of business in the border community, according to David Jerome, the president of the local chamber of commerce. An additional 300 companies – restaurants, hair salons and retail shops – have only enough cash on hand to survive for less than a month.
“We’re hitting a bit of a tipping point,” Jerome said. “People are getting to the point where they’re pretty stretched. People are vulnerable.”
Eight months into a historic crisis, the United States appears to be suspended in a sort of economic purgatory. The labor market is slowly healing, with initial unemployment claims falling for four straight weeks. But the virus outlook is grim and getting grimmer.
On Thursday, the United States for the first time reported more than 150,000 cases in a single day. Within the next week, the daily total will top 200,000 and is likely to reach 300,000 by early December, according to Ian Shepherdson, chief economist for Pantheon Macroeconomics.
By mid-December, hospitals will be swamped with twice as many coronavirus patients as during the pandemic’s earlier waves “unless most large-population states impose much more severe restrictions on the leisure and hospitality sectors, and on indoor gatherings, very soon,” he wrote in a note to clients Friday.
Consumers already have begun retrenching. Spending by 30 million Chase credit and debit cardholders through Nov. 9 was 7.4 percent below last year’s level and had “fallen notably” over the past two weeks, according to economist Jesse Edgerton of JPMorgan Chase.
Investors are profiting despite the worsening health situation. On Friday, the Dow Jones industrial average rose nearly 400 points and is up more than 11 percent this month. Yet, millions of American households are suffering a silent financial squeeze.
Between the end of September and the end of October, the number of Americans saying it was “very difficult” to pay their usual household expenses rose by more than 2.3 million to 34.8 million, according to the Census Bureau’s pulse survey.
In Los Angeles, Micah Martin, 57, has been struggling to survive since losing his job as a health-care training consultant. He finally received unemployment benefits this summer just as he was preparing to move back to his parents’ home in Oklahoma.
“Since then, it’s been living off fumes,” he said. “I’m aggravated that Nancy Pelosi and McConnell haven’t come up with a compromise. It’s really put a hardship on me and a lot of other people.”
Los Angeles County health officials warned on Friday that tighter activity limits may be imminent if a recent surge in coronavirus cases isn’t contained. The county already is operating under the most restrictive conditions in California’s four-tiered system.
“Covid seems to be out of control here,” Martin said. “I haven’t been to a restaurant since February.”
There are reasons to hope the economy will fare better in the next few months than it did during the pandemic’s first wave. Doctors have more experience treating covid-19, the disease caused by the coronavirus. More Americans are wearing masks and practicing social distancing. And a highly effective vaccine could be widely available by April, according to Anthony Fauci, the nation’s leading infectious-disease specialist.
“The American people’s reaction to the surge will be significantly different from what it was in the spring,” said Michael Strain, an economist with the American Enterprise Institute. “The risk of dying has gone down considerably relative to the spring. People may be willing to take more risks.”
That seems to be true in the resort town of Branson, Mo. Gail Myer, vice president of family-owned Myer Hotels, said the company has kept employees and guests safe through mask-wearing, social distancing and enhanced sanitizing and hygiene.
Though business is down significantly, and he has reduced his workforce by one-third, Myer said October was the company’s best month this year. November could be even better.
“People are tired of not being able to do things they consider normal, and they are also figuring out how to travel comfortably,” Myer said. “I think the economy in the U.S. is getting better and people are figuring out how to make it work for them.”
But the $3 trillion in federal support that cushioned the blow to the economy in the spring is now absent. The resurgent virus may depress activity no matter what government officials do.
“More businesses will be at risk of permanently going out of business, which would dampen labor demand and potentially spur new rounds of layoffs. This suggests the labor market recovery could meaningfully slow or even reverse in coming months as the country tries to get the virus under control,” economists at Bank of America said Friday.
In Chicago, restaurateur Kevin Boehm, 50, closed two of his 20 restaurants and laid off 1,800 of his roughly 2,000 employees in the spring. With the virus spreading uncontrollably, city officials on Oct. 30 reimposed a ban on indoor dining just one month after they had relaxed restaurant capacity limits.
Over a 27-year career, Boehm has had an oven explode in his face and seen a restaurant burn down. But with revenue off by 80 percent, the pandemic has pushed him and his partner in the Boka Group to the brink.
Now, as Boehm contemplates multimillion-dollar financial losses and the prospect of additional layoffs, he is looking to Washington.
“We need Republicans and Democrats to step up and give us the help we need,” he said. “You can only take so many punches.”
The House last month passed legislation to provide $120 billion in grants to independent restaurants amid warnings that 85% of them could fail without assistance. But the Senate has yet to act on the measure.
Ryan Rivett, chief executive of My Place Hotels of America, is also counting on new stimulus legislation. His extended-stay hotel chain remained open throughout the pandemic with managers of some properties sleeping on site to compensate for reduced staffing.
Rivett received a forgivable government loan earlier this year, which was intended to prevent layoffs. But while he can adjust his labor costs as demand fluctuates, his loan payments are less flexible.
“The absence of stimulus is our bigger worry,” he said. “I don’t want to lose our business because we can’t service our debt.
The economic outlook is clouded by the limited nature of some new restrictions. As the escalating health emergency threatens to overwhelm hospital systems, restrictions are spreading to politically conservative states, such as West Virginia, Iowa and Wyoming, that had resisted such measures during earlier phases of the pandemic.
But such efforts remain controversial. In El Paso, Texas Attorney General Ken Paxton is challenging County Judge Ricardo Samaniego’s shutdown order.
In New Germany, Minn., Jean Stelten-Beuning, owner of Top Dog Country Club, an upscale dog-boarding facility, is worried about the next few months.
Last year, at her 35-acre site, complete with a heated canine swimming pool, she boarded 105 dogs over Thanksgiving weekend. Now as officials urge caution about traveling for the holiday, she expects just 35.
She has halved her 28-person staff, as her revenue dropped 55 percent. The state’s daily case total this week reached a new high and the governor ordered new limits on restaurants and other indoor gatherings.
“If the numbers keep growing and these shutdowns keep expanding, I have no idea what’s going to happen,” she said. “It’s going to be pretty bleak.”
MEA provides tree-trimming course to staff for safety and better landscaping
Nov 14. 2020
By THE NATION
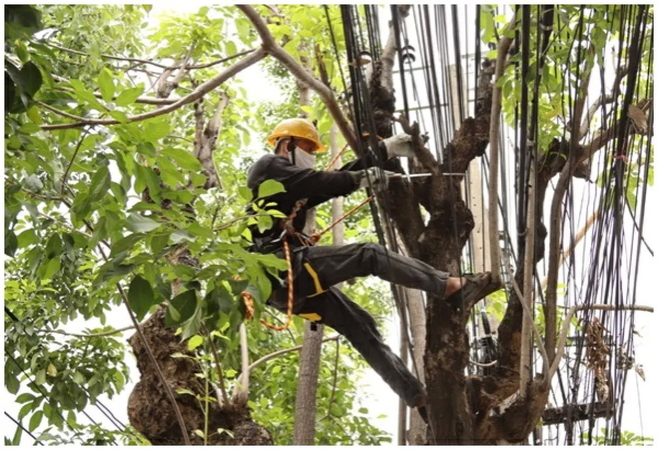
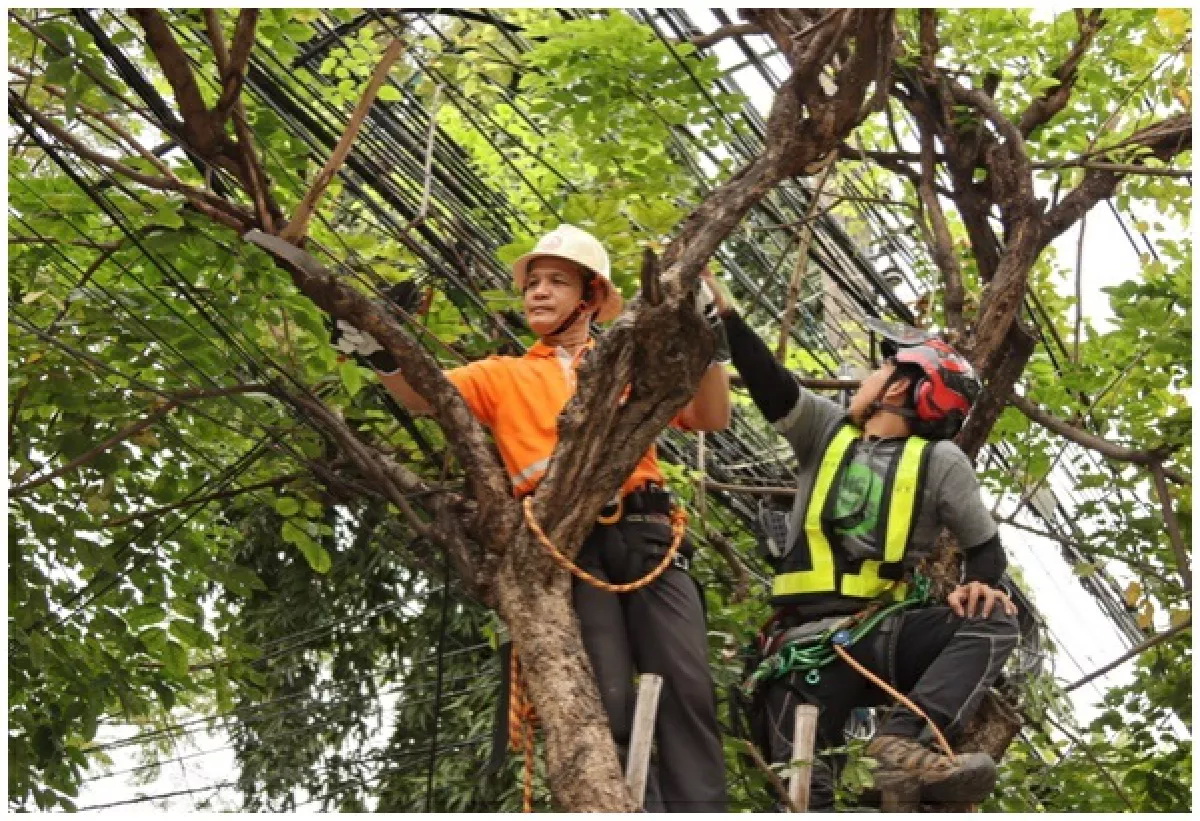
The Metropolitan Electricity Authority (MEA) organised a tree-trimming course from November 11-13 at its Sam Sen headquarters in Bangkok.
The MEA wanted its staff and contractors to improve their skills in tree trimming and maintenance as well as promote personnel and public safety while working on big trees.
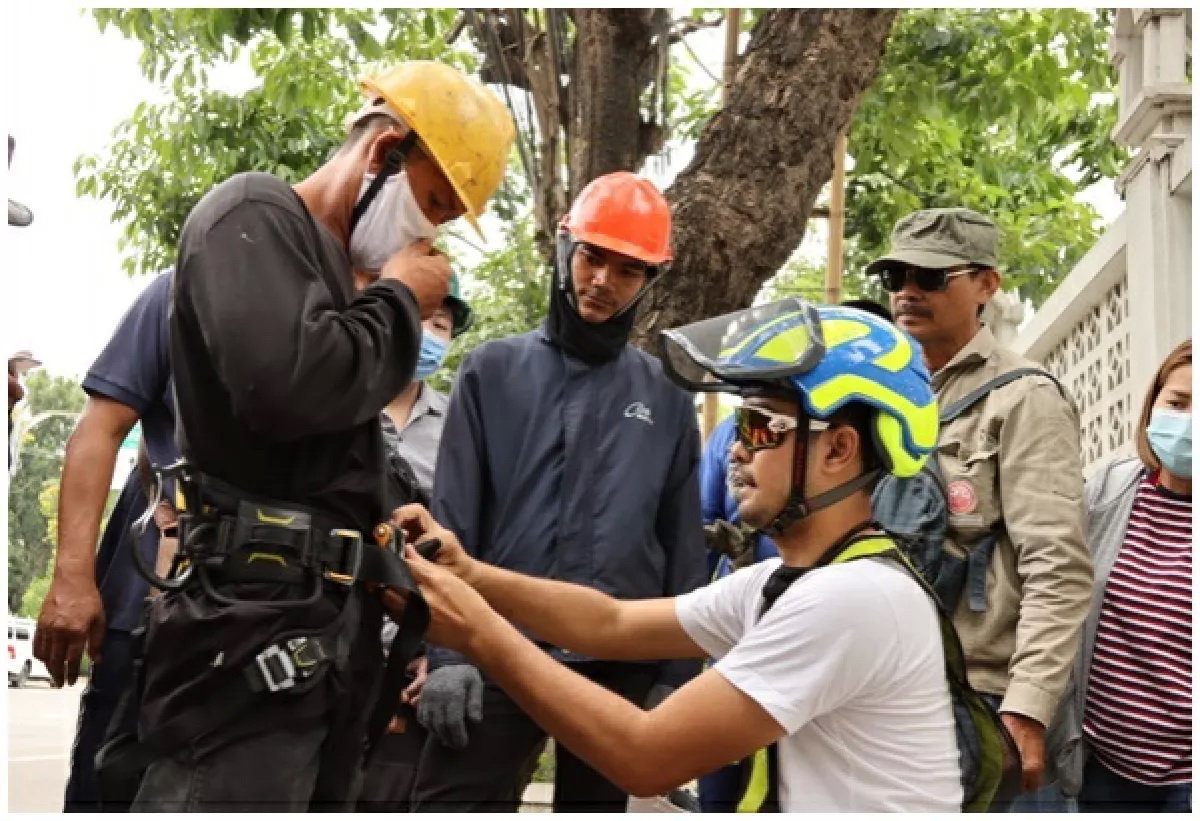
“The programme was a collaboration between the MEA, the Faculty of Forestry at Kasetsart University and the Big Tree Network, which sent experts to give lectures on tree trimming and maintenance, tree risk assessment, as well as uses of ladder and safety equipment,” said Chanvet Yuwachit, deputy MEA governor.
“Participants also practised using an aerial vehicle to trim tree branches along powerlines while maintaining safety standards to prevent electric shocks and branches falling off that could pose a threat to pedestrians and property.
“We expect that the training course would enable workers to work on trees in city areas and near powerlines according to the arboriculture principle, which would improve the landscape and reduce the risk of tree branches damaging powerlines or causing blackout in the areas,” he added.
“This course is a part of the MEA’s efforts in promoting work safety and power stability in city areas,” Chanvet said.
Siam Commercial Bank (SCB) is supporting adoption of the Revenue Department’s new e-Withholding Tax system for businesses by waiving its e-Withholding Tax service fees next year for businesses who apply between now and March 31, 2021.
The e-Withholding Tax system is designed to boost convenience and cut costs of the tax withholding process for businesses.
The new online process will also help eliminate operational errors that are part and parcel of paper-based processes while increasing transparency and efficiency.
SCB will act as an intermediary for the Revenue Department by deducting withholding tax on behalf of businesses, helping them to reduce or eliminate time-consuming preparation of documents needed for paper tax filing.
The Revenue Department introduced the e-witholding tax system earlier this year in partnership with 11 banks. The 11 participating banks are SCB, Krungthai, Kasikornbank, the Bank for Agricultural and Agricultural Cooperatives, Bangkok Bank, Mizuho Bank (Bangkok branch), Krungsri, Sumitomo Mitsui Banking Corporation, Standard Chartered (Thai), TMB and the Land and Houses Bank.
Charoen Pokphand Foods (CPF) has registered Bt7.475 billion net profit in the third quarter of 2020, a 23 per cent increase from the same period last year. The income boosted 9-month earnings to Bt19.614 billion, up 36 per cent year on year. Earnings before interest, tax, depreciation and amortisation (EBITDA) jumped 87 per cent on year to Bt61.658 billion, the highest-ever in the company’s history.
Prasit Boondoungprasert, CEO of CPF, attributed the improved performance to an African Swine Fever (ASF) outbreak which led to pork shortages and boosted pork prices above last year’s level, as well as greater profitability of the aquaculture business in Thailand following adjustments in marketing strategies and business model.
Prasit said that CPF expected earnings growth to be sustained next year, due to business and capacity expansion in several countries. Pork prices may soften from this year’s level but would remain high, he added.
Meanwhile, CPF is set to start realising profits from its swine business in China, which is under the acquisition process following approval of minor shareholders in late August.
Oil falls below $41 with surging covid cases menacing demand
EconNov 14. 2020Storage tanks located near a dock for Hornbeck Offshore Services, Inc. oil industry support vessels in Port Fourchon, La., on June 11, 2020. MUST CREDIT: Bloomberg photo by Luke Sharrett.
By Syndication Washington Post, Bloomberg · Alex Longley · BUSINESS, US-GLOBAL-MARKETS
Oil fell for a second day — dropping below $41 a barrel in New York — as the ongoing spread of coronavirus dampens the demand outlook.
As well as the surge in European coronavirus cases, there are also growing numbers in the U.S., Japan and South Korea, all of which are major oil consumers. The International Energy Agency and the Organization of Petroleum Exporting Countries revised down their demand forecasts this week.
At the same time, supply is rising as Libya opens the taps. The country’s production rose to 1.145 million barrels a day on Friday, according to a spokesman for its state-run National Oil Corp.
Crude is still up more than 8% this week, however, after news of a potential covid-19 vaccine breakthrough spurred a sharp jump in global markets on Monday. Futures have also been supported by indications that the OPEC+ alliance is closing in on a deal to delay a planned easing of output cuts. Still, three of the world’s top central bankers warned that a vaccine wouldn’t be enough to put an end to the economic challenges created by the pandemic as it continues to stymie consumption in some parts.
“There is a clear divergence in the oil demand recovery between Asia and Europe,” said Kevin Solomon, an analyst at brokerage StoneX Group. “We can assume that tighter lockdowns will resume in the United States, ultimately crimping oil demand.”
West Texas Intermediate for December delivery lost 1.9% to $40.35 a barrel as of 1:11 p.m. in London. Brent for January settlement slid 1.4% to $42.93.
In Asia, refiners are having to outbid one another to secure supplies in the spot market as buying interest from Chinese refiners grows. Meanwhile in Europe, where motorway traffic is down by almost 50% in some countries, demand is stuttering anew. That’s impacting crude, with six supertankers of unwanted North Sea oil continuing to float in the region.
Passive oil investors are also taking a more circumspect view on oil in the short term. More than $460 million has been pulled from the market’s largest exchange-traded funds so far this week, according to data compiled by Bloomberg.
U.S. consumer sentiment unexpectedly declines on economic views
EconNov 14. 2020Shoppers walk through the Queens Center shopping mall in the Queens borough of New York on Sept. 9, 2020. MUST CREDIT: Bloomberg photo by Peter Foley.
By Syndication Washington Post, Bloomberg · Jarrell Dillard · BUSINESS, US-GLOBAL-MARKETS, RETAIL U.S. consumer sentiment unexpectedly declined in early November as an increase in covid-19 infections and the election prompted Americans to reassess their outlooks for the economy and finances.
The University of Michigan’s preliminary sentiment index for November decreased to a three-month low of 77 from a final October reading of 81.8, data released Friday showed. The median estimate in Bloomberg’s survey of economists called for a reading of 82.
The measure of expectations dropped by nearly 8 points to 71.3, while a gauge of current conditions was little changed at 85.8. Interviews conducted following the election recorded a substantial negative shift in Republicans’ expectations and no gain among Democrats. The survey began Oct. 28 and concluded late on Nov. 10.
“Republicans now voice the least favorable economic expectations since Trump took office, and Democrats have voiced more positive expectations,” Richard Curtin, director of the survey, said in the report. “In the months ahead, the partisan gap is likely to enlarge, although the gains will be limited until a potential vaccine is approved and widely distributed.”
Consumers’ views about their current financial situations deteriorated, to well below the pre-pandemic peaks, the report showed. Net declines in household incomes were reported in early November for the first time since March 2014, with the largest decrease among lower income households and older Americans.
Less optimism about the state of the economy may damp prospects for the holiday shopping season against a backdrop of surging new virus infections across the country. The rising caseloads could weigh on sentiment in the coming months as some cities and states reinstate more restrictive measures.
A separate report on Thursday showed that the modest momentum in the labor market’s recovery remains intact, with initial jobless claims falling by the most in five weeks.
By Syndication Washington Post, Bloomberg · Rita Nazareth, Claire Ballentine · BUSINESS, US-GLOBAL-MARKETS Stocks climbed to a record as the rotation to economically-sensitive industries regained momentum even with a surge in coronavirus cases that could lead to more restrictions and crimp growth.
Both the S&P 500 and the Russell 2000 Index of small caps rallied to all-time highs, while the Dow Jones industrial average rose to pre-pandemic levels. All major groups in the equity benchmark advanced, with energy, industrial and financial companies among the biggest gainers. The tech-heavy Nasdaq 100 underperformed major gauges, with stay-at-home winner Zoom Video Communications Inc. tumbling. Walt Disney Co. jumped on solid results, and Cisco Systems Inc. climbed after upbeat sales projections. Tesla Inc., whose Chief Executive Officer Elon Musk tweeted he may have covid-19, fell. DoorDash Inc., the biggest U.S. food delivery platform, filed for an initial public offering.
The risk-on mood fueled a rotation into value and cyclical sectors, whereas more defensive industries underperformed. Stock funds attracted a record amount after positive results for a coronavirus vaccine, adding $44.5 billion in the week through Nov. 11, according to Bank of America Corp. and EPFR Global data. While the latest figures on covid-19 continued to fuel concern, with the surge in U.S. infections now spread to 49 states, the S&P 500 notched a second weekly rally.
“You have this push-pull,” said Tom Hainlin, national investment strategist at U.S. Bank Wealth Management’s Ascent Private Wealth Group. “As people become more optimistic, you get the recovery in the more cyclical sectors, and then as the optimism wanes a bit, you go back into the tech stocks.”
New York’s daily covid-19 cases exceeded 5,000, the highest for the state since April, as New York Mayor Bill de Blasio, D, warned parents to prepare for city schools to halt in-person classes as soon as Monday. California, Oregon and Washington state urged arriving people to self-quarantine, while Illinois reported a record number of daily infections and hospitalizations, a day after Chicago announced a stay-home advisory.
Federal Reserve Bank of St. Louis President James Bullard and New York head John Williams both voiced concerns about the economic impact of the pandemic, echoing previous comments from Fed Chairman Jerome Powell. U.S. consumer sentiment unexpectedly declined in early November as an increase in covid-19 infections and the election prompted Americans to reassess their outlooks. Meanwhile, a key measure of prices paid to U.S. producers decelerated in October, consistent with a pandemic that continues to limit pricing power.
U.S. stocks are poised for “a digestion period,” according to Keith Lerner, chief market strategist at SunTrust Private Wealth Management. He cited the S&P 500’s track record since 1990 after days when more than 60% of its component stocks reached 20-day highs, as they did Monday. There were 25 instances mentioned in a report Thursday. A month later, the S&P 500 was unchanged on average. Gains were posted over three-, six- and 12 months, with the latter period bringing an average increase of 12.5%.
These are some of the main moves in markets:
Stocks
–The S&P 500 gained 1.4% at 4 p.m. EST.
–The Stoxx Europe 600 Index was little changed.
–The MSCI Asia Pacific Index climbed 0.1%.
Currencies
–The Bloomberg Dollar Spot Index declined 0.4%.
–The euro advanced 0.2% to $1.1832.
–The Japanese yen appreciated 0.5% to 104.65 per dollar.
Bonds
–The yield on 10-year Treasurys rose one basis point to 0.90%.
–Germany’s 10-year yield decreased one basis point to -0.55%.
–Britain’s 10-year yield fell one basis point to 0.338%.
Commodities
–The Bloomberg Commodity Index was little changed.
–West Texas Intermediate crude fell 2.3% to $40.18 a barrel.
Banks’ credit-card divisions plan to tap more young customers next year to boost the growth of their business.
Somwang Toraktrakul, managing director of Krungsriayudhya Card Co Ltd, said the company will launch new products that are tailormade to tap the new generation, even though their spending through credit cards at present is not high.
The company is targeting a 7 to 8 per cent growth in card subscription next year, while it expects spending via its credit cards to grow 12 per cent.
Though spending via its credit cards in the past 10 months shrank 12 per cent, it is still an improvement from minus 50 per cent in March and April, he said.
The company’s credit-card subscription base at present totals 1.4 million cards, which is expected to rise to 1.5 million by yearend.
Thaweelap Rittapirom, Bangkok Bank’s executive vice president, said his bank will also focus on tapping the new generation next year.
It will take part in university activities to raise awareness of its BBL brand, which will make them think of BBL first when they want credit-card services.
The bank will also expand partnership in many sectors as part of efforts to boost the number of new cardholders and spending next year.
 Deputy Prime Minister Supattanapong Punmeechaow
 Federal Reserve Chair Jerome Powell
 Storage tanks located near a dock for Hornbeck Offshore Services, Inc. oil industry support vessels in Port Fourchon, La., on June 11, 2020. MUST CREDIT: Bloomberg photo by Luke Sharrett.
 Shoppers walk through the Queens Center shopping mall in the Queens borough of New York on Sept. 9, 2020. MUST CREDIT: Bloomberg photo by Peter Foley.